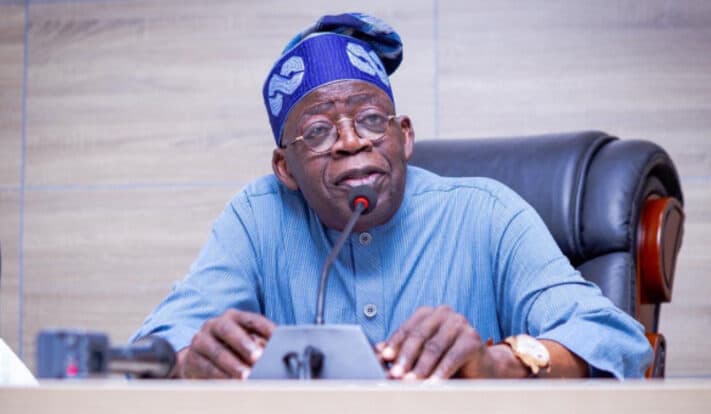
President Bola Tinubu has urged state governments to channel increased revenues into projects that directly improve living conditions for Nigerians. His call follows a World Bank report detailing a significant rise in public revenues and infrastructure spending since the administration introduced key economic reforms.
Tinubu said findings from the World Bank’s October 2026 Nigeria Development Update, titled Beyond the “Federal Purse: How Higher Revenues Reshaped State Priorities,” show that policy changes are strengthening the economy. However, he acknowledged that further efforts are required to translate fiscal gains into lower living costs and higher standards of living.
The report revealed that federation revenues grew by 69 percent in real terms between 2023 and 2025, with state governments emerging as the primary beneficiaries. States subsequently increased capital expenditure by 151 per cent in real terms over the period, directing the bulk of additional spending toward roads, transportation, agriculture, energy, and housing.
According to the World Bank, 29 of the 33 states reviewed shifted spending priorities toward economic infrastructure. Meanwhile, real social spending per person increased in all but one state.
The findings indicate that major structural measures, including the removal of the petrol subsidy and the unification of the foreign exchange market, have expanded subnational fiscal capacity. Nevertheless, the ultimate impact of these changes on household welfare remains the primary test of policy success.
Macroeconomic indicators show broader recovery
In a statement issued by Special Adviser to the President on Information and Strategy, Bayo Onanuga, Tinubu noted that the findings validate the administration’s fiscal direction.
“These findings confirm that the difficult but necessary decisions to remove the petrol subsidy, unify the foreign exchange market, and strengthen fiscal discipline have raised revenues, stabilised the economy, and created fiscal space for every tier of government to invest in its people,” the president said.
Read also: States’ bumper revenues push capital spending by over 182% in 4 years – World Bank
The World Bank report also indicated that Nigeria’s economy grew by 4.2 per cent in the first half of 2026, compared with 3.9 per cent in the corresponding period of 2025, despite economic spillovers from Middle East conflicts. The bank projected average annual growth of at least 4.4 per cent between 2026 and 2028, with poverty expected to decline gradually as economic expansion outpaces population growth.
Furthermore, the poverty rate has stabilised for the first time since 2019. On inflation, the rate dropped from 27.6 per cent in January 2025 to 15.2 per cent in December 2025, though higher global fuel prices linked to Middle East tensions have slowed the pace of decline. The World Bank expects inflation to ease to about 12 per cent by 2028.
Nigeria’s external position also strengthened during the period. The current account surplus rose to $12 billion—representing 7 per cent of gross domestic product—in the first half of 2026, up from $8.6 billion a year earlier. Gross external reserves expanded from $45.5 billion at the end of 2025 to $53.8 billion by late August 2026, providing a solid buffer.
At the subnational level, internally generated revenue grew in real terms across 31 of 35 states examined, while 21 states reduced their debt-to-GDP ratios between 2021 and 2025. Total public debt is projected to fall from 40 per cent of GDP in 2025 to 38.1 per cent in 2026.
Relief measures target household welfare
Despite improvements in macroeconomic indicators, Tinubu acknowledged that gains have yet to translate fully into everyday relief, particularly regarding food affordability, job creation, and access to essential services.
“The dividends of reform are becoming visible. But more work remains to ensure they fully translate into better living standards for every household, starting with lower food prices and decent jobs for our young people,” he said.
Read also: AI, energy shock, record debt to dominate IMF-World Bank meetings in Bangkok
Reaffirming his commitment to the Renewed Hope Agenda, Tinubu promised to scale up targeted cash transfers, accelerate compressed natural gas deployment, boost agricultural output, and broaden access to healthcare and education. Targeted cash transfers have reached more than 10 million households to date.
The president called on state governors to exercise fiscal prudence and prioritise investments that yield measurable improvements in living standards. Commending the economic management team, state governors, and key stakeholders for their cooperation, he stressed that subnational allocations must translate into shared prosperity across all communities.
Related News

