AI assistants are making it easier for consumers to search for products and compare options, but allowing software to complete a purchase introduces a different question: how much authority should an AI system have over a customer’s money?
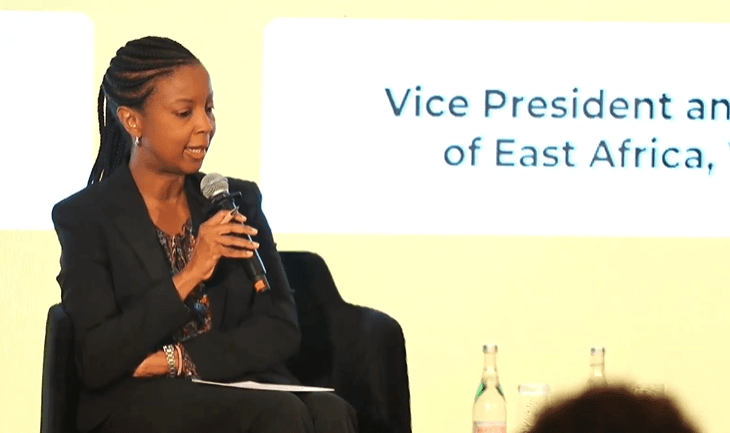
That question was central to Visa East Africa’s contribution to Glovo Kenya’s Future of Commerce Summit. Anne Kinuthia-Otieno discussed the potential for AI-assisted commerce alongside the payment infrastructure needed to support transactions initiated through new digital interfaces.
The summit included two figures that capture the gap between interest in the technology and confidence in letting it act. Visa cited research indicating that 89% of respondents surveyed would use an AI agent to shop, while only 29% trusted an AI agent to complete checkout.
The figures describe different levels of willingness. Consumers may be comfortable asking AI to search for products or compare options without being ready to let it submit an order and initiate payment. The distinction becomes more important as AI tools move from providing recommendations to taking actions on a customer’s behalf.
For payment providers, the challenge is to make that transition possible without leaving consumers uncertain about what they have authorised, how their credentials are used or what happens when a transaction goes wrong.
Shopping assistance is different from payment authority
An AI shopping assistant can help a customer identify a product, compare alternatives or narrow a list of choices. Those activities influence a purchasing decision, but the customer can still review the results and complete the transaction through a conventional checkout.
An AI agent with the ability to initiate a transaction has a broader role. Depending on how the service is designed, it may be able to select an item, submit an order or use a payment method according to instructions given by the customer.
That creates questions that do not arise in quite the same way when AI is used only for research. Customers need to know what instructions the system is following, what limits apply and whether they will be asked to approve a purchase before money changes hands.
A customer might authorise an agent to find a product below a specified price, for example, but that does not automatically mean the customer wants the agent to make additional purchases or accept unexpected fees. The system must distinguish between permission to search and permission to transact.
The challenge is not just whether the AI can complete a checkout technically. It is whether the customer understands and controls the authority being delegated.
How tokenisation can protect payment credentials
One of the technologies relevant to this challenge is payment tokenisation. Instead of exposing a customer’s underlying card credentials in every transaction, tokenisation uses a substitute value, or token, to represent those credentials within a defined payment context.
The objective is to reduce the need to expose the original card details while allowing an authorised transaction to take place. The way a token can be used depends on how the payment system and token are configured.
At the summit, Kinuthia-Otieno discussed transaction-specific tokens for AI-agent checkout. Such an approach can help connect payment authority to a particular transaction rather than treating access to a payment credential as unlimited permission to spend.
The security benefit depends on the implementation. Tokenisation is not, by itself, a guarantee that an AI agent will make the right purchase or that every form of misuse will be prevented. It is one part of a broader system that must also address authorisation, transaction limits, customer consent and the handling of disputes.
Those distinctions matter because an AI system may make a mistake even when payment credentials are protected. It could interpret a request incorrectly, select an unsuitable product or attempt to buy something outside the customer’s intended scope. Payment security needs to work alongside clear rules about what the agent is allowed to do.
Trust depends on control as well as security
The 89% and 29% figures cited at the summit suggest that willingness to use AI for shopping does not automatically translate into confidence in AI-led checkout. A customer can see value in receiving recommendations while remaining cautious about letting software commit money.
That gap is partly about security, but it is also about control and predictability. Consumers need to understand when an AI agent is making a recommendation, when it is preparing a transaction and when it has permission to complete a purchase.
Clear approval steps can help. So can spending limits, restrictions on the types of purchases an agent can make and transaction records that allow customers to see what happened. The appropriate controls will depend on the service and the degree of authority the customer grants it.
There is also a practical issue around accountability. If a customer disputes a purchase initiated by an AI agent, the process must establish what instructions were given, what action the agent took and how the payment was authorised. A secure payment credential alone does not answer every question about responsibility.
For merchants, the checkout experience must remain clear enough for customers to understand the final product, price and delivery conditions. An agent may reduce the effort needed to find an item, but it should not make the terms of the purchase harder to understand.
Visa’s broader payment initiatives address different parts of commerce
Kinuthia-Otieno also discussed Visa initiatives intended to support digital payments and business participation across different channels.
Visa Accept was presented as an app-based payment acceptance option for small businesses. Visa Pay was discussed in connection with virtual cards, digital onboarding and cross-border payments. These initiatives address different business needs, but they sit within a wider effort to make digital transactions easier to initiate and process.
Digitised payment activity can also create more usable records of a small business’s sales. Those records may help financial institutions assess trading activity when considering a business for financial services or credit. They do not guarantee that a business will qualify for financing, but they can provide evidence that may otherwise be difficult to assemble.
For AI-agent commerce, the requirement is more specific: payment systems need to recognise that a transaction may be initiated through software while preserving the customer’s ability to set limits and understand what has been authorised.
That requires coordination between the AI interface, merchant checkout, payment network and issuing institution. Each part has a different role, and the overall experience depends on the way those roles fit together.
The checkout experience will shape adoption
AI-assisted shopping can reduce the effort involved in finding products, but the final transaction remains a point where customers expect clarity and control. The willingness to use an AI assistant for discovery does not mean consumers are prepared to delegate every decision that follows.
The figures shared by Visa at the summit indicate that distinction remains significant among the respondents surveyed. They do not establish how quickly consumer confidence will change or which safeguards will prove most effective, but they underline the need to address payment authority as AI tools become more capable.
For merchants and payment providers, the task is to make AI-assisted purchases understandable, secure and consistent with the customer’s instructions. Tokenisation can help protect payment credentials, while transaction limits and clear approval processes can define the scope of an agent’s authority.
The wider test is whether consumers can benefit from AI assistance without feeling that they have surrendered control over their purchases. If the checkout process makes that boundary clear, AI agents may become a more practical part of digital commerce. If it does not, the convenience of automated shopping may not be enough to overcome consumer hesitation.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to editorial@techtrendsmedia.co.ke