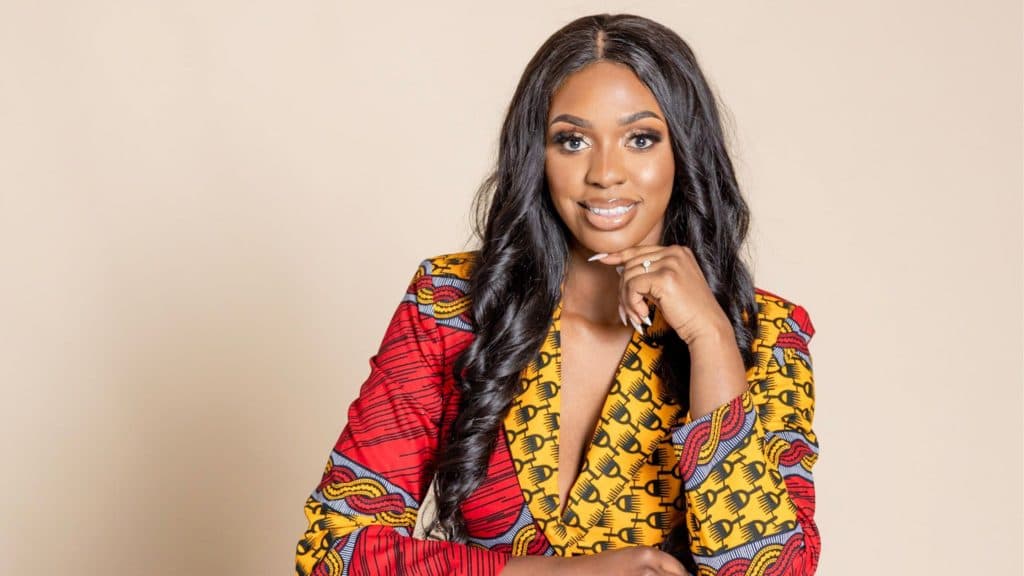
When Eunice Ajim launched her eponymous venture capital firm, Ajim Capital, in 2022, she expected to make as many as 80 investments.
The firm’s first $10 million fund ultimately backed 20 companies. Now raising a second fund, she says she is unlikely to invest in that many startups again, planning instead for a portfolio of around 30 companies.
“When I was getting started as a VC, I was very naive,” she told Condia.
Maturing as an African venture capitalist has meant an evolution in how Ajim assesses opportunities, though not necessarily in the sectors she invests in. Her experience has made her more deliberate about portfolio construction, the number of companies she backs, and the likelihood that those investments can generate returns.
Ajim Capital’s first fund was built around the conviction that fintech offered significant opportunities in Africa. It backed startups including Raenest, Dojah, TemboPlus, and Flex Finance. Her earlier angel investment portfolio also included Bamboo, LemFi, and Payhippo.
Even as fintech funding in Africa has fallen from its 2022 highs, Ajim remains convinced that opportunities exist in the sector. What has changed is her selectivity. Rather than abandoning fintech, she is looking more carefully at which companies can build defensible businesses and deliver meaningful returns.
Vertical software-as-a-service (SaaS) is another area where her thinking has evolved. Before the widespread adoption of AI, she saw considerable opportunity in software tailored to the needs of specific industries. But as AI tools make it easier for experienced developers and professionals to build bespoke software, the opportunity has become harder to assess.
In Africa, however, where many industries are still being digitised, she believes there is room for AI-enabled software businesses that solve specific operational problems.
“Obviously, in the day and age where we are, it’s not just purely vertical SaaS; it needs to have some sort of AI enabled in the software.”
The challenge of raising African venture capital
In September, Ajim hosted the Ajim Summit on the sidelines of the United Nations General Assembly, bringing together investors and selected founders to discuss investing in Africa. The conversations, she says, helped put the continent’s investment landscape into perspective.
Two panels stood out: one featuring institutional limited partners (LPs) that had never invested in Africa, and another featuring US venture capitalists with existing investments on the continent.
The discussion with institutional LPs offered a glimpse into why some large investors have stayed away from African funds. For institutions managing billions of dollars, an allocation to a relatively small Africa-focused venture or private equity fund may be too small to make a meaningful difference to their overall portfolios. Yet the work required to assess and approve that investment can remain substantial.
The result is a structural obstacle for African fund managers. Even when they can make a compelling case for their investment strategies, the size of their funds can make them difficult to accommodate within the allocation frameworks of larger institutions.
The panel featuring US venture capitalists offered a different perspective. Their experiences investing in Africa were not fundamentally different from those of investors elsewhere: some bets had failed, while others could become significant winners.
More importantly, some investors believed that their African portfolio companies could eventually return their entire global funds.
For Ajim, that was evidence that the continent can produce companies with outcomes large enough to matter even to global venture capital firms. The challenge is ensuring that investors recognise those opportunities and have the structures to pursue them.
Her own fundraising experience has brought the problem into sharper focus. As she raises her second fund, she says many LPs are concentrating on opportunities in the United States, particularly AI, rather than committing capital to African investment vehicles.
The shift reflects how venture capital follows investor sentiment. When a sector captures the market’s imagination, capital tends to concentrate around it, making it harder for fund managers pursuing other strategies to attract commitments.
US venture funding figures illustrate the scale of that concentration. In the first nine months of 2026, AI accounted for 82.7% of US venture funding. Ajim expects the current enthusiasm to moderate as the AI investment cycle evolves, potentially creating more room for other markets and strategies.
For now, however, African fund managers must compete with a US technology market offering investors the prospect of enormous returns and a more established route to realising them.
Why African founders need to prove more
The fundraising challenge has direct consequences for founders. African venture funds generally have less capital to deploy than their counterparts in more developed venture markets, limiting the number of early-stage companies they can back and the risks they can afford to take.
“Founders need to understand that it is not easy for us to take a bet on someone that is too early because we don’t have an infinite amount of money,” Ajim says.
She points to the relatively small number of Africa-focused venture capital firms that have raised funds exceeding $100 million. For these firms, too, much of their LP base consists of international institutions and entrepreneurs whose investment priorities may lie elsewhere.
This puts pressure on fund managers to demonstrate that their investments can generate returns. It also shapes the kinds of companies they are willing to back. An investor may be interested in a founder’s vision but still hesitate if the business is too early to establish demand, lacks a credible path to growth, or is unlikely to attract subsequent funding.
That pressure can encourage more conservative investment decisions, even in a market where many businesses still need early capital to prove their potential.
It also raises a broader question about whether venture capital alone can finance Africa’s businesses. Not every promising company will generate the scale or returns that venture investors require, and expecting every business to fit the model can leave viable opportunities underserved.
“The more you understand the VC model, the more you understand that other models need to exist for the VC model to work,” Ajim says.
For her, expanding the range of financing options available to African businesses is not an argument against venture capital. It is a recognition that the model works best when other forms of capital can support companies that do not fit its requirements.
Building relationships before the next fundraise
For founders who do fit the venture model, Ajim’s advice is to begin preparing for fundraising long before they need capital.
Relationships are crucial because investors do not discover companies exclusively through pitch submissions or public contact channels. Much of their deal flow comes from referrals from fellow investors and founders they have backed.
Founders should therefore spend time building relationships with entrepreneurs who have already raised funding, attending relevant events, and developing connections with investors before a fundraising round becomes urgent. Accelerators can help by giving founders practice in communicating with investors, exposing them to fundraising expectations, and providing access to useful networks.
But relationships alone are not enough. Founders still need to build products that customers want and businesses that can grow. A strong reputation among customers and fellow founders can help investors discover a company, while evidence of demand gives them a reason to invest.
Valuations also need to reflect the current environment. Ajim puts the sweet spot for a pre-seed investment at a valuation of $2 million to $5 million. At seed, valuations can reach $10 million, but she considers that an exception rather than the norm.
For companies generating between $5,000 and $10,000 in monthly recurring revenue, that traction can strengthen the case for investment, alongside the founder’s ability to build the product, manage the business as it grows, and raise subsequent rounds.
These are not universal thresholds for every African startup, but they offer a window into how one investor evaluates early-stage opportunities.
Ultimately, Ajim’s approach reflects a venture capital market in which conviction is balanced against limited resources. Her sector thesis remains intact, but the standards for backing a company have become more demanding.
As global investors chase AI opportunities in the United States, she sees a different possibility in Africa: AI-enabled software built for industries that are still being digitised and fintech startups that go beyond payments.
Whether that opportunity translates into successful investments will depend not only on the technology but also on founders’ ability to build durable businesses and the ecosystem’s ability to provide the capital they need to scale.