Moody's kept France's sovereign credit rating and outlook unchanged while warning that conditions have deteriorated over the past several months. According to the Financial Times on the 24th, the ratings agency a day earlier affirmed France at Aa3 and maintained its outlook at negative.
The decision offered unexpected relief to France, which has been under pressure from surging government bond yields, political deadlock and nationwide protests. Moody's refrained from a downgrade even though growth has slowed and the fiscal deficit has widened since its previous rating decision. The agency said it assumed that a deficit-cutting budget for next year will be adopted and that funding costs and social tensions will ease somewhat over the coming months.
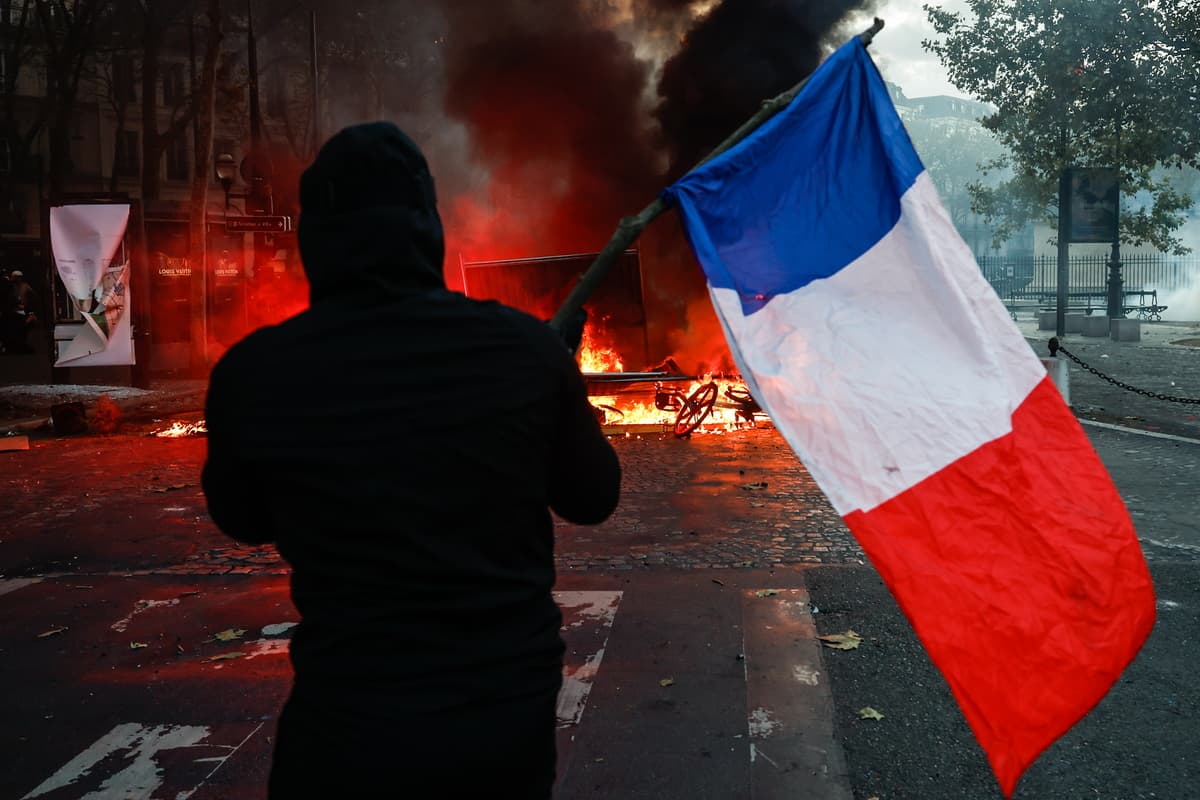
Even so, Moody's cautioned that the situation has worsened compared with what it had expected only a few months ago. In its report, the agency said slower growth and a wider deficit have pushed France's debt burden somewhat higher than previously expected, adding that government bond yields have risen faster than anticipated and that widespread social protests could constrain efforts to repair public finances.
Investor concerns are also mounting. France's government debt stands at about 120% of gross domestic product, the third-highest in the eurozone after Greece and Italy. The yield on France's 10-year government bond reached 5% this week for the first time since 2002, and its spread over German bunds widened to about 1.7 percentage points, the widest since 2011.
Moody's projects France will post a deficit equivalent to 5.2% of GDP next year. Prime Minister Sebastien Lecornu wrote on X that the announcement overturned the pessimistic forecasts of many "experts" and signaled to creditors that there is a path forward. He added that it is now up to lawmakers to deliver a budget for France consistent with the target of a 5% deficit this year.