The foreign remittance playbook in India is undergoing a systematic change. The decade-long strategy of earning in dollars, dirhams or euros, and remitting them to a mainland bank account in Mumbai or New Delhi, is no longer the only viable option for Non-Resident Indians (NRIs).
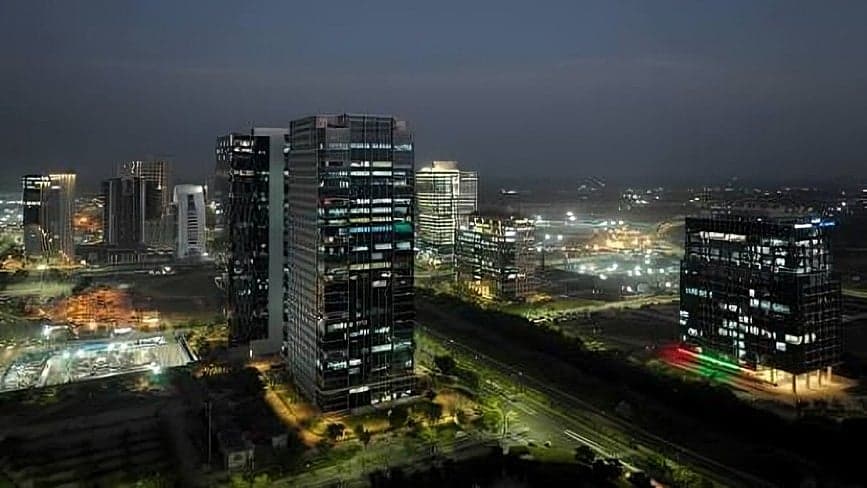
An 886-acre enclave between Ahmedabad and Gandhinagar—GIFT City (Gujarat International Finance Tec-City)—is rapidly rising in popularity for global Indian families remitting funds to avail investment opportunity into India.
The lure of GIFT City isn’t merely a patriotic nod to India’s financial modernisation. Rather, this shift is a calculated strategy driven by regulatory and tax benefits. As GIFT City operates outside mainland India’s jurisdiction, it is excluded from the capital controls, compliance hurdles and tax complexities that potentially trap or trim NRI wealth in India.
The complexities of repatriation
A prudent NRI investor can’t overlook the regulatory boundaries under Foreign Exchange Management Act (FEMA) when trying to repatriate capital from India. Let’s take the example of an NRI selling their equity stake in an unlisted Indian startup. In such instances, the funds may end up in the Non-Resident Ordinary (NRO) account of the NRI.
In accordance with the present FEMA regulations, am NRI is permitted to repatriate up to $1 million per financial year from eligible NRO account balances. That ceiling is a major hinderance for an NRI or a global Indian family office looking for easy flow of foreign exchange across regulatory borders.
In addition to this cap under FEMA, there are tax compliances that make repatriation daunting for many. Repatriating mainland NRO funds necessitates Form 15CA and Form 15CB—an arduous digitised declaration, along with a Chartered Accountant’s certificate verifying that all applicable taxes have been withheld at source. These additional procedures require coordination, costs and at times complex discussions between banks and Indian advisors hoping to satisfy numerous agencies involved in the process of repatriation.
Moreover, wrongly classifying overseas remittances or mixing the freely repatriable Non-Resident External (NRE) funds with restricted NRO funds can draw more than just a regulatory rap. The consequences may attract penalties and compounding proceedings, along with months of administrative logjam with the AD Bank.
These complexities are exacerbated as NRIs are now wary of Reserve Bank of India (RBI) and tax agencies have who have been infamously highlighted for their heavy handed approach towards venial breaches or weak bookkeeping on cross border capital flows.
The IFSC solution
GIFT City has now been offered as a solution to address the above issues having been carved out of the current mainland regulations.
Under Regulation 3 of the Foreign Exchange Management (International Financial Services Centre) Regulations, 2015 any financial institution or branch of a financial institution set up in the IFSC and permitted or recognised as such by the Government of India or a Regulatory Authority is treated as a “person resident outside India”.
In simple terms: GIFT City operates as an offshore financial centre from a legal, and jurisdictional lens, despite being physically located in Gujarat.
The gains for NRIs include:
GIFT City investments by NRIs in foreign currency can be freely repatriable, without the $1 million annual cap applicable to NRO balances
Capital gains, dividends or interest income can move in and out of India in Foreign currency which eliminates currency conversion friction and exchange-rate depreciation risk.
Tax incentives including a 10-year tax holiday under Section 80LA, zero capital gains tax on specified securities listed on IFSC exchanges.
Exemption from the cumbersome Portfolio Investment Scheme (PIS) approvals traditionally required by the RBI for NRI stock trading.
Smart money: Chasing smart ideas
In practice, this has transformed how global Indians approach cross-border transactions. Consider a Dubai-based family office looking to invest in Indian startups. Historically, the family faced an unappealing choice: invest directly under Foreign Direct Investment (FDI) rules—enduring rigid pricing guidelines and reporting requirements—or route the investment through Mauritius or Singapore, which increasingly invites tax-treaty scrutiny and General Anti-Avoidance Rules (GAAR).
Today, that same family has an option to establish or participate in a GIFT City Alternative Investment Fund (AIF) structure. With the International Financial Services Centres Authority (IFSCA) permitting 100% NRI ownership in IFSC funds, global families can pool foreign capital offshore and inject it into mainland Indian startups as domestic institutional capital—easily, transparently, and with seamless exit repatriation.
A similar shift is occurring across wealth management. Singapore was long the default hub for wealthy NRI single-family offices but rising local operating costs and heightened regulatory scrutiny have eroded that edge. Utilising IFSCA’s tailored family office frameworks, Indian promoters with global footprints are evaluating relocating their treasury operations to GIFT City, managing US equities, global debt, and Indian assets under a single, tax-neutral roof.
Efficiency, not evasion
It would be a mistake, however, to view GIFT City as a regulatory hideout. The IFSCA is building an institutional-grade jurisdiction modelled on the success of London and Singapore where compliance with global standards including Anti-Money Laundering (AML) standards and Financial Action Task Force (FATF) norms are founding principles for operations.
As for legit, NRI wealth, the Gift City option is compelling. Mainland India remains the engine to generate wealth, whereas GIFT City has become the vault where you may remit capital, invest through structures, hold for wealth creation and repatriate your capital without regulatory overhangs and long-term tax benefits. This offers NRIs the best of both worlds.
(The author is managing partner, Dewan P N Chopra & Co. Views are personal.)