For many parents, paying school fees is a responsibility that cannot wait. Retirement, on the other hand, often feels like a problem for another day.
When income is limited, and household expenses keep rising, parents make difficult choices. They pay school fees, buy textbooks, cover transport, provide meals and do everything possible to give their children opportunities they may not have had themselves. If anything remains, they may save a little. If nothing remains, retirement planning is postponed until things improve.
The intention is understandable. No parent wants to watch a child’s education suffer because the family cannot afford it. But when preparing children for the future consistently comes at the expense of preparing for their own later years, families may be solving one financial problem while quietly creating another.
The question is not whether parents should fund their children’s education or prepare for retirement. It is how they can plan for both without leaving either future entirely to chance.
The cost of always putting retirement last
Retirement planning is easy to postpone because its consequences are not immediately visible. A school fee deadline has a date. A child needs a uniform today. A university admission letter may arrive with payment instructions and a short deadline. Retirement, by comparison, can feel distant, particularly when a parent is still earning a regular salary.
However, the years spent postponing retirement preparation are also years that could have been used to build savings, contribute to a pension, or gradually acquire income-producing assets.
When retirement eventually becomes urgent, the options may be more limited. A parent who has spent decades directing almost every available resource towards the children may reach the end of active employment without enough independent income to maintain a reasonable standard of living.
The family may then face a difficult transition. The children who were educated and supported may be expected to contribute to their parents’ living expenses, even as they establish their own households, raise children and pursue their financial goals.
There is nothing wrong with children supporting their parents when they can. The problem arises when that support becomes the primary retirement strategy rather than a voluntary expression of family responsibility.
Why parents keep postponing the decision
For some households, the challenge is not poor financial discipline. It is the reality of competing needs. School fees, food, housing, healthcare, transportation and other essential expenses can consume a significant portion of household income. Parents may genuinely have little left to allocate towards long-term goals.
Others assume that retirement planning can begin after the children graduate, secure jobs or become financially independent. Yet education costs can stretch across many years, and completing one child’s education may coincide with another child entering school.
There is also an emotional dimension. Parents can see the immediate benefits of paying school fees, but retirement contributions may not produce an equally visible result today. As a result, the urgent often defeats the important.
Recognising these pressures matters because the solution is not simply to tell parents to save more. It is to encourage them to make deliberate financial decisions based on the resources available to them, rather than waiting for a perfect financial season that may never arrive.
One family, two financial futures
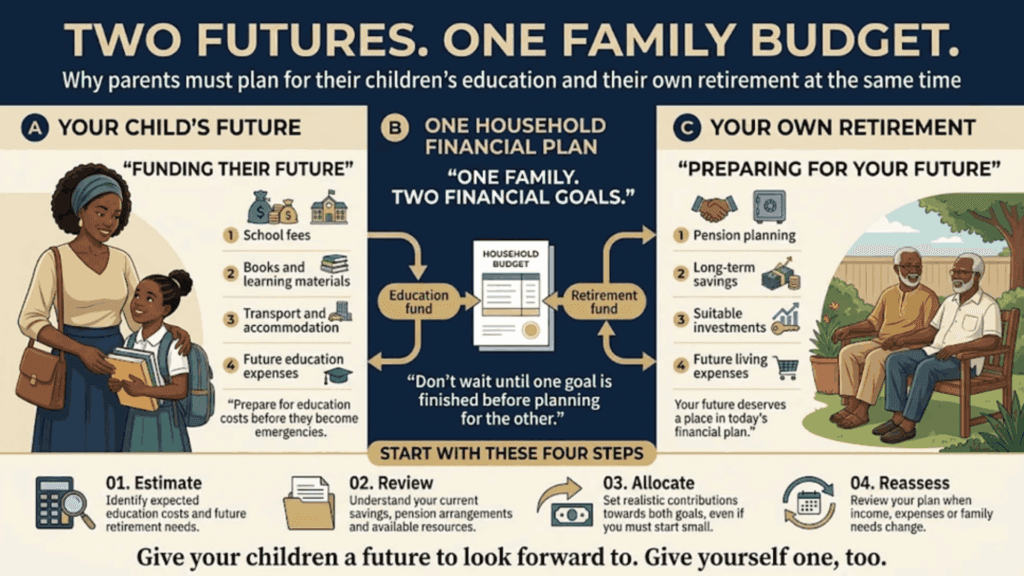
A practical starting point is to treat children’s education and retirement as two distinct financial goals within the same household plan.
First, estimate the likely education expenses ahead. Consider the number of children, their current ages, the stages of education they will enter, and the costs the family expects to bear. School fees are only one part of the picture; books, transportation, accommodation and other related expenses may also require preparation.
Second, assess the retirement resources already in place. For salaried workers, this includes understanding their pension arrangements, reviewing contribution records and learning what benefits may be available. Business owners and self-employed individuals may need to build their own structured retirement savings and investment arrangements. In either case, it is important to understand what resources exist rather than assume they will be sufficient.
Third, create a realistic contribution plan for both goals. The amounts may not be equal, and they may need to change as income and expenses change. A family under severe financial pressure may need to begin with modest contributions, review discretionary spending, increase savings when income improves or adjust the education budget to what is genuinely affordable.
The objective is not to fund every goal perfectly from the beginning. It is to stop treating retirement as a goal that can only be considered after every other responsibility has been completed.
Finally, review the plan regularly. A salary increase, a change in school fees, a new child or a shift in business income may require adjustments. Money set aside for long-term goals should also be matched to suitable financial products and investments, with attention to risk, access to funds, fees and the time when the money will be needed.
A property, for example, may be valuable but difficult to convert quickly into cash. Likewise, an investment intended for a child’s university expenses should not expose that money to a level of risk the family cannot reasonably afford.
Preparing for their future without abandoning yours
Parents naturally want their children to have better opportunities. But a child’s future should not be built on the assumption that a parent’s own financial needs will somehow take care of themselves.
Planning for retirement does not mean loving your children less, and setting aside money for your own later years is not selfish. It is part of creating a more sustainable family financial plan, one that recognises that parents have needs beyond the years of active employment.
The goal is not to choose between a child’s education and a parent’s retirement. It is to recognise both as important financial responsibilities and begin preparing for them with the resources available today.
Give your children the opportunity to build their future without abandoning the responsibility to prepare for yours. A successful education plan should help a child move forward, not leave the parents’ own financial future behind.
Related News

