Ugandan businesses that fail to maintain proper financial records and file tax returns on time risk hefty tax assessments, mounting penalties and cash-flow problems that could undermine their operations and ability to secure contracts, tax practitioners have warned.
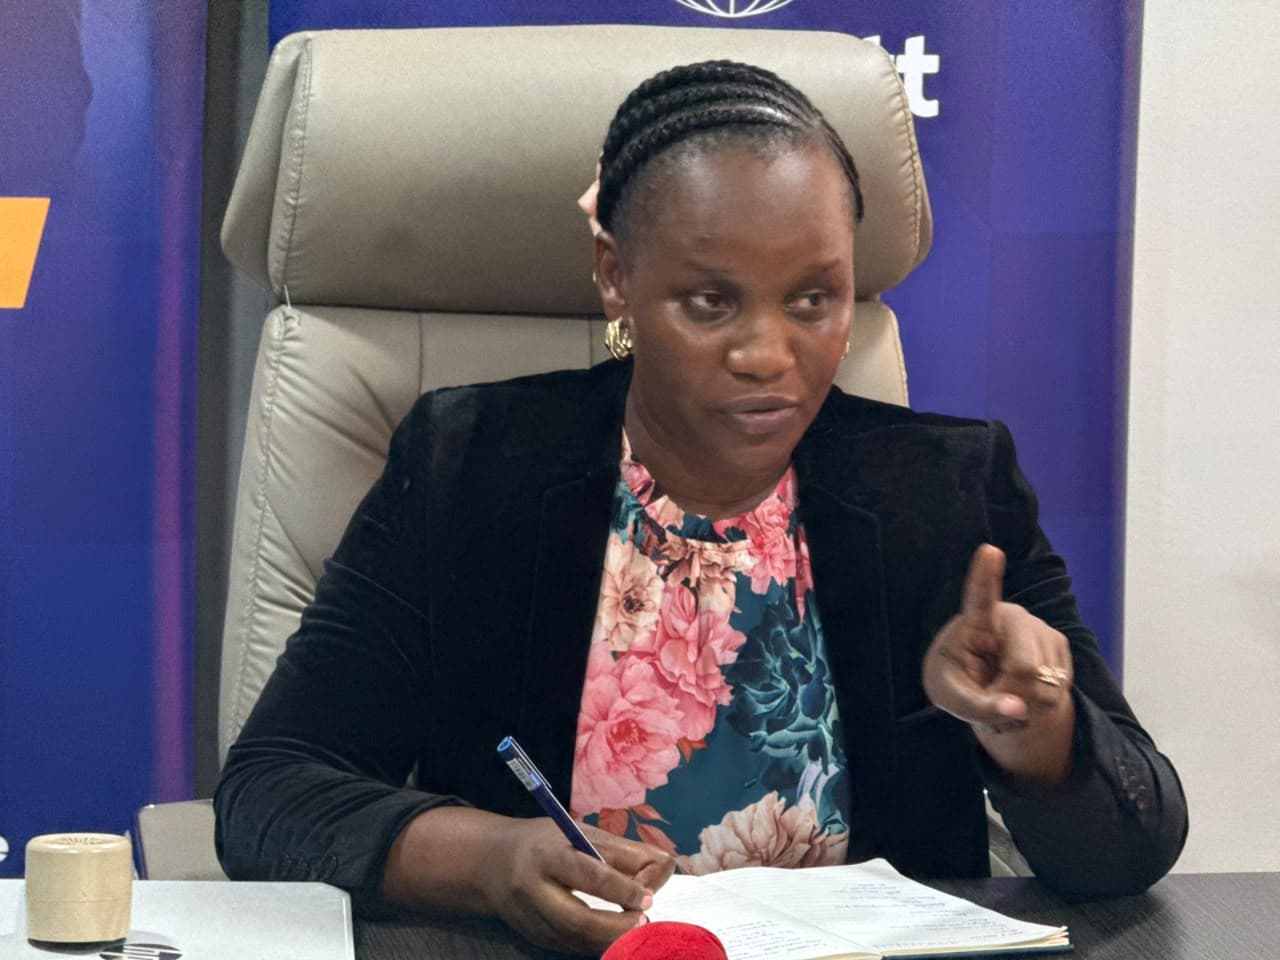
Daisy Namayanjja Sanyu , managing partner at Bennett Advisory, said businesses that cannot adequately document their income and allowable expenses risk paying more tax than necessary because they may struggle to establish their actual taxable profits when assessed by the Uganda Revenue Authority (URA).
Uganda operates a self-assessment tax system under which taxpayers are responsible for declaring their income, expenses and tax liabilities. The system places the responsibility on businesses to maintain accurate financial records to support their tax declarations.
“If you are not organised, if you don’t have proper records, if you have not reported your business, you will be overassessed,” Namayanjja said.
She illustrated the risk using a hypothetical business that earns Shs1 billion but fails to document its operating expenses. Without adequate records to substantiate allowable deductions, the business could struggle to demonstrate its actual taxable profit.
At the standard corporate income tax rate of 30 per cent, treating the entire Shs1 billion as taxable profit would result in a tax liability of Shs300 million. However, the actual amount payable depends on the applicable tax rules, allowable deductions and the specific circumstances of the business.
Namayanjja said proper bookkeeping, including maintaining invoices, payment records and supporting documents for business expenses, is essential to establishing the correct tax liability and challenging assessments that taxpayers believe are inaccurate.
She also warned that businesses could face mounting financial pressure if they neglect their tax obligations for several years and subsequently have to settle outstanding liabilities alongside their current tax payments.
Namayanjja said some businesses interpret multiple demands from URA as evidence of excessive taxation, when the notices may relate to different tax obligations, assessments or stages of debt recovery.
She explained that different departments may handle assessments, objections, routine payments and the recovery of outstanding liabilities, potentially creating confusion among taxpayers unfamiliar with the processes.
Businesses that have failed to meet their obligations for several years may consequently face demands relating to previous tax periods while remaining responsible for their current tax liabilities.
The resulting financial pressure can be significant, particularly for businesses that have not set aside funds to meet their tax obligations.
Namayanjja urged entrepreneurs to understand their tax responsibilities from the time they begin operating rather than waiting until they need tax clearance certificates to pursue business opportunities.
Government institutions, non-governmental organisations and private companies may require suppliers to present tax clearance certificates before awarding contracts or engaging their services.
Businesses that have neglected filing requirements may therefore be forced to regularise their tax affairs when an opportunity arises, potentially facing penalties, additional costs and delays.
“Once you’re compliant, you’re able to bid, and you get the contracts,” she said.
Another tax practitioner identified inadequate taxpayer awareness as a major challenge, arguing that businesses need clearer information about the taxes applicable to their operations and the returns they are required to file.
The practitioner called on URA to strengthen taxpayer education, particularly among businesses operating in the informal sector, to help entrepreneurs understand and meet their obligations.
“There is a huge knowledge gap regarding taxation,” the practitioner said.
The practitioner also encouraged business owners to seek qualified professional advice where necessary, noting that government sensitisation alone may not resolve the challenges of navigating tax requirements.
Namayanjja similarly attributed non-compliance partly to perceptions that professional tax services are expensive and difficulties accessing reliable tax advice.
She said some entrepreneurs mistakenly assume that small businesses are automatically exempt from tax obligations, while others ignore filing requirements until enforcement action begins.
Namayanjja estimated that more than 90 per cent of Ugandan businesses are not fully tax-compliant, although she did not cite a formal study to substantiate the figure.
She distinguished between businesses that fail to comply altogether and those that meet some requirements but neglect others.
The practitioners’ advice centres on maintaining accurate financial records, understanding filing deadlines and seeking qualified assistance before tax problems accumulate.
Namayanjja said a tax clinic scheduled for November 19 at the Sheraton Hotel in Kampala would seek to improve business owners’ understanding of their tax obligations and help them identify potential compliance risks.
The initiative comes amid calls for businesses to strengthen their financial management practices and seek timely guidance to avoid preventable tax disputes and accumulated liabilities.
The broader challenge is to ensure that businesses can access clear, affordable tax guidance while meeting their legal obligations, without allowing avoidable filing errors and mounting liabilities to threaten their financial stability.