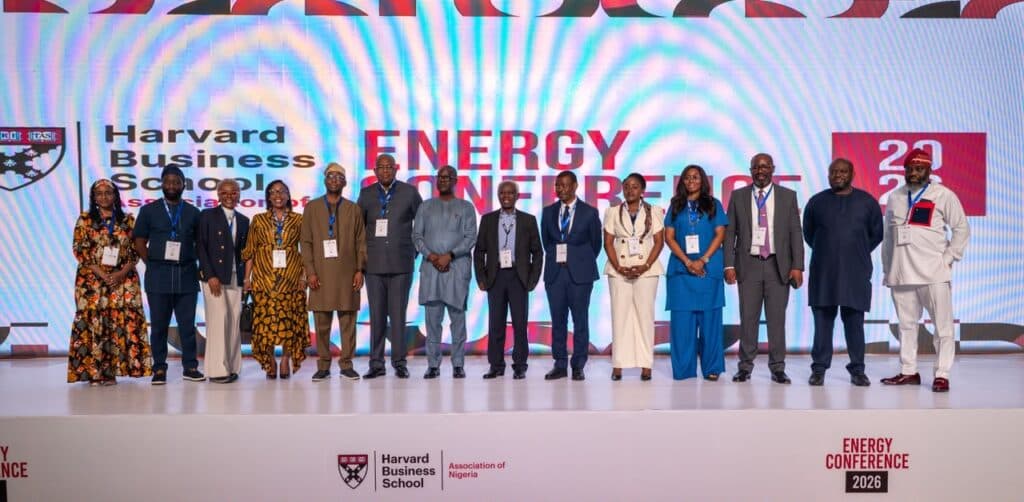
Nigeria needs to attract about $50 billion into its energy infrastructure over the next five years. Getting there depends less on any single reform than on whether government, regulators and investors can coordinate and stay consistent, said Mayowa Afe, chairman of the Harvard Business School Association of Nigeria’s energy conference.
“Capital follows confidence, and confidence follows consistency,” Afe told delegates in closing remarks at the event, which brought together policymakers, financiers, executives and sponsors to discuss the future of Africa’s largest oil producer and its struggling power sector.
The figure framed one of four sessions at the conference, which asked what it would take to make oil, gas and power projects bankable. Afe said speakers pointed to stable fiscal and regulatory frameworks, targeted incentives, innovative financing structures and the mobilization of both domestic and international capital.
Investors, he said, were clear about what they want: bankable projects, credible offtakers, competitive returns, predictable gas pricing, and confidence that they can access foreign exchange and repatriate their returns. Those concerns have long weighed on investment in Nigeria’s energy industry, where currency availability and payment reliability have been recurring sticking points for foreign and local backers alike.
The first session of the day focused on governance and regulatory convergence. Afe said participants made a case for closer alignment among regulators, ministries and market participants, arguing that “policy ambition alone is not enough.” Progress, he said, will require coordinated execution, shared accountability, integrated planning and better collaboration across the oil, gas and power value chains. Speakers stressed commercial viability, sector liquidity, market discipline and long-term policy certainty as the conditions that attract investment and strengthen energy security.
A third session turned to efficiency in the integration of power, oil and gas. Afe said the discussion centered on unlocking more value from Nigeria’s gas resources through better monetization and tighter links along the value chain. Panelists identified commercial and regulatory bottlenecks as obstacles, along with the need to expand infrastructure and make greater use of digital technologies. They also called for closer cooperation among industry, financial institutions and government.
Afe said the session also underlined a people problem. Speakers urged investment in human capital and in developing the next generation of energy professionals who will lead the sector’s growth.
The final session, on building homegrown energy companies in Africa, pushed delegates to think beyond participation in the sector and toward ownership. Afe said it emphasized developing indigenous enterprises that can compete, scale, innovate and create lasting value across the continent.
Corporate governance ran through that discussion. Afe said successful companies need structures built on competence, accountability, discipline and attention to detail, and that enduring businesses are “built deliberately” through sound governance, capable leadership and management teams committed to long-term shareholder value. Speakers also argued that firms hoping to compete globally must recruit and keep talent on merit, capability and performance, and must exercise capital discipline and long-term planning to survive both good periods and bad.
Across the four sessions, Afe said, delegates settled on a common set of priorities: stronger coordination and execution across the energy value chain; more investment in critical infrastructure; better market liquidity and commercial discipline; policy consistency and regulatory certainty; mobilization of domestic and international capital; investment in talent and institutional capacity; strong governance and disciplined leadership; and the development of indigenous companies able to drive Africa’s energy future.
He struck an optimistic note despite the scale of the task. “The challenges facing the energy sector are significant, the opportunities before us are even greater,” Afe said, adding that Nigeria has the resources, talent, entrepreneurial capacity and market potential to become a leading energy hub for Africa. “The task before us is to convert vision into execution and strategy into measurable outcomes.”
The remarks reflect a view widely held among industry participants that Nigeria’s energy problem is as much about execution and institutional credibility as about money. The country is rich in oil and gas, yet its power supply remains unreliable, and bridging that gap has been a stated goal of successive administrations. Afe’s emphasis on integration, with gas monetization linking the oil and power sectors, points to where many in the industry see the largest untapped value.
Afe did not set out a specific funding plan or name the sources of the $50 billion. His address focused instead on the conditions under which capital would arrive and the discipline needed to deploy it. He thanked keynote speakers, panelists, moderators, sponsors, partners and the organizing committee, as well as the participants who attended.
He closed by urging those present to treat the conference as a starting point rather than an endpoint. “The future of Nigeria’s energy sector will be shaped by the actions we take after today,” he said, calling on institutions, sectors and disciplines to work together toward an energy future that is “reliable, inclusive, sustainable, and globally competitive.”
Related News

Dipo Oladehinde is a skilled energy analyst with experience across Nigeria's energy sector alongside relevant know-how about Nigeria’s macro economy. He provides a blend of market intelligence, financial analysis, industry insight, micro and macro-level analysis of a wide range of local and international issues as well as informed technical rudiments for policy-making and private directions.

