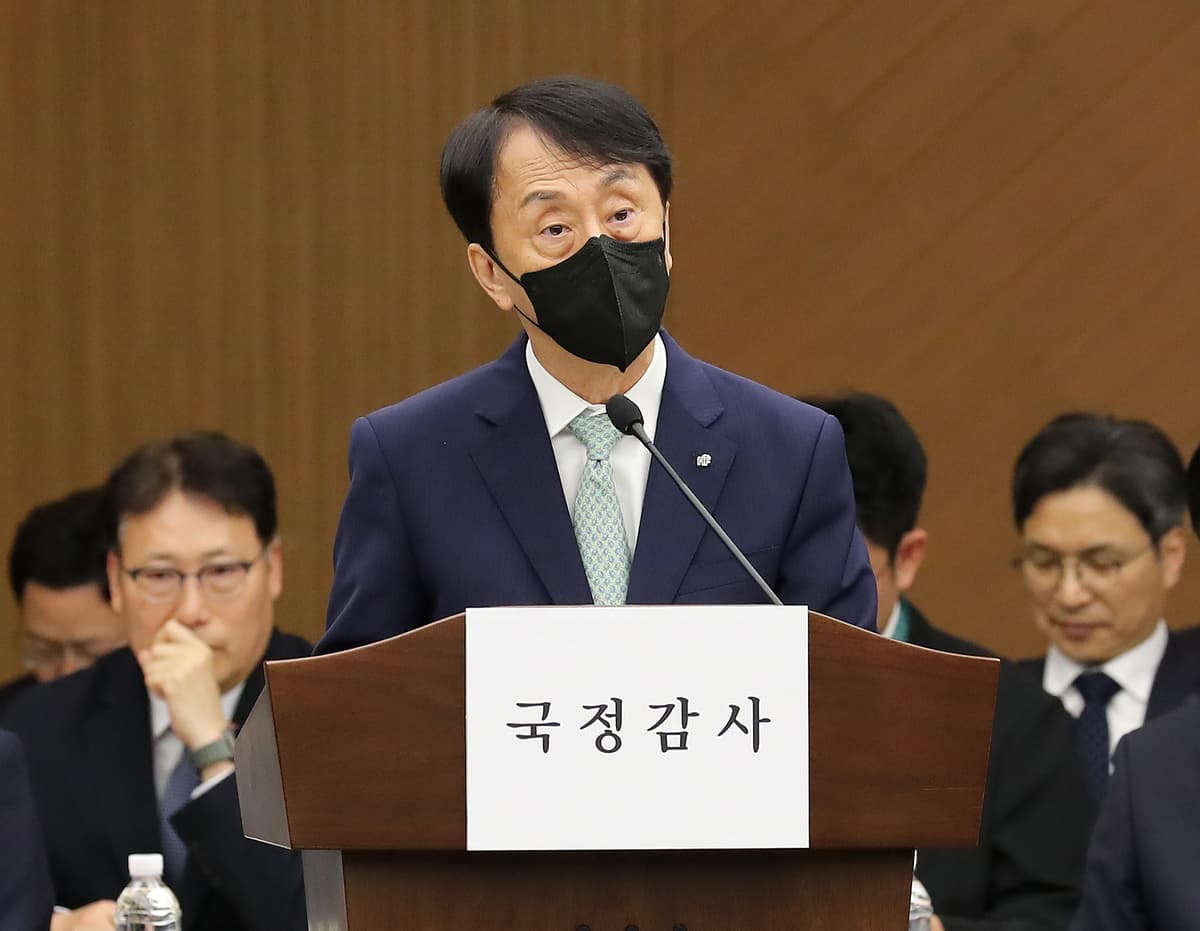
BUSAN — Kim Kyung-hwan, president of the Korea Housing Finance Corporation, said on the 15th that short-term mortgage-backed securities are suitable as reserve assets for stablecoins.
Kim made the remark at a parliamentary audit held by the National Assembly's National Policy Committee at the Busan International Finance Center, responding to a question from Rep. Min Byoung-dug of the Democratic Party of Korea on whether MBS could be used as stablecoin reserve assets. Reserve assets are holdings that back a stablecoin's value and redemption.
"In Korea, MBS is the second-largest asset class after government bonds, and it offers both safety and liquidity," Kim said. Min said he would include MBS in discussions when legislation on stablecoins is taken up.
The Korea Housing Finance Corporation believes including MBS among reserve assets for a won-denominated stablecoin would broaden the demand base. The corporation argues that MBS carries a credit rating and market size comparable to government bonds, and that more active MBS trading would ultimately allow policy mortgages to be offered at lower interest rates.
The ruling party is pushing to consolidate authority over policy and budget planning for the Korea Credit Guarantee Fund, which is currently divided between the Financial Services Commission and the Ministry of SMEs and Startups. "The FSC supervises KODIT's operations while the ministry handles its government budget planning. Even parliamentary review is split between the National Policy Committee and the Trade, Industry, Energy, SMEs and Startups Committee," Rep. Kim Hyun-jung of the Democratic Party said. "Policy finance needs to move quickly, but policy decisions and funding are moving separately." She added that she is preparing a bill to revise the relevant law.
Lawmakers also criticized the Youth Future Bogeumjari Loan, set to launch next year. The product offers low-interest financing to first-time home buyers aged 39 and under for purchases of non-apartment properties such as officetels — studio units used as either a home or an office — priced at 400 million won or less. "Apartments account for 97% of demand for Bogeumjari loans, so will there really be demand for this one?" Rep. Seo Il-jun of the People Power Party said, arguing the program does little to help young people climb the housing ladder. Rep. Choi Eun-seok, also of the People Power Party, pointed to the low resale liquidity of officetels and said: "I am concerned about what the purpose is. Isn't this a housing trap?"
The Korea Asset Management Corporation drew criticism for wasting taxpayer money by selling state-owned land to a private builder below value. According to Rep. Jeon Hyun-heui of the Democratic Party, KAMCO sold state land in Seoul's Guro district appraised at 18.2 billion won to a private company for 9.2 billion won, and the company later sold the same asset to the Korea Land & Housing Corporation for 12.8 billion won. "This is a case of wasting taxpayer money, selling off state assets at a discount, and then having a public institution buy them back at a higher price," Jeon said. KAMCO President Chung Chung-hoon said he was sorry and pledged to tighten the agency's systems.
KAMCO's debtor-in-possession financing program also came under scrutiny. "Refinancing funds within DIP financing support rose to 62.3 billion won last year from 26 billion won in 2023," Rep. Kim Jae-sup of the People Power Party said, noting that the increase outpaced the rise in working capital, which went from 20.3 billion won to 29.8 billion won. "DIP financing is money put into companies that can be saved, and the principle should be working capital," Kim said, calling for changes.