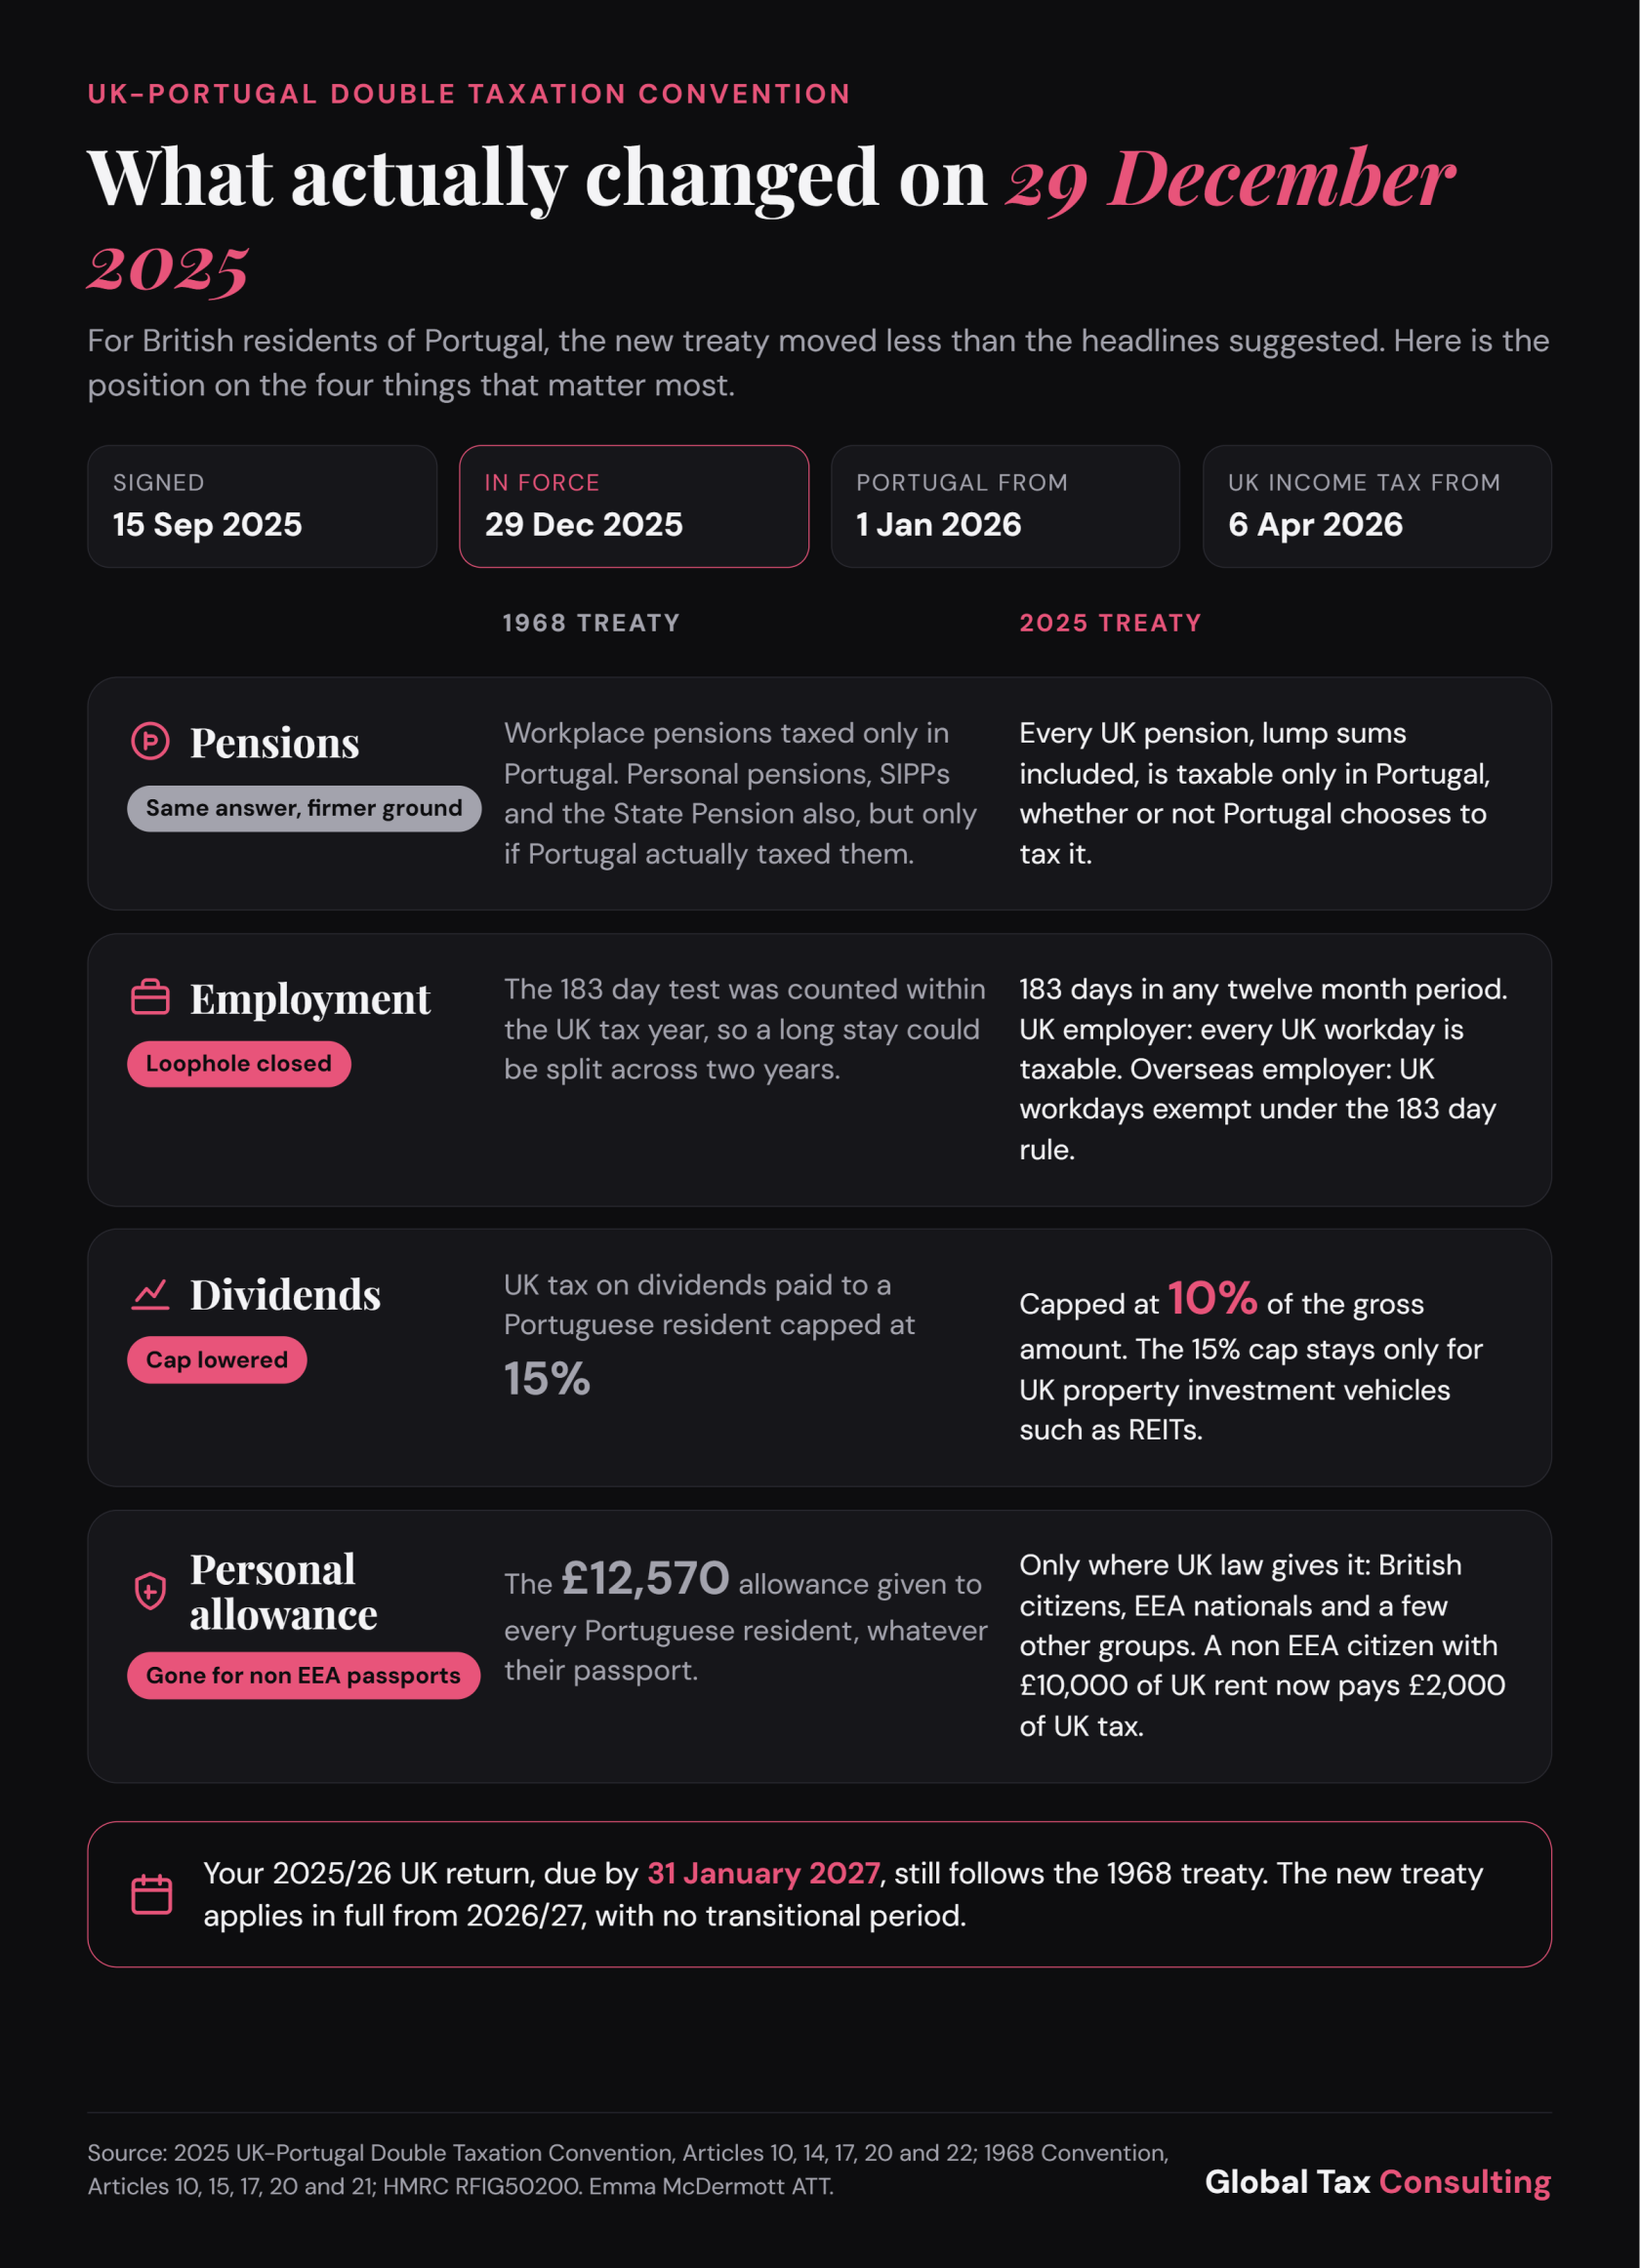
The new double taxation convention between the UK and Portugal entered into force on 29 December 2025, replacing an agreement that had been in place since 1968.
The treaty applies in Portugal from 1 January 2026.
In the UK, it applies to taxes withheld at source from 1 January 2026 and to income tax and capital gains tax from 6 April 2026.When the agreement was signed in September 2025, it attracted considerable attention among British residents in Portugal, particularly those receiving UK pensions, working remotely or retaining income and investments in the UK.However, having compared the two treaties, I would argue that several of the changes are less significant than they initially appear. In many cases, the underlying tax treatment remains broadly unchanged.There is, nevertheless, one particularly important amendment that has received comparatively little attention: the removal of the treaty provision granting the UK personal allowance to Portuguese residents.For some individuals, this could result in a substantial increase in their UK tax liability.Here are four areas where the new agreement makes a difference and what they mean in practice.
1. Pensions: similar tax treatment, but broader protection
Article 17 is the starting point for pension income under the new treaty. It provides that pensions and other similar remuneration paid to a Portuguese resident are taxable exclusively in Portugal, subject to the government service provisions in Article 18.This broadly preserves the position under the 1968 treaty, although the previous wording created complications for certain pension arrangements.Under the old agreement, Article 17 only covered pensions paid in consideration of past employment. Workplace pensions qualified, but personal pensions, including self-invested personal pensions (SIPPs), and the UK state pension could instead fall within Article 20, dealing with other income.Article 20 only provided exclusive taxing rights to Portugal where the recipient was subject to tax in Portugal on the income. Consequently, where Portuguese taxation did not apply, the UK could retain taxing rights.The new Article 17 removes this distinction. It no longer requires pension payments to arise from past employment, providing broader treaty protection for personal pensions.Importantly, the reference to "other similar remuneration" also covers lump sums, and therefore the treaty treats regular pension payments and lump-sum withdrawals in the same way, with Portugal holding the exclusive taxing rights.Whether Portugal actually charges tax on the payment depends on its domestic legislation.
Government service pensions: Article 18
Government service pensions are subject to separate rules under Article 18.The general principle is that pensions paid in respect of qualifying UK government service remain taxable exclusively in the UK.However, where the recipient is resident in Portugal and is a Portuguese national but not also a UK national, both the UK and Portugal may tax the pension. Portugal must then provide relief for UK tax in accordance with the treaty's double taxation provisions, subject to the applicable limitations.This nationality exception broadly preserves the treatment under the 1968 agreement, although the new Article 18 expressly confirms that both countries may exercise taxing rights.What if UK tax is still being deducted?
Where Portugal has exclusive taxing rights, individuals can request relief from UK pension deductions or reclaim tax already paid.One option is to submit HMRC form DT-Individual, supported by certification of Portuguese tax residence, to an NT tax code to receive pension income free of UK taxation.Alternatively, tax can be claimed reclaimed at the end of the tax year through a UK self-assessment return using the SA109 residence pages and HS304.2. Employment: the 183-day test changes
The number of individuals moving to Portugal while continuing to work for UK employers has increased the importance of the treaty's employment provisions.Article 14 provides that employment income earned by a Portuguese tax resident is taxable exclusively in Portugal unless the employment duties are physically performed in the UK.Where an individual is non-resident in the UK, employed by a UK company and performs duties in the UK, the UK can tax the earnings attributable to those workdays.For example, a Portuguese resident who continues to work for a UK company but returns to London for a week of meetings will be liable to UK tax on the earnings attributable to that week.Portugal may also tax the income as the individual's country of residence but must provide relief for UK tax in accordance with the treaty's double taxation provisions.The 183-day exemption: employees of non-UK companies
The position is different where a Portuguese resident performs duties in the UK but is employed by a non-UK company.Under Article 14(2), this employment income can be exempt from UK taxation where all three conditions are satisfied:· The individual spends no more than 183 days in the UK during any 12-month period commencing or ending in the relevant fiscal year;
· The remuneration is paid by, or on behalf of, an employer that is not UK resident;
· The remuneration is not borne by a UK permanent establishment of the employer.
The important change is how the 183 days are calculated.
Under the 1968 treaty, the 183-day limit was measured by reference to the UK tax year, ending on 5 April.
This allowed individuals to spread their visits across two UK tax years without necessarily exceeding the threshold in either year.
The new treaty replaces this with a rolling 12-month test, covering any relevant 12-month period commencing or ending in the fiscal year concerned.
Consequently, individuals can no longer rely on the UK tax year ending on 5 April to reset their 183-day limit.
For Portuguese residents employed by non-UK companies who regularly visit the UK for work, maintaining an accurate record of their days in the country is therefore important.
What if UK PAYE is still being deducted?
For Portuguese residents continuing to work remotely for UK employers, UK PAYE may still be deducted from their salary even where some or all of their earnings are not subject to UK tax.
There are two main options for addressing this.
Option one: apply for an NT tax code. Individuals leaving the UK to work abroad can submit form P85 and request an NT tax code from HMRC. Once approved, this will allow their employer to pay salary without deducting UK income tax.
Option two: reclaim the tax through self-assessment. Where UK PAYE has already been deducted, individuals can file a UK tax return to reclaim tax paid on earnings attributable to overseas employment duties that are not subject to UK taxation.
3. Dividends: the withholding tax ceiling falls from 15% to 10%
Article 10 reduces the maximum tax that the UK can charge on ordinary dividends paid to Portuguese residents from 15% under the 1968 treaty to 10% under the new agreement.
An exception applies to certain distributions from property investment vehicles, including qualifying Real Estate Investment Trusts (REITs), where the maximum remains 15%.
In practice, however, most Portuguese residents receiving ordinary UK dividends will see little difference.
This is because UK domestic law is often more favourable than the treaty.
The UK does not withhold tax at source on dividends. Furthermore, under the UK's disregarded income rules, the UK tax liability of full-year non-residents on certain investment income, including UK dividends, can be limited to the tax deducted at source.
As no tax is withheld on UK dividends, the resulting UK tax liability on those dividends can therefore be nil.
The disregarded income calculation does not allow personal allowances to be deducted against other UK income, so HMRC compares this calculation with the normal tax computation and applies the lower liability.
Consequently, for many Portuguese residents holding ordinary UK shares, UK domestic legislation already provides a more favourable outcome than the treaty's 10% ceiling.
Further information is available in HMRC's helpsheet HS300.
4. The UK personal allowance: the most overlooked change
Of all the amendments introduced by the new treaty, this is arguably the most important for certain Portuguese residents who continue to receive UK income.
Article 21 of the 1968 convention entitled individuals resident in Portugal to the same UK personal allowances as British subjects living abroad, subject to certain restrictions.
Crucially, the entitlement was not limited to British or Portuguese nationals.
For example, an American, Indian or South African national living in Portugal could potentially claim the UK personal allowance against taxable UK rental profits, despite being neither British nor an EEA national.
The 2025 treaty removes this entitlement.
The new agreement contains no equivalent to the former Article 21.
Instead, Article 22(5) confirms that neither country is required to grant its personal allowances to individuals who are not resident there.
From 6 April 2026, Portuguese residents must therefore establish their entitlement to the UK personal allowance under UK domestic legislation or another applicable legal provision, rather than relying solely on residence in Portugal.
HMRC explains the domestic eligibility rules in its Residence and FIG Regime Manual at RFIG50200.
The qualifying categories include British citizens, nationals of EEA countries and certain other individuals who satisfy specific statutory conditions.
Portuguese nationals remain eligible because Portugal is an EEA member state. Similarly, British nationals living in Portugal retain their entitlement.
However, individuals who are neither British nor EEA nationals, and who do not qualify under another exception, will now lose an allowance that was previously available to them.
What does this mean financially?
Consider an American national who is resident in Portugal and receives £10,000 of net annual rental profits from a UK property.
Assume the individual has no other UK income, deductions or reliefs and would otherwise be taxable at the UK basic rate of 20%.
Under the previous treaty, the individual could claim the UK personal allowance of £12,570.
The result would have been no UK Income Tax liability on those rental profits.
Under the new treaty, if the individual has no separate entitlement to the personal allowance, the position changes:
| 2025/26 | 2026/27 | |
| UK rental profit | £10,000 | £10,000 |
| Available personal allowance | £12,570 | £0 |
| UK Income Tax | £0 | £2,000 |
The result is an additional £2,000 of UK tax annually, despite no change in rental income.
Portugal may provide a foreign tax credit for UK tax properly charged on the same income, subject to Portuguese domestic rules.
However, that credit is limited to the Portuguese tax attributable to the relevant income. It does not mean that Portugal will automatically refund the full amount of additional UK tax.
For affected individuals, the removal of the allowance therefore represents a potentially significant additional tax cost.
What Portuguese residents should check nowThe new convention has already taken effect, but its different commencement dates remain important.
For UK income tax, the new treaty applies from the 2026/27 tax year, beginning on 6 April 2026.
The earlier treaty remains relevant to the 2025/26 UK tax year, although the new provisions relating to taxes withheld at source took effect on 1 January 2026.
The normal online self-assessment filing deadline for 2025/26 is 31 January 2027.
For Portuguese residents with ongoing UK financial interests, I recommend
reviewing three areas in particular.
First, individuals receiving UK pensions should confirm whether the correct treaty treatment has been applied and whether any UK tax deductions are recoverable.
Second, those continuing to work for UK employers should review their UK workdays, residence position and payroll arrangements to ensure tax is not being deducted unnecessarily.
Finally, Portuguese residents receiving UK rental income should confirm their entitlement to the UK personal allowance, particularly where they are neither British nor EEA nationals.
The new treaty does not fundamentally change every aspect of the UK-Portugal tax relationship. For many residents, the practical outcome remains largely the same.
However, as the personal allowance provisions demonstrate, even a relatively small change in treaty wording can have substantial financial consequences.Understanding where the rules have genuinely changed, rather than assuming every revised article creates a new tax liability, is essential to managing a cross-border tax position effectively.
Emma McDermott, ATT, is the founder of Global Tax Consulting, a UK tax firm for expats and digital nomads. She advises clients living in Portugal on non-resident tax rules and cross-border tax obligations. Further information is available in her leaving the UK tax guide and leaving the UK calculator.
Disclaimer:
The views expressed on this page are those of the author and not of The Portugal News.