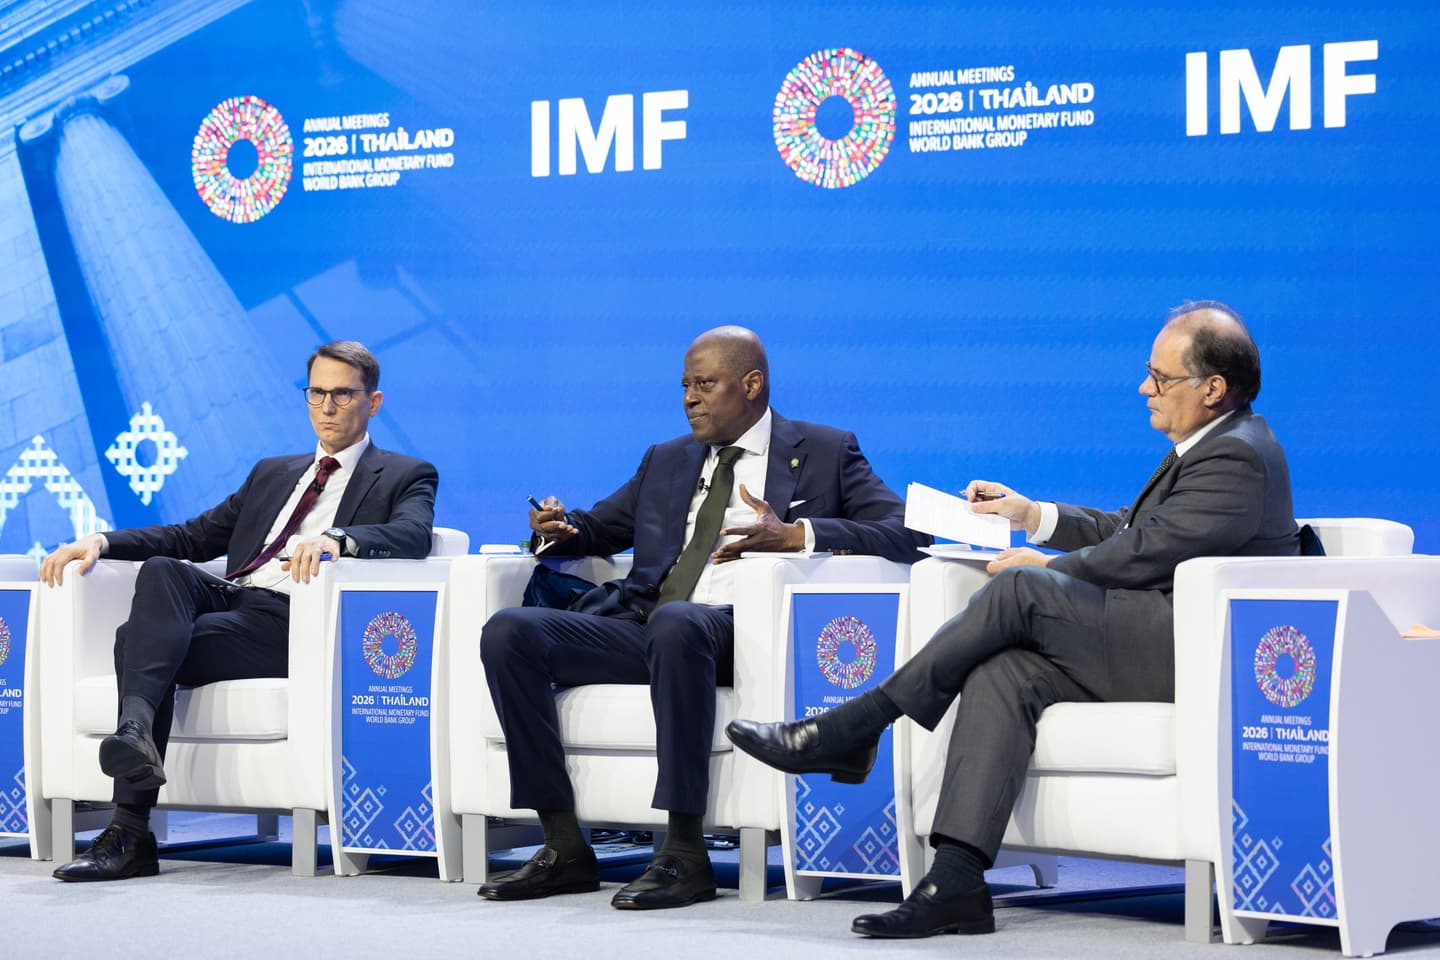
Governor of the Central Bank of Nigeria (CBN), Olayemi Cardoso, has emphasised that credible monetary policy depends on informed committee deliberations, independent perspectives and clear communication of decisions to financial markets and the public.
Speaking at an International Monetary Fund (IMF) seminar in Bangkok on Thursday, Cardoso explained how the CBN has strengthened these practices within its Monetary Policy Committee (MPC), drawing on Nigeria’s experience of navigating complex economic reforms and restoring confidence in monetary policymaking.
The seminar, ‘How Central Banks Decide: Committee Decision-Making and Communication in an Era of Uncertainty,’ brought together Cardoso; Chairman of the Swiss National Bank’s Governing Board, Martin Schlegel; and Governor of the Banque de France and member of the European Central Bank’s Governing Council, Emmanuel Moulin. The discussion was moderated by IMF First Deputy Managing Director, Dan Katz.
Addressing the role of committee members in reaching credible decisions, Cardoso explained that the CBN provides external MPC members with dedicated technical support and opportunities to consult independent specialists.
The bank also organises retreats involving experts from other central banks and wider stakeholder engagements, allowing members to consider diverse economic perspectives beyond formal policy meetings.
These arrangements extend to Nigeria’s ongoing transition towards inflation targeting, supported by IMF technical assistance, with external members involved from the outset of the process.
Cardoso said the arrangements were particularly important in establishing the credibility of the MPC following the economic and institutional challenges confronting the CBN when the current leadership assumed office.
He also highlighted the bank’s practice of publishing individual MPC members’ policy statements, which provides greater transparency around the reasoning behind monetary policy decisions.
According to Cardoso, he personally reviews the statements to understand the different assessments informing committee deliberations, including opinions that may differ from the eventual decision.
On the role of leadership, he explained that effective deliberation requires identifying areas of agreement before addressing disagreements and proceeding to a vote.
“What are the things we all agree on? That should be number one. What are the things we don’t really agree on? And then number three, of course, is to vote,” he said.
Cardoso noted that this approach helps prevent committees from becoming absorbed in relatively minor disagreements while losing sight of the broader economic questions requiring decisions.
His remarks reflected a central theme of the IMF discussion: how central banks can encourage rigorous internal debate while maintaining a coherent institutional position.
Schlegel described the Swiss National Bank’s approach, where governing board members examine the merits and disadvantages of competing policy options before reaching consensus. The institution communicates a common position without attributing individual votes, a practice he said also helps protect members from external pressure.
Moulin discussed the European Central Bank’s consensus-building culture under President Christine Lagarde, highlighting inclusive deliberations, equal access to information and a shared monetary policy framework. He stressed that communication must help households understand the implications of policy decisions for prices, employment and borrowing costs.
Cardoso illustrated the application of Nigeria’s approach through the September MPC meeting, when members agreed that weaknesses in the monetary policy transmission mechanism required correction.
That common assessment helped focus deliberations on the appropriate response, resulting in a 350-basis-point reduction in the benchmark interest rate from 26.5 per cent to 23 per cent.
He explained that Nigeria’s distinct inflation cycle, influenced by foreign-exchange harmonisation and subsidy reforms, required the committee to assess domestic economic conditions rather than simply follow monetary policy developments in other countries.
Although the decision surprised markets, Cardoso said earlier reforms, stronger economic fundamentals and carefully considered communication helped investors understand its rationale.
“To do such a thing successfully, you must have an element of credibility with the market,” he said.
Katz observed that financial markets absorbed the unexpected decision without significant disruption, describing the response as a testament to the clarity and credibility of the CBN’s communications.
The discussion also examined the growing role of artificial intelligence in interpreting central bank statements. Schlegel emphasised the importance of precise language, while Katz disclosed that the IMF had developed AI tools to analyse monetary policy communications in near real time.
In closing, Katz noted that although central banks operate under different governance arrangements, effective decision-making depends on candid debate, diverse perspectives, strong leadership and clear communication.
Cardoso’s contribution offered Nigeria’s experience of combining independent participation, transparent policy assessments and structured committee deliberations with the responsibility to communicate collective decisions clearly.
The exchange highlighted how the credibility of monetary policy is shaped not only by the decisions central banks announce, but also by the institutional processes through which those decisions are reached.