
It’s not quite mission accomplished, but South Africa is safely back from the edge of a fiscal cliff and the dividends include fuel levy relief for hard-pressed consumers and a R10-billion kitty to deal with any droughts and disasters that El Niño may bring.
Finance Minister Enoch Godongwana announced the cut in the fuel levy in his annual Medium-Term Budget Policy Statement (MTBPS) to Parliament – and the 2026 edition is the most promising and plausible in years, and should translate into further ratings upgrades.
“Because we have rebuilt fiscal buffers, government is in a stronger position to respond, including by providing temporary fuel levy relief again,” Godongwana said in his speech on Wednesday, 21 October.
“We are aware of the pressure that rising fuel prices are placing on households and businesses. To provide temporary relief, the fuel levy will be reduced by R3 per litre for diesel and R1.50 per litre for petrol from 4 November 2026 up until 1 December 2026.”
This move has been enabled by a favourable combination of rising revenues and falling debt – the precise trajectory that South Africa needs to maintain to dig itself out of the deep fiscal pothole that was dug during the lost Zuma years.
Treasure underground
Speaking of digging, the mining sector played a starring role in delivering a fiscal boost from higher precious metals prices. The projection for gross tax revenue for this year has been revised upwards by R17.1-billion compared with the February estimate.
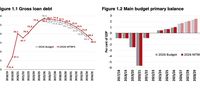
“For the first time in nearly two decades, our debt-to-GDP stabilised, at 78.4% of GDP in 2025/26,” Godongwana said.
From this peak it is projected to descend to 76.6% by 2030 and to 66.6% by 2035.
“The budget deficit is also better than we expected in February. It will now narrow to 4.3% of GDP this year compared to the 4.5% forecast at the time of the Budget. By 2030, we see the deficit falling to 2.5% of GDP.”
This is a big deal: debt stabilisation has been the elusive Holy Grail long pursued by the Treasury, and is the metric that the markets and credit ratings watch like a hawk.
It all adds up to additional funds being made available to save some cash for a rainy day – or in this case, the expected scorching droughts from the unfolding El Niño that is widely regarded as the strongest on record.
“In an environment of elevated uncertainty, government is increasing the contingency reserve to R10-billion in 2026/27 for drought and El Niño response, and potential responses to additional energy price spikes,” the MTBPS statement said.
Digging the DG
Thoughtful Treasury Director-General Duncan Pieterse told Daily Maverick in a brief interview that fiscal space had opened up to allow for such measures to respond to challenges such as elevated fuel prices or drought.
“The fuel levy relief for us is an appropriate thing to do given where prices are, provided they can be funded without deviating from our fiscal targets,” he said.
“When we have additional revenue that is coming in relative to our estimates, when expenditure is lower than we thought relative to our estimates, that frees up revenue, it frees up space... It’s the benefit of meeting your fiscal targets, and the benefit of improving fiscal credibility is that your borrowing costs are lower and there is more confidence in your economy.”
And as long as fuel prices remain high – at the moment largely a consequence of US President Donald Trump’s ill-conceived war of choice against Iran – such relief will remain on the cards, the director-general said.
“If we don’t have additional revenue, then fuel levy relief becomes very difficult... because by implication it will force you to deviate from your fiscal plan,” he pointedly noted.
He went on to say that the Treasury was confident that these improvements would be noted by the ratings agencies as South Africa strove to regain its coveted investment grade rating. Fitch and Moody’s will both update their ratings reviews on South Africa before the end of this year.
“If you look at where bond yields are trending at the moment, they are quite well aligned to some of our emerging market peers that are investment grade. If you take the example of Mexico, which is an investment-grade jurisdiction, our 10-year bond yield at the moment is around where theirs is, and even slightly lower.”
Anchors away
This momentum will be maintained by a fiscal anchor, which the finance ministry wants to embed in legislation.
It will not be a rigid numerical rule such as capping the debt-to-GDP ratio at, say, 70% of GDP.
Rather, Godongwana said in his speech that: “It requires each administration to commit to its own fiscal objectives, consistent with the electoral mandate. It then reports against it at every Budget and explain any material deviation to Parliament.”
One dark cloud hanging over the fiscal outlook remains the slow pace of economic growth. The forecast for South Africa's growth for 2026 has been cut to 1.2% from the 1.6% projected in the February Budget Speech.
“Growth is expected to reach 1.6% in 2027, and 2% by 2029... But growth remains too low,” Godongwana said. “For this reason, government is focused on accelerating implementation of structural reforms coupled with strengthening state capability and delivering public infrastructure. This will put the economy on a faster, more sustainable growth trajectory.”
In the past, such a statement would have been taken with a massive dose of salt. But credibility on the debt front has finally been restored, and that provides confidence that a path to higher rates of economic growth can finally be blazed. DM