
China Decoded is Newsweek’s in-depth newsletter about China’s growing influence on the world. It goes beyond the headlines to examine how Beijing thinks, how its policies travel beyond China’s borders, and what they mean for the United States and its allies. Readers can sign up for China Decoded here to receive each edition directly in their inbox.
The newsletter is written by journalists with deep experience covering China. Didi Kirsten Tatlow, Senior Correspondent for International Affairs and Investigations, has reported extensively on Chinese politics, influence and security. John Feng, China Editor, is based in Taiwan and covers China’s domestic politics, foreign policy and the strategic competition between Beijing and Washington.
Below, for Newsweek Members, we are reproducing the latest edition of China Decoded in full:
Printing the Future
It’s a familiar playbook: Communist Party economic planners identify an exciting new technology and acquire it “by multiple means,” as their phrase goes. They boost it with subsidies and other forms of industrial support that far outstrip others’; the technology is integrated into state development plans and the country’s military-civil fusion system; even cyberespionage capacities are deployed to secure advantage and create global dependency as manufacturing expands.
That’s what’s happening with 3D printing, or additive manufacturing, as it’s more accurately known. AM refers to production processes that create physical objects from digital models by adding material layer by layer. It will, literally, print the future.
The technology is fast and flexible, making it particularly valuable in time-sensitive or supply-constrained environments including defense, disaster response, and other crisis conditions, according to a revelatory and thorough new study, Blueprinting the Future: Mitigating the Risks of Chinese Hegemony in Additive Manufacturing, by David Gardáš, Michal Thim and Filip Urban, and published by the Czech think tank Sinopsis.
“China’s growing dominance in 3D printing is turning a manufacturing revolution into a question of economic and national security,” the authors warn.
China has a playbook for industrial areas where it wants to dominate, and it does it well. Policy is clear, people work hard, they work fast, the product is well-priced and good. But little is left to chance. Control is king.
That raises a question: is it fair? And is dependency in this area what the rest of the world wants?
Perhaps fairness has nothing to do with it. Perhaps that’s sour grapes.
Perhaps the question should be, what should other countries do about it, and why aren’t they doing much, if they don’t like it?
It’s important to know that China spent 4.4 percent of its GDP on supporting its industrial policies in 2023, including in the form of cash subsidies, tax benefits, subsidized land, and preferential credit, as the authors point out, citing IMF figures. That’s extraordinarily high—three times more than any other economy.
So there is a fairness question in there—at least if you are interested in free and balanced trade. Then there’s AM’s close inclusion in a mature, integrated military-civil fusion system that merges military and non-military knowledge and manufacturing.
Today, AM is classified as a strategic industry in China following about three decades of incorporation into its industrial policy via a chain of policies, plans and documents at the national and provincial level, the authors write. Production in China is surging. Uptake is surging globally too.
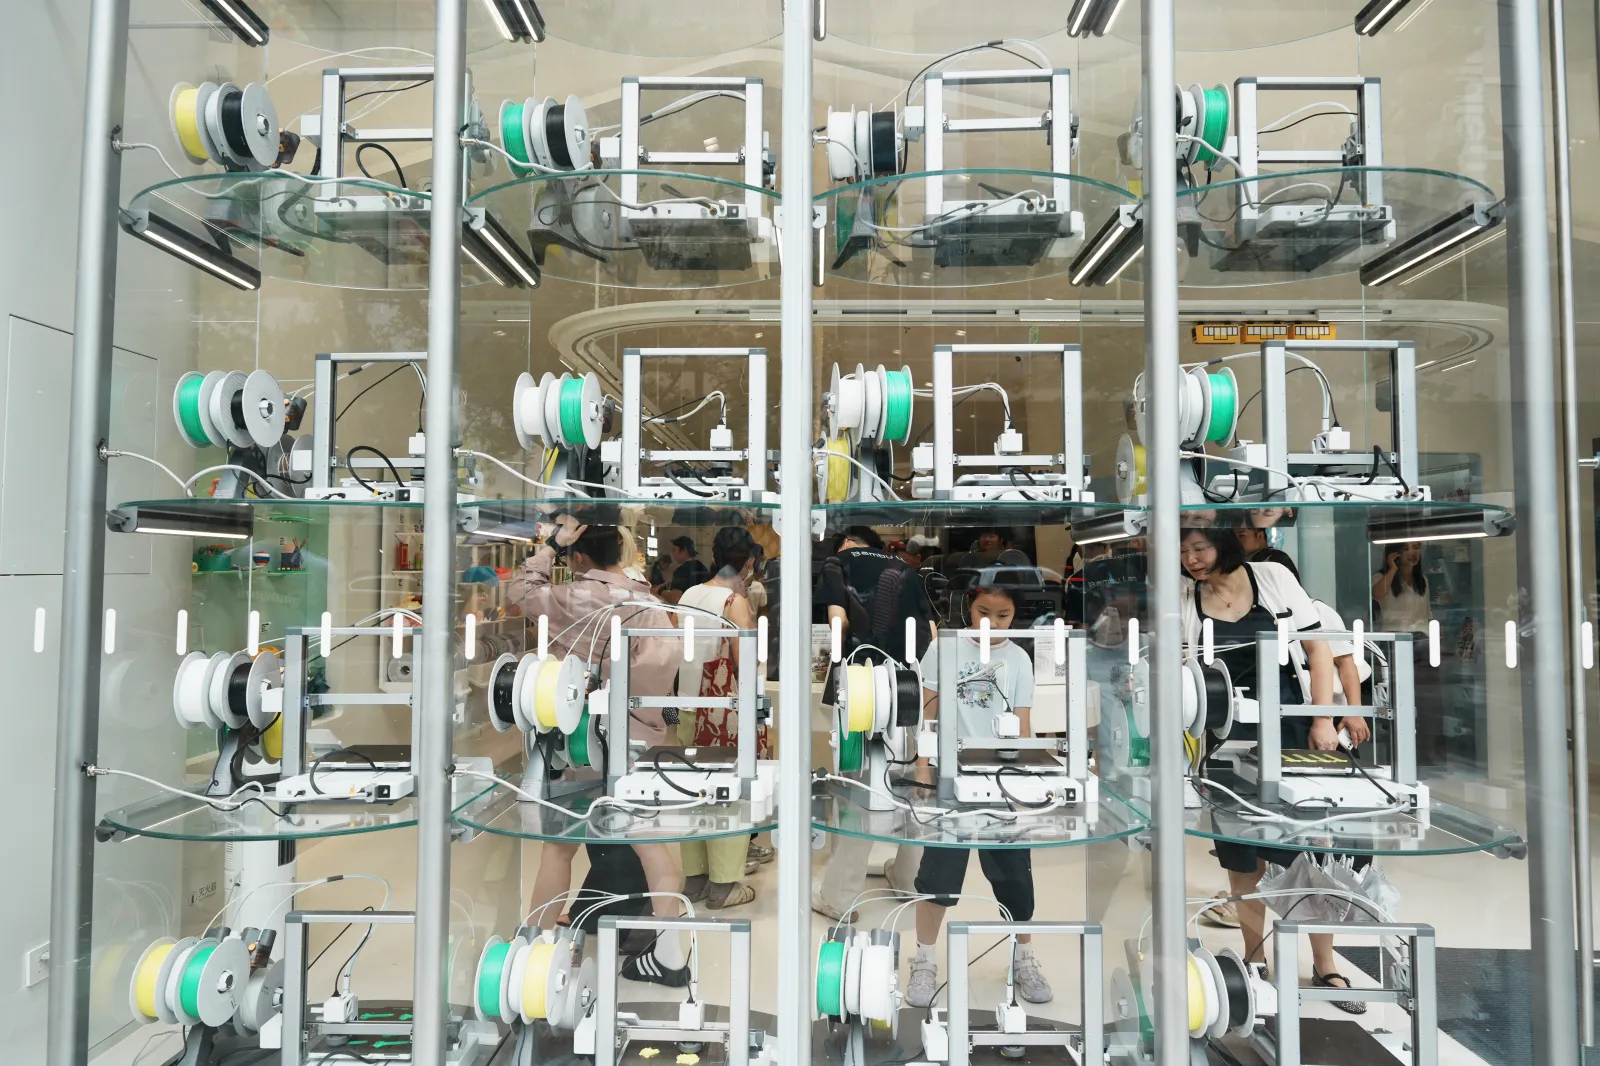
“Against this policy backdrop, China’s AM industry now spans desktop 3D printers as well as industrial systems for high-performance metal and polymer components,” the authors write, pointing to leading companies such as Bambu Lab, Xi’an Bright Laser Technologies and Farsoon Technologies, and to Norinco Group, the giant defense conglomerate which operates its own Additive Manufacturing Technology Research and Application Center.
Customers watch the additive manufacturing process at the Bambu Lab flagship store on August 24, 2026 in Hangzhou, Zhejiang province:
...
The defense use is clear: The war in Ukraine has demonstrated AM’s value in rapid production, particularly of drones and related components. Bambu Lab printers have reportedly been used in Ukraine and by the British army.
The authors say it’s not just the technology; a “soup to nuts” situation, or a beginning-to-end ecosystem, is being built for long-term dominance. And as this happens the risks for the rest of the world, “related to intellectual property loss, technology transfer, and the security of sensitive data are becoming more consequential,” they write.
Chinese AM companies benefit from broader non-market measures favoring localization, scale, and domestic substitution, and—subsidies again—receive disproportionately high levels of state support relative to competitors in OECD economies, they write.
“The result is a significant distortion of competition, enabling rapid expansion abroad while foreign firms face more constrained access to the Chinese market.” Overall, new Western AM market entrants find it increasingly difficult to gain a foothold, secure venture funding, or compete, they write.
“Taken together, these trends make China’s AM ecosystem a strategic concern not only for industrial competitiveness, but also for supply-chain resilience, technology and innovation security, intellectual-property protection, and Western national security,” they write.
What to do? The authors have seven recommendations. Here are three core ones, summarized. They boil down to: protect your technology, work with friendly nations, and do better yourself:
- Classify additive manufacturing systems as sensitive technology; Apply targeted export controls and procurement safeguards;
- Coordinate technology-security measures with allies…to reduce the risk that controls in one jurisdiction simply redirect acquisition activity to another;
- Invest in competitive open innovation ecosystems; Support domestic and allied R&D, technical education, and workforce expertise in industrial software, materials, secure digital workflows…to reduce strategic dependence and preserve critical AM know-how.
Didi Kirsten Tatlow is Senior Correspondent, International Affairs/Investigations at Newsweek. She is based in Berlin, Germany. You can get in touch by email here.
The Data Story
China is growing into a superpower like no other. Its importance to the world, or rather the world’s dependence on it, was created by design through a heavily subsidized manufacturing sector, and global economies are finding it hard to wean themselves off.
The Chinese government in January valued the country’s additive manufacturing industry at 70 billion Chinese yuan, or just under $10.5 billion. Its top 3D printing companies, like those referenced by Kirsten above, shipped nearly 40 percent of all AM devices sold last year and around 90 percent of those in the consumer sector.
“Additive” is a technical category in engineering that differs from “subtractive” like milling or “formative” like injection molding. 3D printing began in the 1980s as a way to make rapid prototypes out of polymer, but manufacturing today has shifted toward much higher-grade materials for uses in the aerospace, defense and medical industries, among others.
China’s AM industry leads by output but remains a distant second to the United States in terms of value. That’s a familiar story we see repeated in industries like AI, but that’s not to say Beijing’s economic planners aren’t planning to take pole position one day.
China has its sights set on winning all aspects of the next industrial revolution, and there’s no industry too small to dominate (not that 3D printing is small).
A June report published by the consultancy Grand View Research valued the global AM market at $30.6 billion in 2025. North America’s revenue share was the largest at 32.8 percent, but the Asia-Pacific market grew the fastest. The total value of the industry is projected to grow by more than five times by 2033, to $168.9 billion.
Industry researchers at the firm CONTEXT analyze 3D printing equipment by four price categories:
- Entry-level: up to $2,500;
- Professional: up to $20,000;
- Midrange: up to $100,000;
- Industrial over $100,000.
The real money is in the final tier—for medical devices like implants and aerospace components like engine parts—and that explains America’s continued dominance of the value chain.
U.S.-Israeli firm Stratasys is the company with the largest market revenue share at 11.5 percent, while Germany’s EOS is second at 7.8 percent. Three other American firms together make up the top five.
So, China is shipping most of the world’s desktop machines, which print mostly with plastic, but Western first movers in the industrial sector are making most of the money—over 70 percent of all hardware revenue.
Rest assured—China will soon be competing in the highest-value sectors too with its mature manufacturing playbook.
John Feng is Newsweek's China Editor based in Taichung, Taiwan. You can get in touch with John by email here.