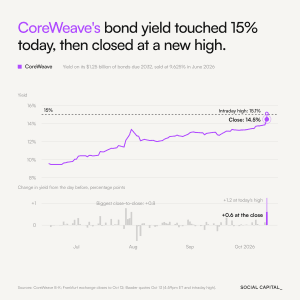
CoreWeave, a cloud computing company operating 51 data centers, had a brutal day on the stock and credit markets yesterday, and may indicate troubles coming for the broader AI industry.
The trouble started when yields on their corporate debt spiked dramatically.
Venture capitalist Chamath Palihapitiya tweeted the following to his 2.4M followers:
It didn’t help when Elon Musk replied, “Yikes.”
Accompanied by an essay titled “Deep Dive: Is the AI buildout creating a private credit bubble?”
The AI buildout is increasingly funded by debt, and private credit is playing a much bigger role than it did even a year ago.
In the second quarter of 2026, Apollo and Blackstone led a $35 billion vehicle to buy chips and lease them to Anthropic. UBS called it the largest private credit deal on record. For comparison, direct lenders made about $23 billion of loans to private-equity-backed U.S. companies that quarter. One AI financing was larger than all the traditional PE-backed direct lending PitchBook counted during the same period.
…
The structure of some AI financings adds another layer to the picture. CoreWeave borrowed for five years against customer contracts averaging about three, while Meta’s Hyperion bonds run to 2049 against leases renewed every four years.The market is also already distinguishing among these deals. Apollo bought debt financing chips leased to xAI at 99 cents in December 2025, and after SpaceX bought xAI, it traded as high as 106. Project Jupiter, an $18 billion AI data-center financing, later traded at 89 to 91 cents as investors reassessed the project’s credit.
So rather than ask whether AI itself is a bubble, our team at Social Capital looked beneath the surface at a different question. Is private credit, which is funding a growing portion of the AI buildout, a bubble?
Interested readers will need to check out the full report to find out Palihapitiya’s conclusion, but what I can tell you is that the impact on CoreWeave’s stock price was immediate and dramatic:

Yahoo! Finance added that CoreWeave’s debt has tripled in a year:

Twitter market analyst Hedgie posted the following graph:

CoreWeave stock fell about 13% Wednesday after its bonds due in 2032 traded at a record 14.5% yield. CoreWeave sold those bonds in June at 9.625%, so in four months the cost of lending to it without collateral jumped about five points. Venture capitalist Chamath Palihapitiya posted the yield chart as a warning about a private credit bubble around AI.
I’ve been saying that the AI bubble lives in the debt more than the demand, and CoreWeave is an example. It raised more than $35 billion this year, carries about $52 billion in debt and leases, and paid $640 million in net interest last quarter, roughly a quarter of its revenue. The $104 billion backlog sounds great, but a backlog doesn’t cover interest until the data centers get built and the customers pay.
Palihapitiya’s numbers show private lenders charge AI borrowers almost the same spread as everyone else, 6.2 points versus 6.1. I think the bond market just repriced that risk for them. My guess is CoreWeave’s next raise costs more, comes backed by chips, or dilutes shareholders, and Nebius and the other AI cloud companies face the same questions. If you own a private credit fund, find out how much AI and software debt it holds, because those loans don’t get repriced every day the way CoreWeave’s bonds do.
A Bit More About CoreWeave
This Wired profile from 2024 tells CoreWeave’s story the way they like it told.
After starting out as a bunch of bros who pooled their fantasy football money to buy GPUs to do some cryptomining as a joke but then took it seriously when prices soared in 2016, they had to pivot when crypto prices crashed:
When crypto prices cratered heading into 2019, Venturo and team pivoted. They raised money to buy cut-price GPUs from struggling crypto miners, rebranded as CoreWeave, and offered up their tens of thousands GPUs as a specialist cloud service for companies in need of the powerful chips, like visual effects studios and AI startups. GPUs are essential to machine learning projects like training algorithms to process images or text. CoreWeave was unknown in those spheres, but won over clients by dropping everything to address support queries. “We would resolve things in 15 minutes,” a manager from that era says. “The dedication to customers was phenomenal.”
Everything changed after OpenAI debuted ChatGPT late in 2022. A rush of interest and investment in all things generative AI caused a GPU shortage—especially of Nvidia’s prized chips. With its couple of data centers packed with GPUs and a long-standing relationship with Nvidia, CoreWeave quickly became vital to the accelerating AI hype train. The company picked up clients including Microsoft, OpenAI’s crucial sponsor, and image-generation startup Stability AI, according to former CoreWeave employees. Venturo’s biggest regret is not ordering more Nvidia chips back when he could. “If I had unlimited amounts, I could have it all sold in two weeks,” he says.
Things still worked out. As demand for CoreWeave’s GPUs surged through 2023, the company piled its new revenue into buying more of the chips and building out new data centers. A company that began as a beer-money side project now doesn’t touch crypto, and is all in on cloud computing. Over the past year the startup has picked up a $2.3 billion loan—using GPUs as collateral—and nearly $2.2 billion in investment funding, including $1.1 billion announced this week, from investors including Nvidia. With its latest infusion of cash, the startup’s valuation jumped to $19 billion.
By the end of this year, CoreWeave expects to have 28 data center campuses spread across a dozen or more US states, Europe, and potentially Asia—overall more than nine times its footprint at the beginning of 2023.
Note they’ve since more than doubled the number of data centers they operate while tripling their debt.
As of June, those lovable bros had sold $2.3 billion in stock since their IPO, per Bloomberg.
But let’s get back to their debt.
Ed Zitron Would Like a Word
In his October 6th piece, “Credit Crunch“, Zitron writes:
CoreWeave, which has Goatse-level spreads of 672bps to 882bps, with the effective yield on its shortest-dated debt (four years) sitting at 11.53% and its longest-dated (a mere six years) sitting at 13.49%.
There are, of course, ways around borrowing on your credit profile. For example, when CoreWeave opened an $8.5 billion delayed draw term loan facility in March 2026, it was able to get it rated as investment-grade and at SOFR (the percentage on overnight borrowing from the Fed for banks) plus 2.25%, all because the counterparty was Meta, and thus the underlying payments would be considered “safe.”
This may seem like the cheat code to get around all these horrifying rates, except CoreWeave, per analysts at UBS, needs to raise $102 billion in debt through 2030, which means it will have to keep raising on its own two feet.
Well, there’s a problem there.
Then he cites the following from The Information saying cracks are beginning to form” in the AI data center debt boom:
Bond markets are getting tough for lower-rated borrowers. One example: CleanSpark, which is developing a data center for Meta Platforms, had to offer investors big concessions to land financing earlier this month.
That deal is among the clearest signs yet that financing the data center boom is getting expensive across the board, and investors are getting picky about which new projects they’ll back. The bank loan market too is showing signs of strain, with some lenders like Société Générale, Sumitomo Mitsui Banking Corp. and Mitsubishi UFJ Financial Group becoming more selective in lending to data center projects, people arranging the deals say. Those dynamics mean companies could struggle to borrow for planned data centers, jeopardizing growth plans for the broader AI industry.
Zitron has more commentary on CoreWeave in “The Hater’s Guide To Junk” from the 9th:
…this industry needs hundreds of billions of dollars to fund the theoretical buildout of these potentially-possible data centers — CoreWeave alone, per UBS, needs to raise $102 billion in debt through 2030 — at a rate with no historical comparison. Even the railroad bubble of the 1800s had, based on rough calculations of inflation, only around $250 billion in total investment compared to the $400 billion in issuance expected from hyperscalers alone in 2027.
He also cites Standard & Poor’s discussion of CoreWeave’s material weaknesses in its accounting mentioned in its S-1:
CoreWeave’s efforts to address material weaknesses in internal control over financial reporting are progressing as we expected, but will remain a rating constraint until they are resolved. The company is working to address and remediate these weaknesses through IT risk assessments, enhanced control frameworks, and expanded finance and accounting staff. The measures also include engaging external advisors, completing an enterprise and IT risk assessment, and adding experienced senior leadership to strengthen oversight and execution.
While CoreWeave’s progress and timeline for addressing previously identified material weaknesses align with our expectations, potential credit risks could still arise so long as the weaknesses remain. This is because the company will be required to provide a management report on internal controls beginning with its 2026 Form 10-K, including diminished reliability of financial reporting and an increased risk of financial restatement or receiving an unqualified opinion from auditors, which would constitute a violation of its affirmative covenants under its credit agreements.
Nevertheless, based on the remediation efforts management intends to undertake throughout 2026, we expect the company to do so within this required timeframe.
…
NVIDIA’s $2 billion equity investment in CoreWeave in January 2026 nearly doubled its ownership stake and deepened commercial and technological integration. This includes preferential access to next-generation GPUs, leveraging their financial strength for multiyear AI factory buildout targeting more than 5 GW of incremental capacity by 2030, and integration of CoreWeave’s Mission Control and SUNK software into NVIDIA’s reference architectures.
We view the software integration as particularly significant, because it validates CoreWeave’s proprietary capabilities, enhances differentiation among neocloud providers, and introduces potential for incremental, higher-margin, asset-light software revenue over time.
Zitron goes on to add:
CoreWeave sits in the fourth tier of junk at B+, has been unprofitable for every single quarter of its existence, but is still only B+ because, and I quote, it has “broadened its customer base and reduced concentration through recent contract wins with Meta and OpenAI, as well as targeted efforts to engage downstream customers, including enterprises and AI labs.”
While S&P would argue that it’s making intelligent, market-based judgments, it is near-entirely basing its “positive” outlook on hype, to the point that it sees NVIDIA’s deeply-circular financing — which involves it renting back its own GPUs — as a good thing.
This is almost entirely nonsense, based on no practical evaluation of CoreWeave’s actual capacity, revenues or underlying technology. I would love to see someone from S&P explain what SUNK means, or who actually uses it — it is, from what I can tell, a specialist AI model training environment (making it unlikely to be used by any major AI lab, as they all have their own), and the one customer I can find is Impossible Inc, which I can’t find much about other than Naval Ravikant’s incomprehensible posts about it.
I should also add that NVIDIA’s $2 billion equity investment was not a means of “deepening its commercial and technological integration,” but a blatant attempt to make sure the company was capitalized enough to retain its current rating and continue to raise debt, and somehow NVIDIA backstopping CoreWeave’s data center leases didn’t come up in the evaluation.
This is the same baby-brained logic that potential creditors use too, because, to quote a friend of mine in fixed-income, nobody knows what they’re investing in.
Well, that’s reassuring.
Follow and support my work at NatWilsonTurner.com
Related Posts
- Banks Struggle to Digest the Mounting Debt Driving the AI Boom
- Another Epically Bad News Cycle for OpenAI, The Amoral Money Abyss
- Meta Makes Its Agentic AI Move With Muse
- Anthropic, OpenAI, Meta, SpaceX Sign Trump ‘Self-Policing’ AI Accords Amidst Financial Follies While Oracle Is Left Out
- AI Credit and Credibility Collapsing or Will the AI Booster/Doomers Power Through?
- AI Doomer Hypeloop Suspiciously Serves to Support OpenAI & Anthropic’s Agenda
- OpenAI Is Sinking Fast, Who Will It Pull Down With It?
- Stressed Oligarchs at Meta, OpenAI, and the Ellison Empire
- Ellison Empire Besieged On All Fronts
- Oracle’s Exploding Debt and Plummeting Stock Price Threaten Paramount Media Empire?
