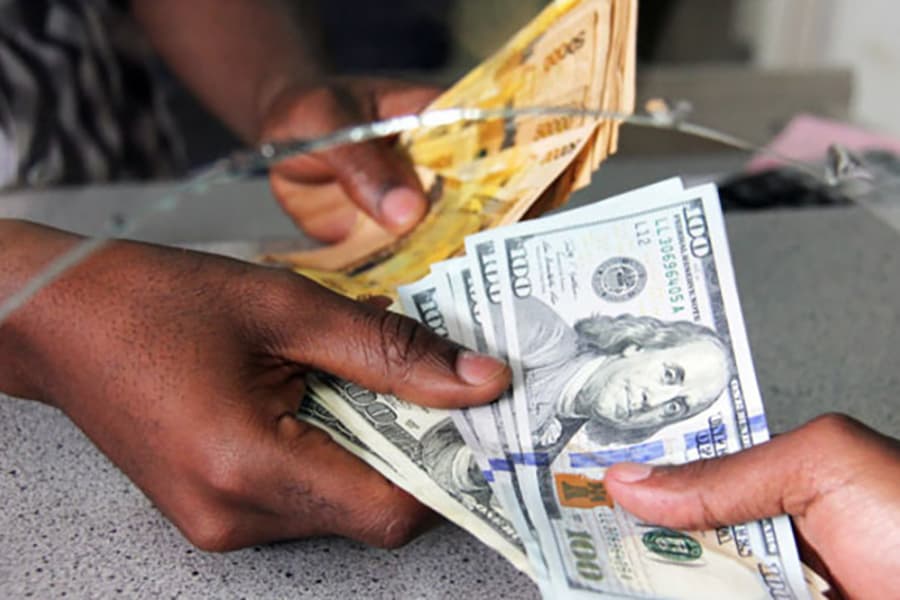
Bank of Uganda’s latest rate hike signals the urgency of stabilising the shilling, but its advice to businesses raises a question: could accepting lower profit margins help companies survive the currency shock and retain customers?
There was a revealing moment during this week’s monetary policy briefing by the Bank of Uganda (BoU) when a businessman’s question about the falling shilling prompted an answer that went beyond interest rates and foreign exchange interventions.
“As an importer of raw materials, I have experienced significant difficulties over the past two/three months as the shilling has depreciated sharply,” the businessman said.
“The increase in the cost of foreign currency has raised my liabilities and reduced my profit margins. Over the past year, the shilling has depreciated by more than 20%, wiping out my profits and affecting future business plans.”
He wanted to know what measures the central bank would take if the depreciation continued and how it would address reports that more than $200 million had left Uganda in two weeks.
Governor Michael Atingi-Ego said the bank had taken measures to slow the shilling’s depreciation, explaining that its role was to smooth excessive or erratic movements in either direction.
But Executive Director of Research Adam Mugume offered a particularly interesting observation for businesses struggling to navigate the turmoil.
“Businesses cannot necessarily maintain the same profit margins when exchange rate movements raise their costs and demand weakens,” Mugume said.
“Some businesses may have to reduce their margins to keep their products affordable and retain customers.”
His response raises a question worth considering: when costs rise and customers are under pressure, is insisting on the same profit margin always the best business strategy?
A weaker shilling means importers need more local currency to purchase the same amount of dollars. Businesses with dollar-denominated liabilities also face higher repayment costs.
For instance, an importer who previously needed Shs3.8 million to purchase $1,000 would require Shs4.1 million at an exchange rate of Shs4,100 to the dollar. That is an additional Shs300,000 before freight, insurance and other charges.
Passing these costs on to customers may seem necessary, but it risks reducing sales as consumers contend with rising food, transport and utility bills.
The pressure comes amid rising inflation. Uganda’s annual headline inflation increased to 4.6% in September from 4.1% in August, while annual inflation for energy, fuel and utilities reached 14.5%, according to the Uganda Bureau of Statistics.
The price of stabilisation
On October 14, BoU raised the Central Bank Rate (CBR) by 225 basis points, from 9.75% to 12%, in a bid to contain inflationary pressures and support the shilling.
Higher interest rates can make shilling-denominated investments more attractive, potentially encouraging capital inflows. However, they can also increase borrowing costs for businesses that need working capital to purchase stock or expand production.
Mugume said the measures were intended to prevent a temporary supply shock from becoming persistent inflation.
“The objective is to contain demand sufficiently to prevent a temporary supply shock from turning into persistent inflation and destabilising inflation expectations, without undermining Uganda’s longer-term growth ambitions,” he said.
That is a delicate balancing act. While stabilising the currency could ease pressure on importers, tighter monetary policy may make credit more expensive.
Mugume’s advice offers a practical lesson. A business that passes every additional cost to customers may preserve its margin per item but lose sales as prices rise. Accepting a smaller margin could help retain customers and protect market share.
That strategy has limits. Businesses cannot indefinitely sell below sustainable costs, particularly when they must pay salaries, service loans and replenish stock. They can, however, explore better supplier terms, reduce waste and review non-essential expenditure.
There is no guarantee that the shilling will recover quickly, and the central bank cannot shield every importer from exchange-rate losses. The outcome will also depend on foreign exchange supply, export earnings, investor confidence and international developments.
But the businessman’s question and Mugume’s response point to a difficult reality: in an economy where customers are also struggling, protecting their purchasing power may help protect a business’s future.
Sometimes, accepting less profit on today’s sale may be a strategy for keeping the business alive tomorrow.