Three months of declining container freight spot rates on the Asia-Europe trades were brought to an end this week when pricing reversed ahead of new FAK price hikes this month.
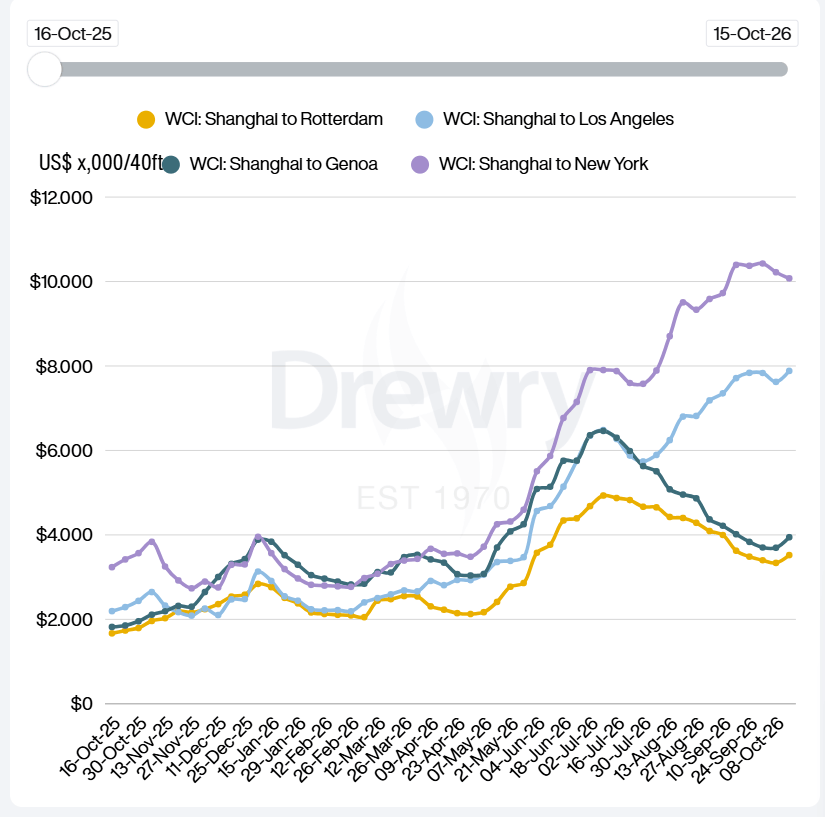
This week’s World Container Index (WCI) from Drewry saw the spot rate on its Shanghai-Rotterdam leg up 6% on the week before, at $3,522 per 40ft, while the Shanghai-Genoa route was up 7%, to $3,945 per 40ft.
Meanwhile, a range of new freight all kinds prices are due to be introduced by carriers on Monday, which forwarders said had been pushed back by a few days, and possibly explains this week’s rise.
The 19 October FAK rates range from: $4,200 per 40ft on Asia-North Europe and $4,600 on Asia-Mediterranean, as advised by Hapag-Lloyd; to CMA CGM’s $4,600 to North Europe and $4,700 to the Mediterranean; while MSC is looking for $4,500 per 40ft to both North and South Europe.
While this week’s WCI rise was enough to wipe out the past three weeks of Asia-Europe declines, forwarders told The Loadstar they expected rates to fall again.
“We did get FAK rate increases for the second half of October, and these were then pushed back to start 19 October, but I have received this morning downward revisions for those, almost back to the levels we saw in the first half of October,” one European forwarder told The Loadstar today.
“We’re not seeing any noticeable increase in demand – it’s all still a bit flat in that respect,” he added.
Meanwhile, another forwarder noted that, when carriers specified an end date to the FAK prices – 31 October by both MSC and CMA CGM – it usually suggested an expectation that rates were expected to soften.
“One useful indicator is when you see carriers place a time limit on the validity of their FAK pricing, as is the case now, because in my experience they don’t normally increase prices before that period expires,” the forwarder explained.
More concerning for forwarders and their shippers was the declining reliability of services, said Jon Charles, head of product at WiseTech, echoing many anecdotal reports The Loadstar recently received.
He said: “On Asia–Europe, the challenge we foresee is reliability rather than space. Only 9.9% of shipments arrived on time in September, and delays of eight days or more now account for almost half of volume, so building extra time into delivery commitments is essential.”
Meanwhile, MSC this week announced its Asia-North Europe Britannia service would be blanked in weeks 45 and 46, “due to ongoing market challenges”.
Source: Drewry
Spot rates on the transpacific trades diverged this week, with the WCI’s Shanghai-Los Angeles route up 3%, to $7,884 per 40ft, while its Shanghai-New York price continued a gradual descent that began three weeks ago.
This week it fell 1%, to $10,075 per 40ft, although Drewry noted that “strong US import demand continues to support transpacific rates”.
US west coast forwarder Freight Right said carriers had this week prioritised clearing backlogs that had built up during Golden Week, which made space for new bookings difficult to secure and propped up spot rates.
“Post-holiday backlogs are taking priority – containers rolled before or during the holiday are filling available slots, leaving fewer opportunities for new bookings,” it said.
“Vessel removals and service adjustments over recent months are keeping space tight – limited availability does not necessarily indicate stronger overall demand,” it added.