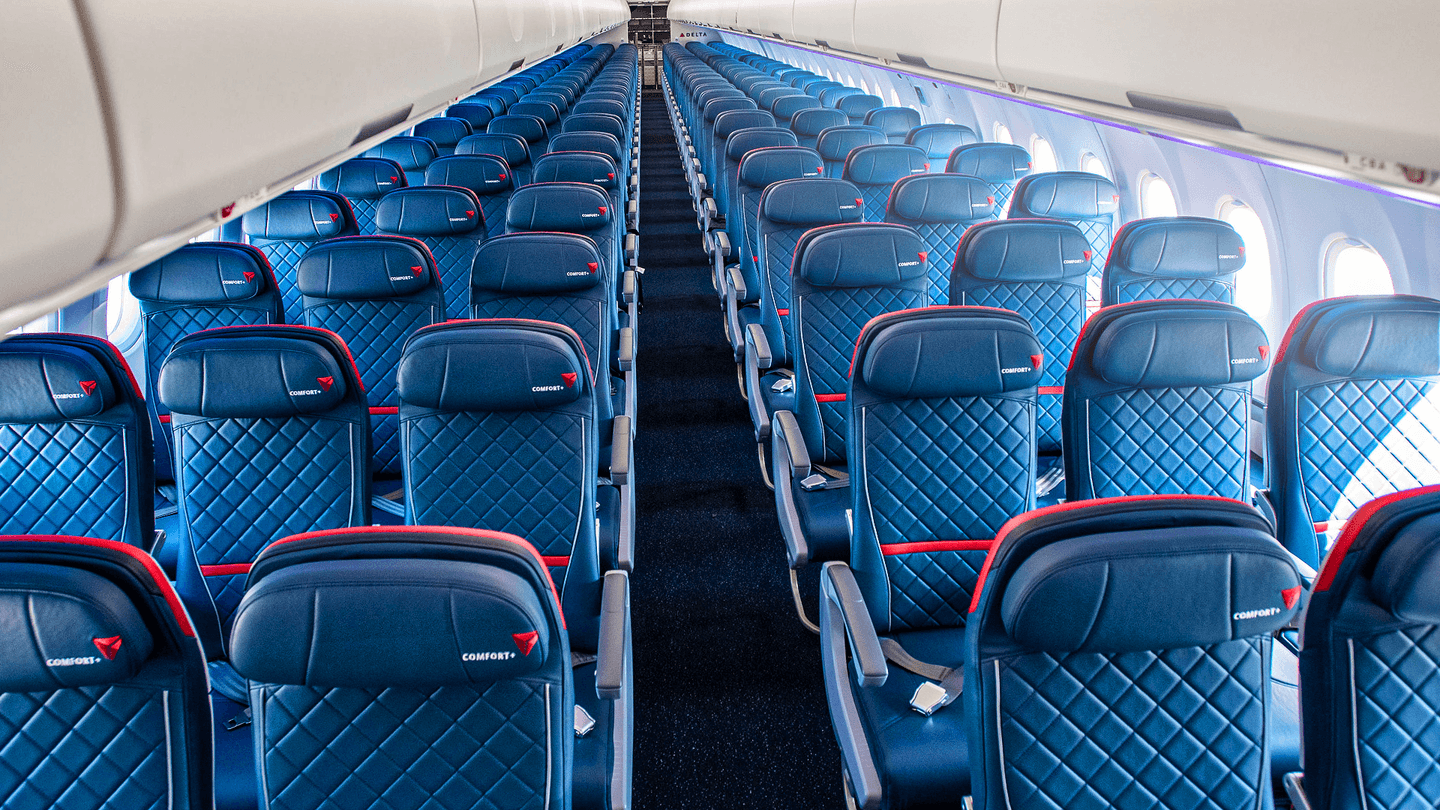
The most important change in the US airline cabin is not the disappearance of free snacks or another increase in checked-bag fees, but the growing realization that a few additional inches of legroom can be worth more to an airline than an entire row of traditional economy seats.  Delta Air Lines generated $6.92 billion in premium revenue during the second quarter of 2026.
This figure surpassed the $6.85 billion earned by Main Cabin, demonstrating that the industry's most valuable real estate was no longer confined to first class. That shift is changing the economics of the narrowbody aircraft, where airlines must squeeze the greatest possible return from every square foot of cabin space without making the experience so uncomfortable that passengers refuse to fly.
Delta Comfort+, United Economy Plus, and American Main Cabin Extra increasingly occupy an important space between standard economy and first class, letting airlines charge a meaningful premium for relatively modest physical improvements. The result is an industry increasingly designed to sell the same basic seat several times over, with different prices attached to the space around it.
The Revenue Tipping Point

Delta Air Lines' second-quarter results offer the clearest illustration of how far the premiumization strategy has progressed. Premium revenue reached $6.92 billion, edging past the $6.85 billion generated by Main Cabin, a milestone that would have been difficult to imagine when domestic economy seating represented the unquestioned commercial center of the aircraft.
Premium revenue includes more than extra-legroom economy, incorporating products such as first class and other premium offerings, but the crossover still illustrates how the industry's revenue priorities are changing. For airlines, the significance lies in the ability to generate more revenue without necessarily increasing the number of passengers carried.
A narrowbody aircraft such as the Airbus A321neo flying between  San Francisco International Airport (SFO) and
 Los Angeles International Airport (LAX) has a relatively fixed amount of cabin space, and adding another passenger or introducing a more elaborate service can create operational complications.
Charging an existing passenger more for a better-positioned seat, however, can deliver additional income without requiring a comparable increase in crew, fuel, or aircraft ownership costs. Extra-legroom economy benefits from sitting at an appealing intersection of price and perceived value.
Passengers who cannot justify first class may still pay to escape the tightest rows, particularly on business trips, connecting itineraries, or flights where comfort matters more than minimizing the ticket price. The airline captures spending from customers who would otherwise remain in standard economy, while preserving first class as a separate, more expensive product for travelers willing to pay substantially more.

The pricing power becomes particularly striking on short domestic routes, where the difference between the base fare and the extra-legroom surcharge can approach absurd proportions. A September 2026 fare sample for  United Airlines showed Economy Plus adding $99 to a $59 San Francisco to Los Angeles base fare, representing a 167% premium over the underlying ticket price.
Although the passenger is purchasing a seat with additional space rather than legroom in isolation, the comparison demonstrates how dramatically airlines can monetize a relatively small physical distinction. The underlying economics are attractive because the additional product frequently requires less investment than a traditional premium cabin.
An airline may designate existing exit-row seats as extra-legroom inventory, increase the pitch of selected rows, or adjust a cabin configuration during a broader refurbishment. These changes still carry costs, including lost seating capacity, certification requirements, and potential differences in maintenance or customer service.
However, they do not automatically require the expense of installing lie-flat seats, premium dining, or a separate business class cabin. The margin advantage therefore comes from selling an improvement that is expensive in perceived value but comparatively inexpensive to deliver.
A seat offering 34 to 36 inches of pitch can feel substantially less restrictive than standard economy, where some carriers have reduced pitch to approximately 28 inches. Because the passenger's willingness to pay depends on the value of the experience rather than the airline's incremental cost, even a modest adjustment to cabin geometry can create a disproportionate financial return when enough customers purchase the upgrade.
The Cabin Is Being Rebuilt Around Premium Demand

 American Airlines is pursuing one of the clearest examples of this change, with plans to increase premium seating from approximately 25 percent to 40 percent across its narrowbody fleet, including the new Airbus A321XLR. That is not simply a decision to offer more first-class seats.
Rather, it is part of a broader effort to allocate a greater share of the aircraft to customers willing to pay for differentiated products. Every additional premium seat represents a decision about which lower-priced seats will be removed, repositioned, or sacrificed to make room. The challenge is that cabin reconfiguration involves a permanent trade-off between passenger volume and revenue per passenger.
Removing standard economy seats can reduce the number of customers carried on a full flight. Meanwhile, increasing premium inventory creates the possibility of earning more from travelers who previously purchased the cheapest available fare. The calculation depends on route demand and aircraft utilization.
Whether customers consistently pay the premium rather than simply occupying upgraded seats through loyalty benefits is also a factor. Delta Air Lines is making a similar strategic bet across its network, while also assigning a substantial share of capacity on its forthcoming Airbus A350-1000 aircraft to premium seating categories.
Although widebody aircraft have different economics from domestic narrowbodies, the broader principle is consistent: cabin space should be allocated according to revenue potential rather than the assumption that economy must occupy the overwhelming majority of the aircraft. Extra-legroom seating becomes especially attractive when it generates premium revenue without requiring a fully separate cabin.
Seat Fees Are Becoming A Business Of Their Own

The financial appeal extends beyond ticket pricing because airlines can now treat seat selection as an independent revenue stream. United Airlines collected approximately $1.3 billion in seat fees in 2023, exceeding the roughly $1.2 billion it generated from checked baggage, illustrating how choosing where to sit has become commercially comparable to transporting a passenger's luggage.
A purchase that once seemed incidental to the ticket is increasingly an important part of the airline's overall revenue model. The wider market reflects that change, and other carriers such as  Southwest Airlines are also adapting their onboard offering. Global airline ancillary revenue has grown considerably as carriers separate previously bundled services.
Meanwhile, estimates place the seat-selection monetization market at $4.8 billion in 2025, with projections reaching $9.9 billion by 2034. Such forecasts depend on assumptions about future passenger demand and pricing practices, but they point toward a market in which airlines expect seat selection to become more sophisticated rather than less important. Dynamic pricing makes the opportunity even more attractive because the same seat does not need to carry the same price on every flight
An extra-legroom row may command a substantial surcharge on a busy Monday morning departure, then sell for considerably less on a lightly booked afternoon service. Airlines can adjust prices as departure approaches, taking account of remaining inventory, booking patterns, and customer demand, while avoiding the need to establish one fixed premium for every route.
The Loyalty Complication

Not every extra-legroom seat produces a cash payment, however, and this is where headline revenue figures require careful interpretation. Airlines frequently include preferred seating or extra-legroom access among the benefits offered to elite frequent flyers, while some passengers receive upgrades through credit-card benefits, corporate arrangements, or other promotional mechanisms.
These customers may value the product highly without generating a separate seat-selection payment at the time of travel. The commercial calculation therefore depends on more than the number of premium seats installed or the advertised surcharge attached to them. Airlines must determine how much inventory to reserve for paying customers, how much to make available as a loyalty benefit, and when to release unsold seats for purchase.
An overly generous policy can undermine the very pricing power that makes the product attractive, particularly when passengers learn that waiting until check-in frequently produces the same seat for free. Nevertheless, loyalty programs can also support premium seating economics by encouraging travelers to concentrate their spending with one airline.
A passenger who repeatedly buys extra-legroom seats may become more receptive to a co-branded credit card or a higher-status loyalty tier, creating value beyond the immediate transaction. The challenge is to preserve enough scarcity that customers continue paying for the product while ensuring that elite benefits remain meaningful enough to influence future booking decisions.
The Limits Of Premiumization
There is a physical limit to how far airlines can push this strategy, because every additional inch allocated to one passenger must come from somewhere else in a finite cabin. If standard economy becomes too cramped, passengers may respond by choosing another airline, booking a competing fare, or avoiding discretionary travel altogether.
The premium product is commercially powerful partly because the basic alternative remains available, but that relationship becomes less stable when the cheapest seats deteriorate too far. Competition also places limits on pricing, particularly on routes served by several carriers offering comparable extra-legroom products.
A $99 surcharge may be commercially viable when a flight is busy, and alternatives are limited, but much harder to sustain when another airline offers a similar seat at a substantially lower price. The strongest operators will be those that can combine carefully managed inventory with credible differences in cabin comfort, reliable operations, and a customer base willing to pay for those distinctions.
For now, extra-legroom economy occupies an unusually valuable position in the domestic aircraft because it can deliver premium pricing without the full cost structure of first class. As American Airlines, Delta Air Lines, and United Airlines continue refining their cabins and pricing systems, the decisive question is no longer simply how many seats an aircraft can carry.
Rather, it boils down to how much revenue each portion of its interior can generate. The standard economy seat remains essential to filling the aircraft, yet the few rows immediately ahead of it are increasingly central to determining how profitable that aircraft becomes.