A Royal LePage market survey released Thursday shows housing sales and prices down across the Greater Vancouver area
If 2021 felt like there were 50 buyers for every home listed in Vancouver, 2026 feels like the opposite.
Subscribe now to read the latest news in your city and across Canada.
- Unlimited online access to articles from across Canada with one account.
- Get exclusive access to the Vancouver Sun ePaper, an electronic replica of the print edition that you can share, download and comment on.
- Enjoy insights and behind-the-scenes analysis from our award-winning journalists.
- Support local journalists and the next generation of journalists.
- Daily puzzles including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
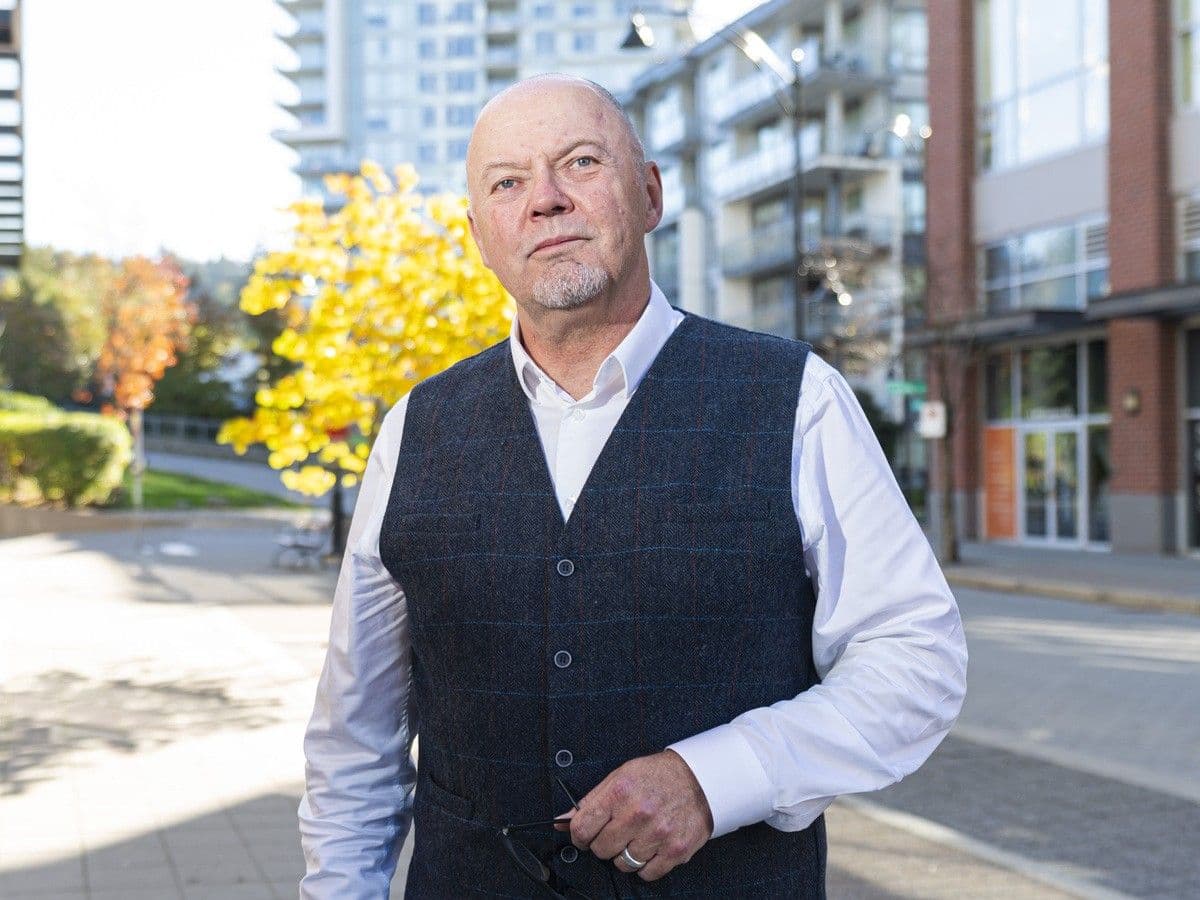
“Now you have 50 listings for every buyer,” said Randy Ryalls, managing broker with Royal LePage Sterling Realty.
A Royal LePage market survey released Thursday shows housing sales and prices down across the Greater Vancouver area, with further price drops expected in the final quarter of the year.
The aggregate price of a home in Greater Vancouver decreased four per cent year-over-year to $1.1 million in the third quarter of 2026, according to the Royal LePage report. The median price of a single-family detached home decreased 5.6 per cent year-over-year to $2 million, while the median price of a condo decreased 4.1 per cent to $710,000 during the same period.
Start your day with a roundup of B.C.-focused news and opinion.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of Sunrise will soon be in your inbox.
We encountered an issue signing you up. Please try again
Transaction volumes are running 25 to 30 per cent below the 10-year average.
While more choice and less competition should be good news for buyers, it hasn’t proven enough to move many off the sidelines.
“Heavy distractions” — such as geopolitical tensions, a trade war, and the coming elections — have caused people to put major market moves on hold, said Ryalls, who oversees 120 realtors from Vancouver to Maple Ridge.
“What’s also concerning is that the development industry has virtually ground to a halt,” he said. “Buyers are no longer lining up for pre-construction sales, and the investor class has gone quiet, (with) some even shifting capital to Alberta and Washington State.”
Ryalls said “mom and pop” investors who might have bought an apartment building in Vancouver might be able to afford two or three in Calgary. Some larger real estate developers have also been outspoken about the decision to shift focus to Alberta, where there are less taxes and bureaucracy.
“A whole bunch of things line up to make B.C. less attractive,” he said, listing rent controls, restrictions and the property transfer tax. At a time when the market is already slow, “it doesn’t help.”
Ryalls said there are various factors making the picture even more complex.
Many of Vancouver’s unsold units are small and were built with short-term rental or international students in mind. Those markets dried up when government policy changed.
There is also uncertainty over mortgage rates. Inflation may cause the Bank of Canada to raise rates, with homeowners who locked in during 2021 and 2022 looking at significantly higher rates when they renew.
Royal LePage president and CEO Phil Soper said he expects the bank to hold rates through 2026, with an increase more likely in early 2027 based on inflation.
“The prospect of higher borrowing costs typically draws some buyers into the market sooner than they would otherwise act. … (But) low confidence is outweighing the urgency to lock in today’s favourable borrowing costs,” he said in a news release.
The Royal LePage report also noted Canada’s “busy political calendar” has put damper on market activity. In B.C., municipal elections will be followed a week later by a provincial election.
“Elections can give buyers and sellers reason to pause while they assess what a change in government might mean for them,” said Soper. “This fall, some of the questions facing voters go well beyond tax policy or housing programs. A home is a long-term commitment to a community. Uncertainty about the future of that community … can make buyers reluctant to put down roots.”
Ryalls said stalled housing development could lead to an inadequate supply of homes in the future.
“If a developer can’t sell for the cost to build it, you don’t have housing being built,” he said. “You don’t need a crystal ball to see where this could go.”
Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.