
Premier Bank Chairman Arifur Rahman believes good governance can be restored to the banking sector if directors stop interfering in management, preventing loans from being diverted to unauthorised purposes and funds from being misappropriated under the guise of lending.
Given the current situation, he has called for reducing directors’ powers by limiting board representation to one person from each family.
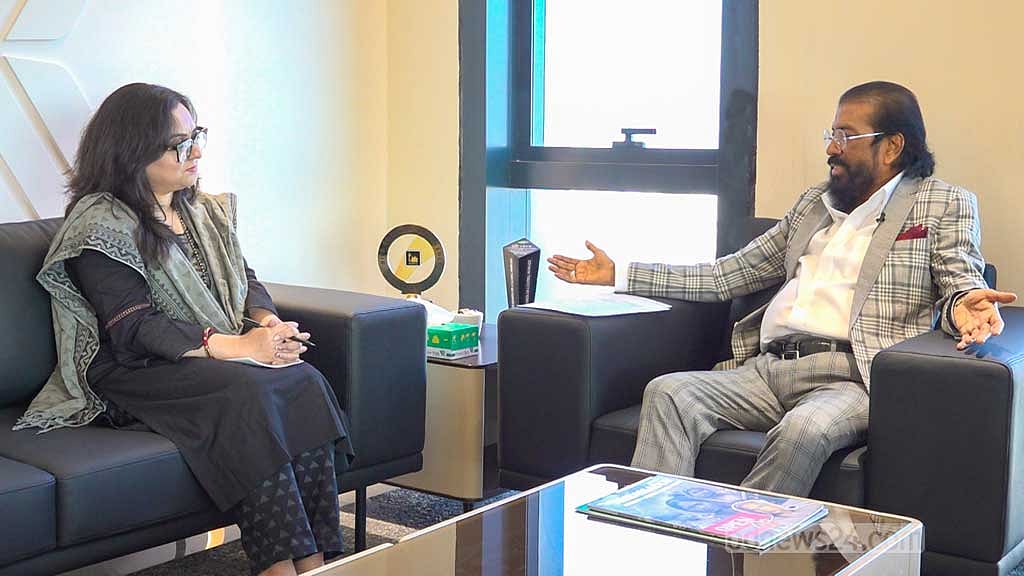
Arifur -- who transitioned from a career in medicine to becoming a banking entrepreneur -- shared his insights on the banking sector during bdnews24.com’s regular broadcast, “Chinwag with the Chiefs”.
The programme was streamed across bdnews24.com’s YouTube channel and Facebook page.
During the session, he discussed the current state of the banking sector and necessary reforms, Premier Bank's ongoing position, and his journey from practising medicine to manpower export before founding the bank.
While studying medicine, Arifur worked in journalism with Dainik Bangla and Bichitra.
As a physician, he served in war zones across Lebanon and Iraq, eventually becoming the personal physician to the Palestinian leader Yasser Arafat.
He later joined the medical team of the Saudi royal family, during which time he entered the manpower export business.
He subsequently entered the banking sector in the 1990s.
Arifur was also involved in filmmaking, producing a short film centered on garment industry workers and a feature film titled “Remakri”, based on children in the Chittagong Hill Tracts.
Following the change of government after the mass uprising in August 2024, Bangladesh Bank reinstated him to Premier Bank amidst wider financial sector restructuring.
Under his leadership, the third-generation bank has returned to normal operations as part of its turnaround strategy, Arifur claimed.
He joined the newly licensed Premier Bank in 1999 at the invitation of his friend HBM Iqbal, an Awami League politician and former MP.
Recalling the moment, he said: “[Iqbal] told me, ‘I have secured a licence for a bank. You are in business now and have capital. Put in some money, and let’s build the bank.’”
Arifur joined the board headed by Iqbal, who served as Premier Bank's former chairman.
However, when irregularities began surfacing roughly a decade later, Arifur resigned from his position as vice-chairman, remaining solely as a shareholder-sponsor.
Following the fall of the Awami League government on Aug 5, 2024 during the student-led mass uprising, the interim government initiated reforms across the financial sector.
In the initial phase, Bangladesh Bank dissolved the boards of 12 banks and reconstituted them with independent directors. Premier Bank was included in that list.
The central bank reinstated Arifur as a shareholder-director and appointed him chairman at that time.
Describing the situation when he took charge, he noted that Premier Bank’s funds had been siphoned off, leaving the institution drained.
“Whatever dividends were paid out previously were done through window dressing using fake accounts,” he said.
Arifur’s name was initially missing as a sponsor in the bank’s legacy records.
Claiming those records had been erased, he said Bangladesh Bank eventually verified his ownership through Dhaka Stock Exchange records, subsequently appointing him to the board as a shareholder-director.
The remaining five members of the board reconstituted in 2024 are independent directors.
Reflecting on the bank's current standing, Arifur noted that while many banks are currently struggling to reimburse depositors, Premier Bank remains stable, with customers able to conduct transactions according to their needs. “Not a single cheque has bounced. We haven't bounced cheques worth Tk 6,000 million, Tk 7,000 million, or Tk 8,000 million.”
Addressing corporate withdrawals, he said major business groups initially pulled out funds but have since returned, bringing in Tk 53,000 million in deposits over the past two years.
He emphasised that the bank no longer faces a liquidity crisis.
Acknowledging that money was misappropriated from Premier Bank prior to his tenure, Arifur said the current administration has stabilised the situation. “We have identified all the structural defects. To understand the extent of the damage in a bank, certain audits must be carried out.”
Accusing the previous board of inflating profits to siphon off capital, he said: “Window dressing in a bank means presenting falsified accounts. By doing so, benefits were extracted for years when, in reality, those gains did not exist. This occurred on a severe scale at the bank.”
Following his appointment as chairman, Premier Bank commissioned a forensic audit on the advice of Bangladesh Bank and the Bangladesh Financial Intelligence Unit (BFIU).
Highlighting this third-party assessment, Arifur said: “We conducted this forensic and standard audit using six external auditing firms.
“The purpose of the forensic audit was to pinpoint where money was stolen and where irregularities occurred. Uncovering these details was like lifting a rock to find a hornets' nest.”
He claimed the audit provided a clear picture of the funds siphoned off, adding: “We have now bandaged those wounds and are moving forward.”
Arifur explained that accumulated losses are being offset by cutting operating expenses, and to heal these financial wounds, Premier Bank is refraining from issuing new large-scale loans, focusing instead on its established corporate clients and regular repayers.
He rejected the notion that entrepreneurs are the true owners of a bank. “Whose money is it? It isn't mine. We [entrepreneurs] claim to own the bank, but how am I the owner? The money belongs to the depositors. They hold their deposits with you, so how can we claim ownership?
“In truth, we are simply the guards of the bank. We have no other duty. Our job is to safeguard the depositors' money.”
Under current Bank Company law, up to three family members can sit on a bank's board.
Commenting on this, he said: “No matter how prominent a sponsor you are, there should not be more than one family member on the board -- two at the absolute most.”
He also proposed reducing the tenure of directors.
On Premier Bank's non-performing loans (NPLs), Arifur said: “Premier Bank’s default loans stood at 65 percent, which we have brought down to 30 percent.”
He added that efforts are under way to reduce the NPL ratio further to 20 percent by December.
Asked about his vision for Premier Bank, the chairman said: “Our primary focus is safeguarding depositors' money, which we are doing. Our broader goal is to play a larger role in the national economy. We must keep the country's economic engine running.”
Having once envisioned turning it into a top-tier institution, Arifur added: “We want to brand ourselves as the people's bank. From rickshaw pullers, boatmen, and street vendors to top industrialists, we want to cater to everyone and participate in government projects.”
He noted that with the rollout of Bangla QR codes, rickshaw pullers can accept digital payments and vendors can be paid directly.
As a result, Premier Bank does not plan to launch a separate mobile financial service (MFS).
‘Directors Are To Blame When A Bank Sinks’
Arifur believes good governance in the banking sector can be achieved relatively easily if boards stop interfering in management.
“Instead of ensuring that management runs smoothly, if the board intervenes -- demanding why a specific loan wasn't issued, ordering debt write-offs, demanding discounts, or forcing the bank to rent their personal properties for branches -- then good governance is destroyed.”
He noted that recruitment based on personal recommendations has been halted at Premier Bank. “We have put an end to that practice.”
Addressing the long-standing view that board members bear the greatest responsibility for bank failures, Arifur said: “I agree 100 percent. The boards are responsible for ruining all the banks. If a branch manager steals, they get caught in two days.”
He added that financial misconduct by regular employees is exceptionally difficult given regulatory oversight. “It is very difficult for general employees because the regulatory systems are so strict. Problems arise when people like me interfere. Misappropriation happens when I choose to steal.”
Rather than shutting down defaulting businesses or imprisoning defaulters, he suggested stripping them of social privileges. “Their physical and mental comfort zones must be revoked.”