
With the weekly average retail diesel benchmark release delayed a day due to the Columbus Day holiday Monday, that lagging indicator is likely to show another decline even as most of the industry discussion these days has been decidedly bullish.
Since the Department of Energy/Energy Information Administration price was most recently published October 8, the futures price of ultra low sulfur diesel (ULSD) has been moving in its usual crazy volatility, a feature of the current market since the U.S. and Israel commenced military action against Iran at the beginning of March.
But the overall futures market trend in the last week has been higher. ULSD settled October 6 at $4.5694/gallon. Within two days it was more than $4.88/g. It then sunk to a settlement Monday of $4.7232/g, but it wasn’t clear that the Trump diesel deal had any impact; for all of the boasting President Trump did about the transaction, it was only down 1.52 cts/g on the day. (Permitting red dye diesel to be used over the road also has hit a regulatory maze and is largely being dismissed as well).
On Tuesday at 10:45 a.m. EDT, ULSD was turning in another typical day of volatility. It was at $4.8185/g, up 9.53 cts/g, or 2.02%. But it had been as low as $4.6431/g on the day, for a low to high swing at that point of about 17 cts/g.
Will Russia deal bring relief?
The DOE/EIA price to be released Wednesday will be the first since the Trump administration announced a deal to purchase Russian diesel, a transaction that has largely been dismissed as irrelevant to supply/demand trends (and the Tuesday upward movement at publication time suggests the broader market was dismissing it as well). The deal with Russia also has been criticized by some members of Congress and others as illegal.
While the DOE/EIA number used as the basis for most fuel surcharges is only a weekly number, and can be delayed during a holiday week, there are other price indicators about what’s happening at the pump.
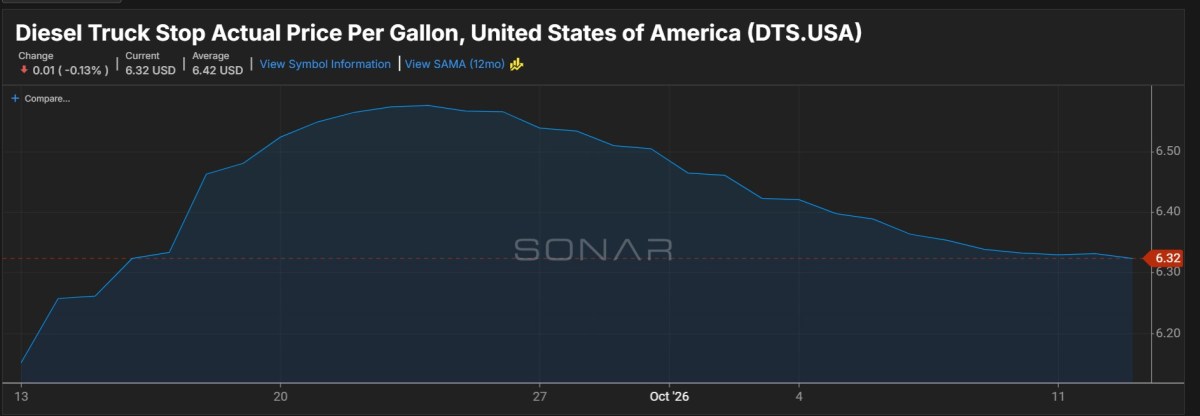
The AAA daily diesel price recently completed a 17-day run where the national average fell every day. At the start of that slide on September 22, the price was $6.5276/g. When it ended Friday, AAA said the average daily diesel price was $6.2785/g. It moved up and down slightly the next four days and Tuesday was largely unchanged from Friday.
The DTS.USA average retail diesel price in SONAR Tuesday was $6.32/g. The latest DOE/EIA diesel price was $6.199/g, effective October 5.
Part of the volatility in the market the past few weeks has been the swing in reports about how much oil is getting through the Strait of Hormuz. Without the one definitive number for the market to agree on, that sort of uncertainty will lead to volatility.
Shipments need help
But even if the number is high, as long-time analyst Paul Sankey told CNBC in an interview, what’s getting out is not transiting through the free flow of tankers that was the state of play before the war started.
“It’s supplied at enormous military cost,” Sankey said. “That’s how you’re getting the ships through, also with the shuttle tinkering. That’s another level of cost.”
He estimated those costs are probably worth about $35/b.
Under the terms of the diesel deal announced by President Trump, Russia is to immediately supply more than 300,000 metric tons of diesel to the world market. At a conversion rate of 7.45 barrels of oil per metric tonne, the formula used by S&P Global Energy in its calculations, that works out to 2.235 million barrels.
The rest of the deal would be another 500,000 tonnes in November and 1 million tonnes soon after. At the conversion rate of 7.45 barrels per metric ton, that is 3.725 million b/d for the November quantity and double that for the supply to come after that.
U.S. daily consumption of all non-jet fuel distillates, according to the most recent report from the EIA, is about 3.65 million b/d. For the members of the OECD, which consists of most Western economies, daily diesel consumption is estimated at about 13 million b/d.
A report from S&P Global Energy quoted Masha Kotkin, a fellow at the Center for Strategic and International Studies, as saying “the amount of diesel Russia can provide would be a drop in the bucket compared to global demand. If you are asking about US diesel prices, I don’t think it’s going to make a difference. It is not very much in the scheme of things.”
It’s the products, not the crude
The move by the Trump administration to secure additional diesel supplies ultimately goes back to the reality that even if flows out of the Strait of Hormuz are increasing, irrespective of whether they only got there through U.S. military support, consumers buy refined products, not crude.
In a separate CNBC interview, Ellen Wald of Transversal Consulting said markets have been able to avoid even higher spikes in price through a wide variety of steps, including drawdowns from strategic stocks. But that has limits.
“We have seen some incredible resilience in the market,” Wald said. “We’ve seen an ability to work around and for the market to find workarounds. But at a certain point, things are going to start to give, and we’re seeing that as prices are creeping higher and higher. Any attempts to bring them down that aren’t actual new sources of supply don’t really last.”
I haven't encountered a more revealing sentence yet about the #diesel market in China, this one from @TheEconomist: "Squeezed by rising costs, some stations now make customers buy cigarettes to get any diesel, the scarcest of all fuels." pic.twitter.com/xPvbYPgqs3
— John Kingston (@JohnHKingston) October 13, 2026
(Editor’s note: the picture is AI-generated.)
Beyond the latest Russian diesel deal, and before that the agreement by G7 nations earlier this month to release additional strategic stocks, reportedly after a U.S. threat to implement a diesel export ban if they did not, there are the broader stock releases that were agreed upon by the members of the International Energy Agency in March.
IEA executive director Fatih Birol on Saturday tried to give a push to the ongoing releases and have them go faster.
“Members that have not yet fully delivered the volumes pledged under the March Collective Action look to see if they are able to accelerate the remaining releases to fulfil this prior commitment, prioritising diesel,” he said in his statement. He also noted that “some members have already released greater volumes than they initially pledged in March.”
More articles by John Kingston
FMCSA’s Elison: ‘weeks’ away from fixing Motus user experience
Wall Street analysts positive on C.H. Robinson deal; S&P more cautious
FMCSA split sleeper berth pilot program moves closer to launch
The post Russian diesel deal having limited impact, if any, on prices appeared first on FreightWaves.