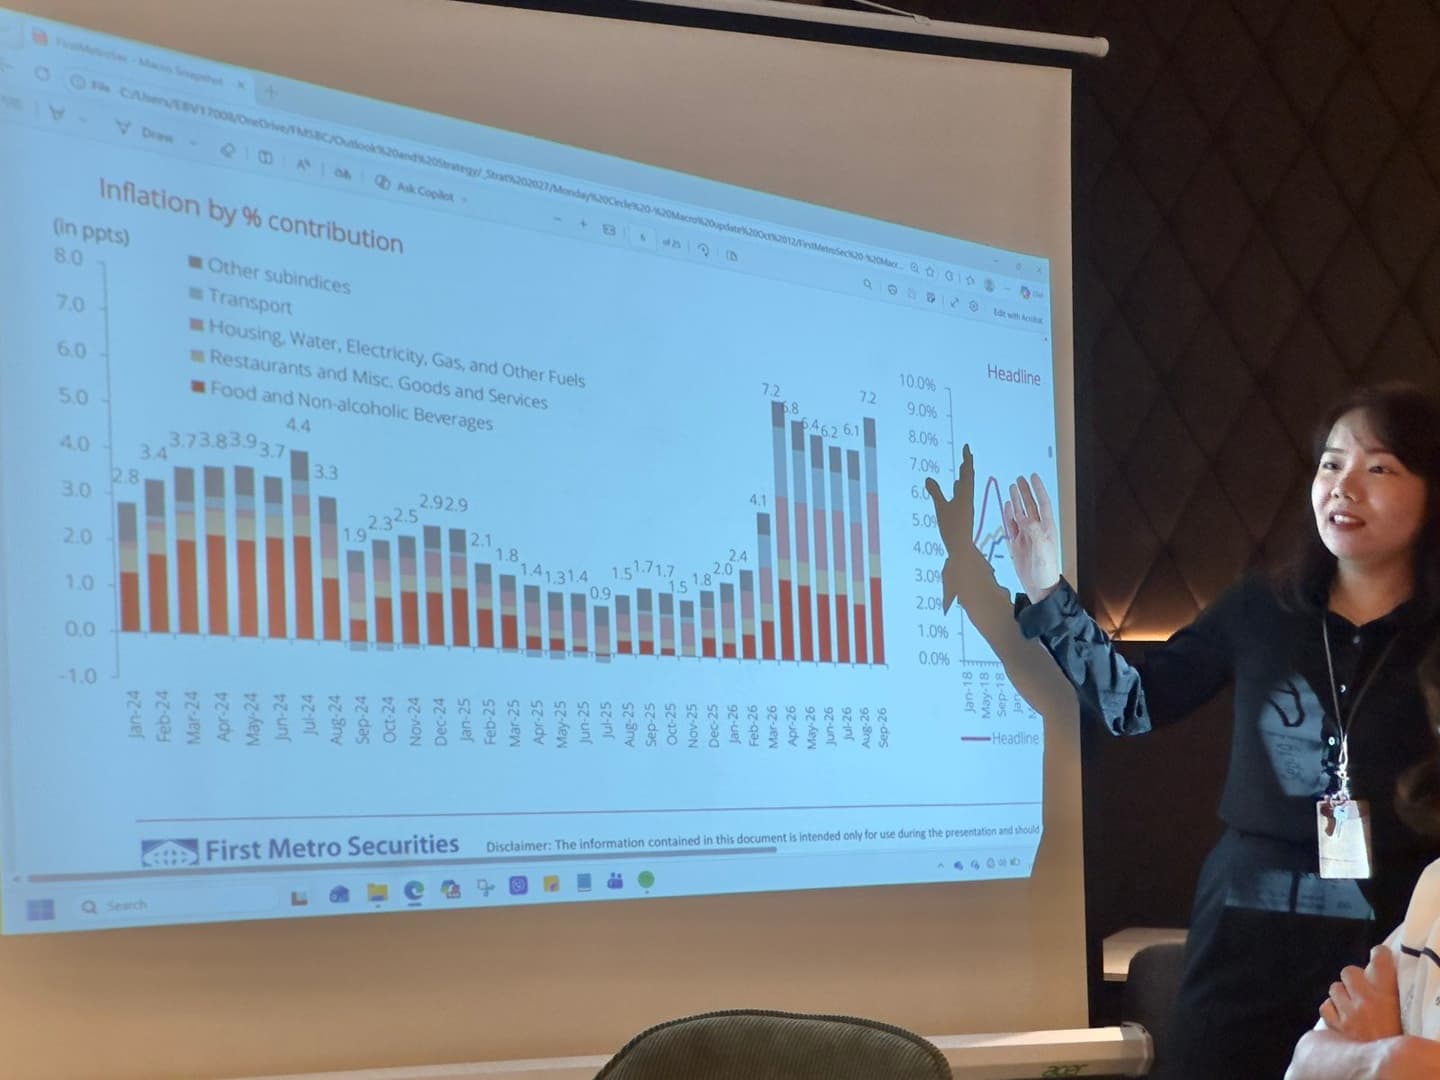
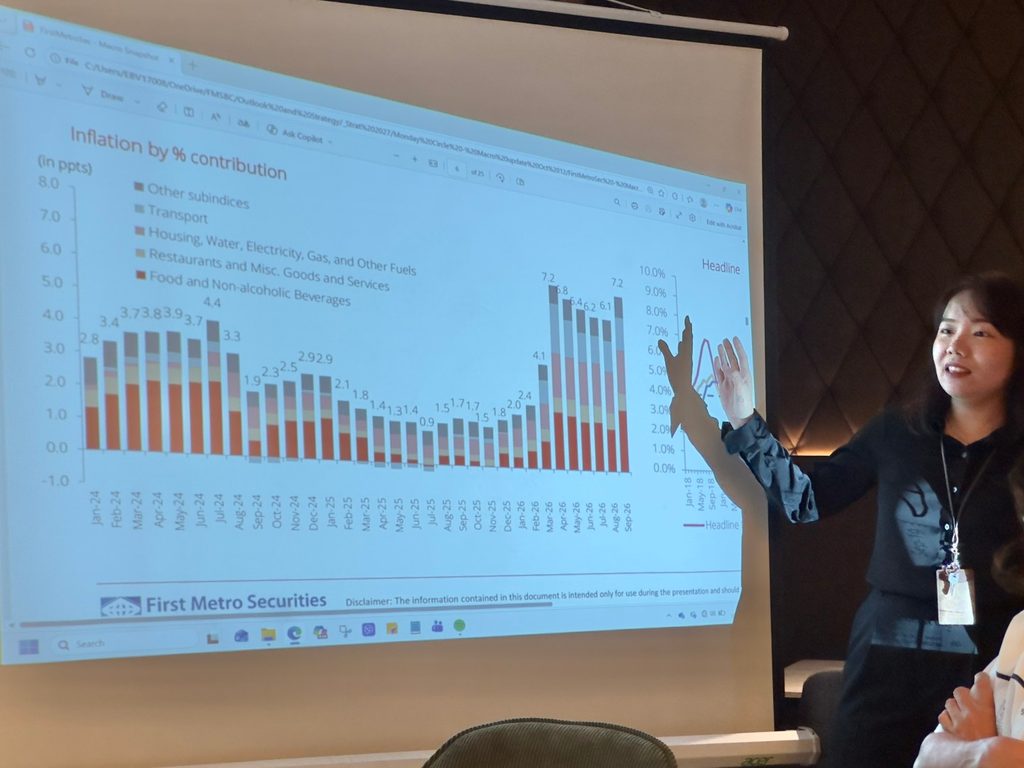
Last Monday, October 12, a discussion on the current state of the economy was held by the members of the Monday Circle. The talk was led by Estella Dhiel B. Villamiel, who serves as the head of institutional research at First Metro Securities Brokerage Corporation (FirstMetroSec) and is an active member of the select group. The update revealed sobering realities about the economy especially for its near-term status that would explain the reasons behind the present variable softness of the stock market – bringing to mind the trading strategy of the market adage, “Buy when there’s blood in the streets, even if it’s your own blood.”
The axiom is also sometimes paraphrased into “in your hand.” Nevertheless, it is a foundational maxim of contrarian investing. It means that the absolute best time to buy assets or invest money is during a severe market crash or panic, when everyone else is terrified and selling.
While the imagery projected by the adage refers to a market in total chaos, we are not yet there, according to the presentation of Villamiel. So far, the problem is about structural headwinds rather than about catastrophic panic. But, come to think of it, we could just be a blink away from it considering what is happening in and out of the country.
Titled “The Philippine Economy At A Glance,” Villamiel described the macroeconomic overview of the Philippine economy to be under severe external headwinds, primarily driven by the economic strain caused by an external oil shock triggered by a US-Iran war, which has created a negative domestic transmission chain, namely: rising oil prices, a widening import bill, a weakening Philippine peso, and elevated inflation.
Economic overview
The country’s gross domestic product (GDP) from January to June this year has slowed down to 2.6%. Outside of the pandemic years, this represents the slowest economic expansion the country has experienced in nearly two decades since 2009. To achieve the government’s full-year target of 3.5% to 4.5%, the economy must expand at a much faster rate of 4.4% to 6.4% in the second half (2Q) of the year.
Looking at the demand-side breakdown, household consumption growth has cooled down from historical highs down to 1.9% in 2Q26. This means consumers are in “survival mode.” This is worrying because the people are sticking to buying essential goods for they are paying at higher prices for lesser quantities.
Capital formation (investments) has, as well, sharply fallen, dropping by -9.2% year-on-year (YoY) in 2Q of 2026, severely weighing on economic momentum.
Complicating the situation, inflation hit 7.2% in September, bringing the year-to-date (YTD) average at 5.4%. This is way past the 2% to 4% comfort band of the government. Driving the economy in this situation are transport and food costs due to high fuel prices, with local transport sharing a 65% correlation with Brent crude prices. Full-year inflation is projected at 6.1%.
To stop prices from rising even more and to protect the peso, the Bangko Sentral ng Pilipinas (BSP) raised its target reverse repurchase (RRP) rate to 5.0% last August 27. This measure made loans, mortgages, and credit card debt much costlier than before. Due to this rate increase, car sales growth – excluding electric vehicles – has plummeted sharply into negative territory, hitting roughly -10% YoY by the end of August 2026. People are just pulling back on big-ticket items like cars because loans are too expensive.
On the fiscal side, the first half 2026 budget deficit reached 5.8% of GDP, pushing the national debt-to-GDP ratio to an elevated 66%.
Credit card usage also reached historic highs. Unfortunately, this shift has triggered a 46.4% spike in non-performing credit card debt, signaling that a growing number of households are facing severe financial distress.
Because the Philippines is a net importer of fuel, higher energy costs require a larger outflow of US dollars to sustain domestic consumption. With such, the peso has experienced significant depreciation against the US dollar, primarily driven by escalating global oil prices.
Concurrently, the domestic job market exhibits underlying structural weaknesses despite stable headline employment figures claiming 94% to 96% full employment. The rolling 12-month net job metrics register a structural loss of 307,000 jobs, signaling contraction in key employment sectors as unemployment rose to 5.3%, up from 3.9% last year.
Furthermore, rising underemployment rates as manifested through the number of workers seeking additional hours, indicating that existing positions fail to provide sufficient income to meet the cost of living.
Instead of concluding her assessment on how much more the economy may suffer, Villamiel ended her presentation on what could trigger the recovery of the economy.
According to her, economic recovery for the country is fundamentally conditional on resolving the Middle East shipping bottleneck.
If commercial vessel traffic through the Strait of Hormuz recovers from current single-digit daily lows back to its pre-war average of about 33 per day, the following stabilization sequence will occur: global oil risk premiums will drop, directly cooling domestic transport CPI; the import bill will narrow, relieving pressure on Gross International Reserves (estimated at US$100 billion) and allowing the peso to strengthen; and easing inflation will allow the BSP to halt or reverse rate hikes, reviving depressed household credit and corporate capital expenditure.
Market call
I agree with Villamiel’s position that the current market fall and the economy’s problem of being squeezed by high prices, weak growth, skyrocketing energy costs, a widening import bill, a depreciating Philippine peso, and elevated inflation, could possibly bottom out and come to an end in a short time with the Middle East shipping bottleneck being resolved soon.
On the other hand, the chances of the US-Iran war ending soon is said to be low, as diplomatic talks have stalled and military escalations have intensified in recent days.
But like the way how the contrarian strategy works, it may be hard to imagine under the present circumstances, the shipping bottleneck in the Middle East could just be resolved sooner than is expected. – Rappler.com
A veteran stock market analyst, Den Somera has long years of professional experience in investment banking and stockbroking and founder-convenor of The Monday Circle. You may reach the writer at kapitaltek@gmail.com
This article has been prepared for general circulation for the reading public and must not be construed as an offer, or solicitation of an offer to buy or sell any securities or financial instruments whether referred to herein or otherwise.
Below are some personal finance tips from the author you may have missed: