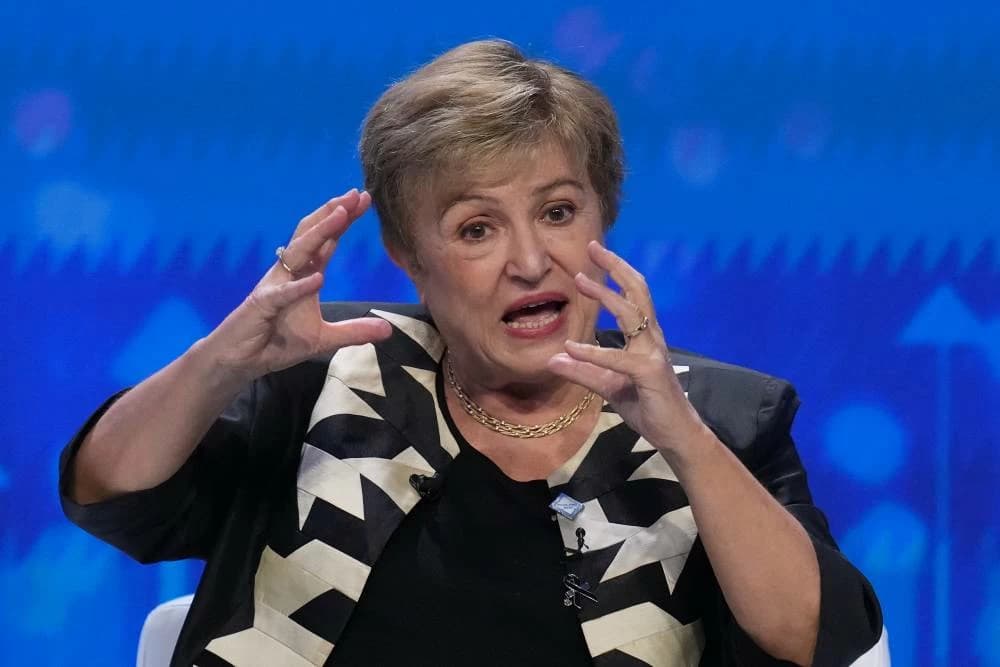
Bangkok: International Monetary Fund (IMF) Managing Director Kristalina Georgieva on Wednesday urged the United States and other wealthy nations to take urgent action to reduce mounting debt levels, warning that rising public debt is placing growing pressure on low-income countries and the global financial system.
Speaking at the annual meetings of the IMF and World Bank in Bangkok, Georgieva said US Treasury Secretary Scott Bessent and other American policymakers recognise that the country’s federal deficit and national debt have reached unsustainable levels. However, she cautioned that economic growth alone would not be sufficient to address the issue.
“At the Fund, we believe that growth, of course, helps, but it cannot deliver fast enough the necessary adjustments,” Georgieva said.
“There is no magic. You have to move in the direction of tightening, bringing debt down and reducing deficits.”
Rising debt levels and global inflation, partly linked to higher energy costs resulting from the Iran war, have pushed interest rates to multi-decade highs, increasing financial pressures on the world’s poorest nations.
Efforts to restore debt sustainability through fiscal consolidation have faced setbacks following extensive government spending during and after the COVID-19 pandemic.
Rodrigo Valdes, Director of the IMF’s Fiscal Affairs Department, warned that fiscal risks continue to increase while many countries have failed to respond adequately.
“Fiscal risks are rising, and a proper reaction is largely absent in many countries,” Valdes said. “In major advanced economies, the effect of fiscal indiscipline does not stop at the border. It travels to the rest of the world.”
The IMF’s latest Fiscal Monitor noted that, among the world’s poorest countries, interest payments have reached record levels relative to government revenues, while declining aid flows have created funding gaps that some nations are unable to fill.
The report said many governments are being forced to choose between supporting vulnerable populations and meeting debt repayment obligations.
Alexander De Croo, former Prime Minister of Belgium and Administrator of the United Nations Development Programme (UNDP), said developing countries face significantly higher borrowing costs than advanced economies.
“Today the median developing country is paying three times more on its interest repayments than developed countries,” De Croo said.
On average, nearly 10% of government expenditure in developing economies is directed towards debt servicing. Combined with elevated prices for fuel, fertiliser and other essential goods, the effects of the El Niño climate phenomenon and higher borrowing costs have left many low-income countries struggling to recover.
“I don’t see a light at the end of the tunnel,” De Croo said.
Job creation remains another major concern, particularly as advances in artificial intelligence threaten to replace some traditional occupations. More than 1.2 billion young people are expected to enter the global workforce over the next decade, while forecasts suggest only 400 million net new jobs will be created.
To address the challenge, the UNDP this week launched the “Jobs for Prosperity” initiative, which will work with governments, development banks and private-sector partners to encourage investment in job-generating sectors such as tourism, healthcare and food processing.
De Croo said the initiative will focus on helping countries attract investment by strengthening governance, improving policy frameworks and developing pipelines of investable projects.
“These are things that are feasible,” he said. “It has been proven that you can do it in many places around the world.”