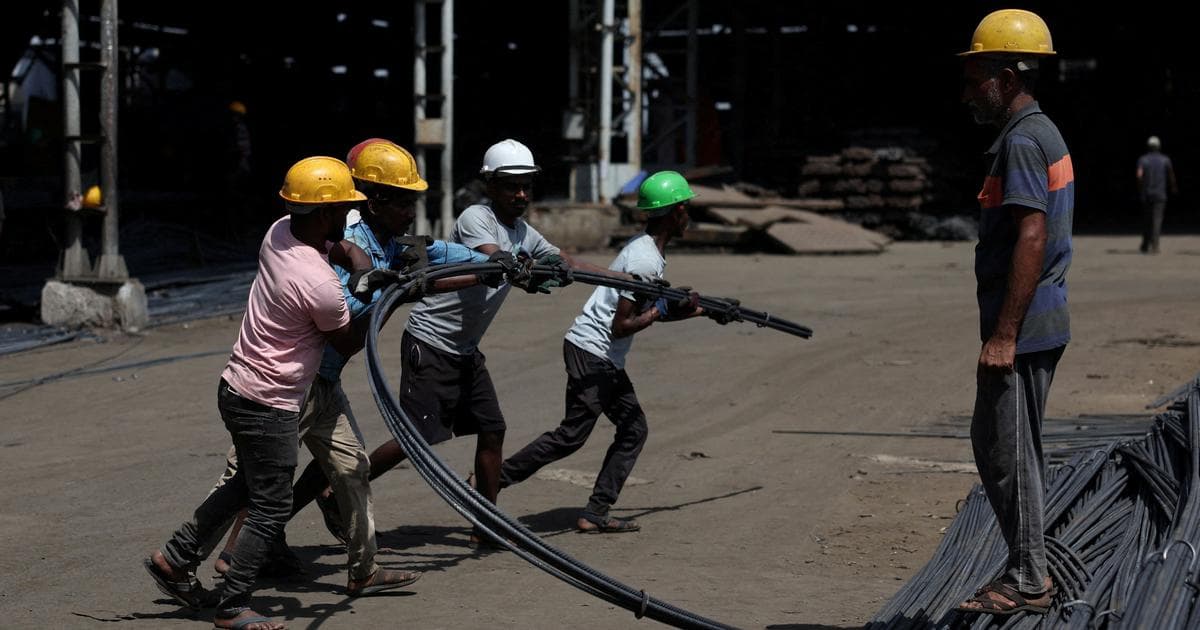
The steel industry announces itself early on the road from Raipur airport into the city. Hoardings for Goel TMT, GK TMT, Concrete TMT and many others appear one after another. These steel brands are deeply interwoven with Chhattisgarh’s economy but are barely known outside the state.
Farther out, towards the industrial clusters of Urla and Siltara, the advertisements give way to the plants themselves: ironmaking units, rolling mills, steel-melting shops, trucks carrying coal and iron ore, and stacks of steel bars and tubes waiting to be transported across the country. The air changes, too, thick with smoke and dust. The environmental cost of steelmaking is difficult to miss, but so is its economic importance.
These industrial clusters support tens of thousands of workers and a much larger network of transporters, traders, contractors and small suppliers. They also reflect a wider reality across India.
The micro, small and medium-size enterprises that largely make up the “secondary” steel sector are responsible for around 40% of crude steel production in India, the world’s second-largest steelmaking nation. They supply steel for construction, industry and infrastructure, all while operating on tight margins and relying heavily on coal to make direct reduced iron, also known as sponge iron. This, along with scrap metal, is...