Piotr Arak and Velina Tchakarova
Bottom lines up front
- The prevailing narrative describes the EU as a project in structural decline.
- The EU, however, has the economic power, strategic vision, and structural assets it needs to act as a credible compound power.
- Only willingness to act constrains European agency.
Table of contents
Executive summary
Introduction: Rethinking the balance sheet
Chapter 1: Mindset
Chapter 2: The single market and the economies of scale
Chapter 3: Geography, corridors, and enlargement
Chapter 4: Infrastructure, energy, and supply chains
Chapter 5: Six policy priorities
About the authors
Acknowledgements
Executive summary
The European Union (EU) enters the second half of the 2020s under sustained external pressure of the second Trump administration’s transactional stance toward allies, Chinese industrial overcapacity and trade surplus, Russia’s protracted war in Ukraine, the conflict in Iran, and a global trading system increasingly organized around economic security rather than open exchange. Against this backdrop, the prevailing narrative describes the EU as a project in structural decline—pointing to lackluster 1.7 percent average EU growth in the decade from 2014 to 2024, a productivity gap of roughly 20 percent with the United States, weak performance in frontier technology, and the regulatory burden documented in various EU reports. This report argues the opposite. The EU has already built the structural assets it needs to act as a credible compound power. The constraint on European agency is not a question of capacity. It is a willingness to act.
An analysis of the chapters that follow yields six findings:
1. The EU’s strategic mindset is catching up to reality, but converting ideas into action remains the core obstacle.1When a reference to “Europe” is meant in its broader geographical sense—encompassing all European countries—that is explicitly stated.
Russia’s invasion of Ukraine, the Niinistö preparedness doctrine, Mario Draghi’s report on European competitiveness, and President Emmanuel Macron’s Sorbonne speech collectively represent the EU’s most consequential strategic awakening since the end of the Cold War.2Sauli Niinistö, Safer Together: Strengthening Europe’s Civilian and Military Preparedness and Readiness, October 30, 2024, https://commission.europa.eu/document/download/5bb2881f-9e29-42f2-8b77-8739b19d047c_en?filename=2024_Niinisto-report_Book_VF.pdf.; Mario Draghi, The Future of European Competitiveness, September 9, 2024, https://commission.europa.eu/topics/competitiveness/draghi-report_en; Emmanuel Macron, “Europe—It Can Die. A New Paradigm at the Sorbonne,” April 26, 2024, transcript, https://geopolitique.eu/en/2024/04/26/macron-europe-it-can-die-a-new-paradigm-at-the-sorbonne/. Yet doctrine has so far outrun delivery. The gap between adopting a strategy and executing it—the “conversion problem”—is now the EU’s central operational challenge. When geopolitical urgency, administrative focus, and political coalition align, the EU system can move with considerably greater speed than its critics acknowledge. The constraint is institutional, not cognitive.
When geopolitical urgency, administrative focus, and political coalition align, the EU system can move with considerably greater speed than its critics acknowledge.
2. The EU is the world’s largest external trader and the only major bloc with surpluses in both goods and services.
In 2024, exports of goods and services by the EU’s twenty-seven member states to nonmember countries reached $4.43 trillion—13.7 percent of global exports—compared to $3.75 trillion exported by China (11.6 percent) and $3.19 trillion by the United States (9.9 percent). On the only comparable measure of external trade, the EU is the world’s largest trader, leading China by roughly $670 billion and the United States by $1.2 trillion. The structural composition matters as much as the volume: Of the thirty most economically complex economies in the world, eighteen are EU27 member states. The EU’s export base is the most diversified high-complexity productive space in the global economy, anchored in pharmaceuticals, aerospace, specialized chemicals, machinery, luxury, and processed agri-foods. These sectors feature high entry barriers that state-directed industrial policy cannot replicate on Beijing’s timescales.
3. The EU has the world’s largest aggregate balance sheet and the most conservative aggregate fiscal stance among major blocs.
The EU27 saves 24 percent of gross domestic product (GDP)—compared to 16.6 percent in the United States. Its net international investment position reached approximately $652 billion in 2025, one of the largest net creditor positions in the global economy.3World Bank WDI (NE.EXP.GNFS.CD) for total exports; Eurostat (ext_lt_intratrd, ext_ser_bec01) for EU27 extra-EU goods and services exports 2024; WTO Statistical Review 2025. Meanwhile, the United States deteriorated to net external liabilities of $27 trillion, the largest debtor position in history. In 2025, the International Monetary Fund (IMF) estimated that EU27 general government debt was at 82.5 percent of GDP, against 123.9 percent for the United States and 99.2 percent for China (with augmented debt substantially higher). The EU’s balance sheet is the only one of the three that does not depend on a single structural fragility to sustain itself. The constraint is that European savings finance American innovation rather than domestic productive investment, primarily because the EU’s capital markets are less than a third as deep as those of the United States. Completing the Capital Markets Union is the single highest-return institutional reform available to the bloc, and it comes at a near-zero additional public cost.
Completing the Capital Markets Union is the single highest-return institutional reform available to the bloc, and it comes at a near-zero additional public cost.
4. The European single market is the world’s largest integrated economic space and the EU’s most credible coercive instrument.
Free movement of goods, services, capital, and people adds an estimated 9 percent to the EU’s GDP every year. The single market in goods is largely complete; the single market in services, capital, energy, and digital is not. The IMF estimates that remaining intra-EU barriers translate on average to a 44 percent tariff on goods and a 110 percent tariff on services—three times higher than barriers between US states. Completing the services market alone would add €1.8 to €2.1 trillion to the EU’s GDP—the equivalent of adding an economy the size of Spain to the bloc’s productive output. Market access is the EU’s primary coercive instrument: For most of Eurasia, large parts of Latin America, and significant parts of Africa, access to the European single market is the strategic variable that no other partner can match.
5. Geography and enlargement are the EU’s most distinctive strategic instruments—and the eastern flank is now the operational center of European grand strategy.
Because of Russia’s war against Ukraine, the EU has shifted its strategic center of gravity eastward. The Black Sea, the Eastern Mediterranean, and the Western Balkans now sit at the center of European geopolitical priorities, with enlargement to Ukraine, Moldova, Iceland (the strategically significant Arctic-North Atlantic case, distinct from the eastern enlargement track) and the Western Balkans serving as the EU’s most powerful long-term instrument. Each accession extends the regulatory perimeter, deepens the market, and anchors additional states within Western institutional architecture, while demonstrating empirically—as Russia has discovered since 2022—that the cost of exclusion from European market integration compounds faster than the effects of military attrition. The widening-versus-deepening debate is analytically obsolete: Enlargement is deepening, when properly executed.
6. The EU has broken its energy dependence on Russia and is rebuilding the industrial base of a hard-power producer.
The Russian share of EU gas imports fell from approximately 40 percent in 2021 to 12 percent by early 2025. The shift represents the most consequential energy infrastructure transformation since the post-WWII coal-and-steel era, achieved through the LNG capacity buildout; a new generation of firm, long-lived baseload capacity across France, Poland, Romania, the Czech Republic, and Bulgaria; and renewables growth under REPowerEU. Several initiatives and trends are aimed at fostering an emerging European hard-power manufacturing base for the first time since the end of the Cold War: The ReArm Europe envelope of €800 billion in defense investment from 2025 to 2030 (of which €150 billion is from the EU-backed Security Action for Europe (SAFE) instrument and €650 billion is from relaxed Stability and Growth Pact rules permitting greater member-state defense spending), combined with the EU CHIPS Act (€43 billion targeting 20 percent of global semiconductor production by 2030), the Critical Raw Materials Act, the Net-Zero Industry Act, and the structural integration of Ukraine’s defense industry into the European industrial ecosystem. The challenge is not strategic but operational, including constraints on production capacity, workforce, and regulatory certainty.
These findings point to six policy priorities:
- Complete the Capital Markets Union to channel European savings into European productive investment;
- Defend and strategically deploy the EU’s trade surplus position through market access conditionality;
- Expand the single market and EU membership or associate membership to Ukraine, Moldova, Iceland, and the Western Balkans;
- Align industrial policy with economic-security objectives through the CHIPS, Critical Raw Materials, and Net-Zero Industry Acts;
- Provide regulatory certainty through stabilized ETS, EDIP, Strategic Technologies for Europe Platform (STEP),4ETS: EU Emissions Trading System, the EU’s carbon market. EDIP: European Defence Industry Programme, supporting joint defense procurement and production. STEP: Strategic Technologies for Europe Platform, directing EU funds toward critical technologies. and energy union completion; and
- Deepen the single market in services and capital, where the untapped integration gains remain the largest.
This report is not a defense of the status quo. It is a call to recognize, measure, and activate the EU’s existing structural leverage. The “simultaneity engine”5The “Simultaneity engine” and the “simultaneity approach” refer to the same underlying framework. The simultaneity approach is the analytical doctrine: European strategic agency must be reorganized around the compound, with trade, industrial, energy, enlargement, and defense policy deployed concurrently rather than sequentially. The simultaneity engine is the operational metaphor used here to describe that doctrine once activated. It is the machinery of compound deployment, built and ready to run, rather than a separate concept.—the things needed to reorganize Europe so that it can work in compound, concurrent fashion rather than sequentially—is built: It needs operators with the strategic confidence to run it at full capacity. The primary constraint is activation; the necessary endowment is already there.
Introduction: Rethinking the balance sheet
When Christine Lagarde told the World Economic Forum in January 2026 that Europe must “decide what we need to do to be strong by ourselves,”6Stephen Collinson, “Trump’s Davos Hosts Might Abhor Him but He’s Worth Listening To,” CNN, January 21, 2026, https://www.cnn.com/2026/01/20/politics/trump-nato-hosts-davos-greenland-analysis. she framed a question the European leaders have been circling for a decade. The honest answer is harder than the question suggests. It is not that Europe lacks the strategic assets to be strong on its own but rather that Europe has grown accustomed to underestimating the assets it already has.
Too often, the EU is assessed through a narrow macro lens, one that focuses on quarterly growth, fiscal fragmentation, the absence of European tech giants, the perceived slowness of Brussels’ decision-making. On those metrics, Europe tends to look worse than the United States or China. But Europe is not built for speed or brute scale. It rests on a dense export base, deep institutional stability, the world’s largest pool of household savings, and the most distributed skilled labor force in the developed world. As French President Emmanuel Macron put it at the same Davos meeting, “Having a place like Europe, which sometimes is too slow, for sure, and needs to be reformed, for sure, but which is predictable, loyal, and where you know that the rule of the game is the rule of law, is a good place.”7“Davos 2026: Special Address by Emmanuel Macron, President of France,” World Economic Forum, January 20, 2026, https://www.weforum.org/stories/2026/01/davos-2026-special-address-by-emmanuel-macron-president-of-france/.
This report sets out the comparative balance sheet. It begins with the macro picture—output, income, and share of the world economy at purchasing power parity—read across three decades and using the right metrics. It then moves to assets where the EU already leads: external trade, household and sovereign balance sheets, common fiscal capacity, and the single market. It is honest about where the EU lags—chiefly in capital markets—and concludes that it does not need to outgrow the United States or outproduce China. The EU already shapes how the global economy works.
Europe is not built for speed or brute scale. It rests on a dense export base, deep institutional stability, the world’s largest pool of household savings, and the most distributed skilled labor force in the developed world.
The “simultaneity approach”8The simultaneity approach holds that European strategic agency must be reorganized around the compound, not the sequential. Trade policy is industrial policy is energy policy is enlargement policy is defense policy. This framework was developed by one of the authors to describe how middle powers operate under concurrent geopolitical pressure in various publications on Substack from 2026. See e.g.,: Velina Tchakarova (2026), The Hard Geopolitical Truths No One Wants to Hear in Europe, https://velinatchakarova.substack.com/p/the-hard-geopolitical-truths-no-one; Velina Tchakarova, Marco Felsberger, and Herbert Saurugg, “Global Systemic Rupture: The Fourth Systemic Crisis and Its Architecture,” GfKV, April 12, 2026, https://gfkv.org/wp-content/uploads/2026/04/GfKV-Global-Systemic-Rupture-The-Fourth-Systemic-Crisis-and-Its-Architecture.pdf. that organizes the analysis throughout the report rests on a simple premise: The EU’s power, when properly reckoned, is already sufficient to navigate the Cold War 2.0 between Washington and Beijing and Moscow—otherwise known as the “DragonBear,” an alliance based on mutual strategic interests in opposition to the Western-led order. What the EU lacks is not the structural capacity but the institutional discipline to deploy that endowment at speed and at scale. The chapters that follow map where these capabilities sit, what their deployment requires, and where the institutional friction lies.
Chapter 1: Mindset
The first challenge is cognitive
An honest assessment of European power must begin with an uncomfortable observation: The EU’s central strategic deficit is not a shortage of resources. It is a conversion problem. The European Union represents a continental market of over 450 million consumers, the world’s most expansive regulatory architecture, trade relationships that span every major economy on earth, a deep institutional memory of civilian-military integration, and an alliance structure—the North Atlantic Treaty Organization—whose combined might is unparalleled. And yet, the Union has consistently struggled to translate these assets into coherent, timely, and geographically disciplined strategic action. That gap between potential and performance is not accidental. It is the product of an institutionalized habit: the habit of delayed prioritization.9Velina Tchakarova, “A Grand Strategy for Europe in the New Cold War,” The Republic Journal, December 8, 2025, https://therepublicjournal.com/essays/europes-grand-strategy-in-the-new-cold-war/.
The EU’s problem is cognitive before it turns material. For a generation after the Cold War, European strategic culture was based on the comfortable assumption that the world was converging around liberal norms, that hard power was a residual instrument of last resort, and that the Union’s civilian power—its legal order, its market access, its development finance, its power to shape global standards10The EU sets de facto global standards because firms and states find it cheaper to comply with EU rules across global markets than to maintain separate regimes.—was sufficient to manage its neighborhood and project influence beyond it. The result was a security culture in which the language of risk mitigation replaced the grammar of hard power, in which preparedness was associated with crisis management rather than the deliberate cultivation of deterrent capacity, and in which the possibility of major interstate war on European soil was viewed as an analytical anachronism.11Piotr Arak, Marek Flis, and Kamil Kutwa, A Union of Nations 2.0: Ideas for EU Reform (Warsaw: Polish Economic Institute, 2018), https://pie.net.pl/wp-content/uploads/2021/12/A_Union_of_Nations_2.0.pdf.
Russia’s full-scale invasion of Ukraine on February 24, 2022, served as a brutal, empirical refutation of that assumption. But the broader lesson of the years since—including the first year of US strategic uncertainty under the second Trump administration—is that the necessary cognitive adjustment is more profound than deciding to boost defense budgets. The EU must change what it plans for, what its institutions regard as normal, and how its decision-making systems behave under pressure. That is a mindset shift in the most precise and operational sense of the term.12European Commission and European External Action Service, White Paper for European Defence – Readiness 2030, March 19, 2025, https://commission.europa.eu/document/download/e6d5db69-e0ab-4bec-9dc0-3867b4373019_en?filename=White+paper+for+European+defence+%E2%80%93+Readiness+2030.pdf. In addition, Andrius Kubilius, European commissioner for defense and space, argues that “Europe needs three explosions at once: a financial big bang, an industrial big bang and an intellectual big bang.”13Wojciech Przybylski, “Europe Needs an Intellectual Big Bang after Ankara: Industrial Ramp-Up Will Not Stand without Political Preparedness,” Visegrad Insight, July 7, 2026, https://visegradinsight.eu/nato-summit-ankara/.
The strategic awakening is real—and insufficient
While the primary challenge is cognitive, as this chapter argues, the awakening to that fact has begun. The Niinistö report,14Niinistö, Safer Together. commissioned by the European Commission in 2024, states with striking directness that treaty commitments to security have not translated into a shared attitude of security. The report calls for comprehensive preparedness across civilian and military domains, treating societal resilience not as a soft add-on but as a load-bearing element of European defense. The 2025 Preparedness Union Strategy15European Commission, “EU Preparedness Union Strategy,” accessed July 28, 2026, https://commission.europa.eu/topics/preparedness_en. goes even further: It explicitly names fragmented, reactive, and siloed crisis management as a structural weakness, calls for a profound change in the European mindset, and links everyday regulatory and infrastructure choices to the Union’s capacity to function under adversarial pressure. The March 2025 Defense White Paper–Readiness 203016European Commission and European External Action Service, White Paper for European Defence – Readiness 2030. then sets the operational benchmark: Ukraine is described as the immediate front line of European defense, and European readiness by the end of the decade becomes the stated test of whether the Union can act as a strategic entity.
These are not rhetorical gestures. They represent a genuine doctrinal shift inside the European institutional system. For the first time in the EU’s history, Brussels has formally acknowledged that the gap between what the Union says about security and what it is institutionally designed to do about it is strategically dangerous. The formulation captures the problem with precision: The EU has mastered the language of risk mitigation but has not yet made preparedness the default operating mode of its public institutions.17The Niinistö’s report states plainly that legal treaty commitments to shared security “have not been fully transformed into an attitude where security is seen as something shared across the EU,” and proposes a “preparedness-by-design principle” as the corrective. Conceding that there is a gap—as the European Commission itself has done—is itself a form of strategic progress. It removes the pretense and names the structural weakness with a candor that, until recently, was confined to the margins of expert commentary.
Emmanuel Macron’s April 2024 Sorbonne speech18Macron, “Europe—It Can Die. A New Paradigm at the Sorbonne.” served a similar function at the level of political leadership in Europe as a whole. His claim that Europe is mortal—that its postwar institutional architecture cannot be taken for granted and that the pace of the Union’s strategic organization remains dangerously slow relative to the speed of external change—was not new as analysis. But it was new as an articulation by a major member-state’s leader using the language of existential urgency rather than reformist technocracy. The competitiveness review chaired by Mario Draghi in September 202419Draghi, The Future of European Competitiveness. completed the triangle by collapsing the boundary between economic governance and security strategy. The Draghi report argued that a Union that cannot fund innovation, sustain its defense-industrial base, and reduce its critical dependencies not only weakens economically but also deteriorates strategically. These three texts—from Niinistö, Macron, and Draghi—alongside similar recent contributions20Enrico Letta, Much More than a Market—Speed, Security, Solidarity: Empowering the Single Market to Deliver a Sustainable Future and Prosperity for All EU Citizens (Brussels: European Council, April 2024), https://www.consilium.europa.eu/media/ny3j24sm/much-more-than-a-market-report-by-enrico-letta.pdf; Christian Noyer, Developing European Capital Markets to Finance the Future (Paris: Direction Générale du Trésor, April 25, 2024), https://www.tresor.economie.gouv.fr/Articles/2024/04/25/developing-european-capital-markets-to-finance-the-future; Manuel Heitor et al., Align, Act, Accelerate: Research, Technology and Innovation to Boost European Competitiveness (Brussels: European Commission, 2024), https://op.europa.eu/en/publication-detail/-/publication/2f9fc221-86bb-11ef-a67d-01aa75ed71a1/language-en.—form the basis of the EU’s strategic-awakening narrative. That narrative has now been institutionalized outside the bodies that produced it, with the launch of the Rhine Group in August 2026, a Geneva-based forum convened by Draghi and Stripe’s Patrick Collison that gathers economists, entrepreneurs, and policymakers under Chatham House Rule to advance the competitiveness agenda where the commission’s own machinery has stalled.21“A Stronger, More Competitive Europe,” Rhine Group, August 25, 2026, https://www.rhinegroup.eu/. Its composition marks the limit of the concession, since the cohort that presided over two decades of European underperformance has constituted itself as the corrective, while Central and Eastern Europe, where growth is still occurring and the mindset gap is least pronounced, is represented among roughly fifty members by a single former Estonian president.
Where the deficit persists: The conversion problem
The awakening may have started but it remains incomplete, and hindering completion is the lag between doctrine and delivery. Christopher Hill’s updated formulation of the capability-expectations gap22Christopher Hill, “The Capability-Expectations Gap in a Time of War,” Studia Europejskie—Studies in European Affairs 1 (2025): 21–38, https://journalse.com/pliki/pw/1-2025-Hill.pdf.—first developed in the early 1990s—remains painfully apposite: The interval between what the European Union says it will do and what it can coherently do has widened, not narrowed, since 2022. Daniel Fiott’s 2025 analysis of strategic autonomy23Daniel Fiott, “The Three Images of EU Strategic Autonomy: Perspectives on Wedging, Binding and Hedging,” Journal of European Integration 47, no. 6 (2025): 825–42, https://www.tandfonline.com/doi/full/10.1080/07036337.2025.2537369. reveals that the EU continues to oscillate between three positions—wedging to preserve leverage over the United States, binding allies to shared commitments, and hedging against strategic uncertainty—without achieving lasting political consensus around any of them. The result is a Union that speaks in the vocabulary of agency but lacks the institutional instinct to prioritize, and then to implement swiftly. Enrico Letta’s “One Europe, One Market Roadmap”24Cyrille Louis, “Enrico Letta au Figaro : « Si chacun reste seul dans son coin, nous serons tous mangés par les Américains et les Chinois »,” Le Figaro, July 24, 2026, https://www.lefigaro.fr/international/enrico-letta-au-figaro-si-chacun-reste-seul-dans-son-coin-nous-serons-tous-manges-par-les-americains-et-les-chinois-20260724. turns precisely on this second deficit; he argues that its significance lies not in any new agenda but in imposing discipline on a shared legislative timetable that binds the European Commission, Parliament, and Council to hard deadlines.
The conversion problem operates at several levels simultaneously. At the level of procurement and defense production, the gap between declared ambition and actual orders placed remains substantial. European defense-industrial capacity is growing but is not yet on a war-economy footing, and transformer and component lead times measured in years rather than months remain a structural constraint. At the level of decision-making, the unanimity requirement in foreign and security affairs continues to function as a de facto veto for actors willing to weaponize procedural rules for transactional ends, as Hungary demonstrated on Ukraine-related decisions between 2022 and early 2026.25Lili Bayer, “Ukraine’s Path to EU Will Be Tough With or Without Hungarian Hurdle,” Reuters, October 6, 2025, https://www.reuters.com/world/europe/ukraines-path-eu-will-be-tough-with-or-without-hungarian-hurdle-2025-10-06/. At the level of strategic culture, the institutional tendency to treat every hard choice as an opportunity for process—to extend timelines, multiply consultations, and defer politically sensitive tradeoffs—persists even as the threat environment demands tempo.
There is, however, one important corrective to the standard declinist narrative. Public opinion data from 2024 to 2026 consistently shows that EU citizens are considerably more strategically serious than European elites tend to assume. Spring 2025 Eurobarometer26European Commission, Standard Eurobarometer 103–Spring 2025 (Brussels: European Commission, 2025), accessed July 28, 2026, https://europa.eu/eurobarometer/surveys/detail/3372. found that over 80 percent of respondents supported a common European defense and security policy, that nearly the same proportion identified Russia’s invasion of Ukraine as a direct threat to European security, and that strong majorities backed increased defense cooperation at the EU level. Polling by the European Council on Foreign Relations in 202527Ivan Krastev and Mark Leonard, “Trump’s European Revolution,” European Council on Foreign Relations, June 23, 2025, https://ecfr.eu/publication/trumps-european-revolution/. showed a more transactional and sober assessment of the United States—a recognition that the American guarantee is neither automatic nor cost-free—alongside a receptivity to the EU taking a stronger strategic role. The implications of this for the post-heroic diagnosis—the theory, advanced first in the 1990s, that Western societies would no longer tolerate casualties in war, which in turn shapes public attitudes about national defense posture28Tine Molendijk, “War Is Back in Post-Heroic Europe: Change and Continuity in the Relationship Between the Armed Forces and Society,” Armed Forces & Society 52, no. 1 (2026): 29-53, https://journals.sagepub.com/doi/10.1177/0095327X241281663.—are significant. The primary bottleneck to converting strategic concern into strategic capacity derives less from public opinion than from elite decision-making capacity, institutional speed, and the scale of political and administrative cohesion required to move a twenty-seven-member union decisively in a contested environment. Mindset, properly understood, is an elite operating-system problem.
Four interlocking institutional mechanisms reproduce the conversion failure. First, the principal-agent fracture: Twenty-seven principals with divergent threat perceptions and electoral calendars must consent simultaneously, setting the EU’s decision speed to its slowest consenting member. Second, the absence of crisis-executive authority: No individual or institution can direct resources across policy domains at crisis tempo; every emergency response must be assembled through ad hoc coalition-building. Third, the siloed policy architecture: European Commission Directorates-General operate within separate legal bases and stakeholder ecosystems, producing the CHIPS Act, the Critical Raw Materials Act (CRMA),29European Parliament and Council of the European Union, Regulation (EU) 2024/1252 Establishing a Framework for Ensuring a Secure and Sustainable Supply of Critical Raw Materials (Critical Raw Materials Act), adopted April 11, 2024, https://eur-lex.europa.eu/eli/reg/2024/1252/2024-05-03/eng. the Net-Zero Industry Act, and the Anti-Coercion Instrument as parallel legislative tracks rather than as components of a single compound deployment. Fourth, the electoral-cycle mismatch: Strategic investments requiring ten- to twenty-year horizons are governed by four- to five-year political mandates, and the EU has no commitment device equivalent to the IRA’s ten-year tax-credit lock to bind future cycles. These four mechanisms interact: The unanimity veto empowers individual principals to block cross-pillar coordination, the absence of executive authority means each blockage requires political negotiation rather than institutional override, and the electoral mismatch ensures that even successful coordination produces instruments with uncertain durability. The conversion problem is not a single institutional defect. It is a system hobbled by interlocking features.
The strengths that strategic doctrine could leverage
Four structural strengths the EU possesses as a middle power deserve emphasis because they are neither hypothetical nor residual. They are ready to be strategically deployed if the conversion problem is addressed with genuine seriousness.
The first strength is regulatory and standard-setting authority. The European Union possesses a unique ability to shape global technology, supply chain, environmental, financial, and digital governance. This projection of its internal rules—known as the Brussels Effect”30Anu Bradford, The Brussels Effect: How the European Union Rules the World (New York: Oxford University Press, 2020).—is unmatched by any other non-superpower. The General Data Protection Regulation,31General Data Protection Regulation (GDPR), European Commission, accessed July 28, 2026, https://commission.europa.eu/law/law-topic/data-protection_en. the AI Act, carbon border adjustments, and financial supervisory architecture all demonstrate that Europe can impose costs and create dependencies far beyond its immediate neighborhood through non-military instruments.32Bradford, The Brussels Effect. This regulatory reach is not soft power in the pejorative sense. Deployed with strategic intent, it constitutes a form of structural leverage over corporate, governmental, and financial actors whose behavior it shapes across jurisdictions.
The second strength is institutional durability. The EU’s governance architecture—however imperfect or prone to blockage at key junctures—is the most elaborate experiment in voluntary multilateral political integration in recorded history. That durability under severe stress—such as the 2008 financial crisis, the 2015 migration crisis, the COVID-19 pandemic, Russia’s invasion of Ukraine, the re-emergence of US strategic ambivalence—is itself a strategic asset.33European Council, Strategic Agenda 2024–2029 (Brussels: European Council, June 27, 2024), https://www.consilium.europa.eu/media/4aldqfl2/2024_557_new-strategic-agenda.pdf. A Union that has survived recurring crises with its core institutions intact possesses a resilience that adversaries have consistently underestimated and analysts have taken for granted.
The third strength is alliance embeddedness. NATO membership and a strategic partnership with Washington provide the Union with intelligence access, interoperability standards, deterrence architecture, and extended nuclear guarantees. Even when US protection is not automatic, no independent European arrangement could replicate these benefits in the near term. A middle-power strategy for Europe is not a plea for strategic autarky. Instead, it is an argument for bearing a larger share of the collective burden—becoming a more capable, demanding ally rather than a passive consumer of US security.34Sven Biscop, “A Grand New European Security Strategy,” Egmont Institute, March 19, 2026, https://www.egmontinstitute.be/a-grand-new-european-security-strategy/. The Union’s strength lies precisely in its capacity to be indispensable to the alliance system rather than merely dependent upon it. The fourth strength is the still-unmatched enlargement toolkit. No other actor in Europe’s neighborhood possesses an equivalent instrument for producing stable political space, reforming governance, anchoring economies, and creating long-term strategic depth through the conditional integration.e alliance system rather than merely dependent upon it.35European Commission, Communication from the Commission to the European Parliament, the European Council and the Council on Pre-Enlargement Reforms and Policy Reviews (Brussels: European Commission, March 20, 2024), https://commission.europa.eu/document/download/926b3cb2-f027-40b6-ac7b-2c198a164c94_en. That toolkit is addressed at length in the next chapter, but its relevance to the mindset argument is immediate: An EU that views enlargement as a strategic instrument of the first order, rather than as a complex administrative process attached to external relations, is an EU that understands the source of its comparative advantage.
Preparedness-by-design: From metaphor to operating doctrine
The practical takeaway from this analysis is clear: The EU should adopt preparedness as its governing strategic doctrine—not as a metaphor for heightened concern but a concrete operational principle embedded across budgeting, regulation, procurement, infrastructure planning, energy policy, and public administration. Preparedness-by-design means that every major regulatory decision asks whether it strengthens or weakens the Union’s capacity to function under adversarial pressure. It means that military mobility, dual-use infrastructure, strategic stockpiling, and critical-node redundancy are treated as investment categories rather than as emergency line items.
It also means reconceiving strategic autonomy. The most defensible formulation is not European separation from the United States—an analytically confused and practically self-defeating objective—but European capacity to carry a larger strategic burden inside the alliance system: to sustain conventional deterrence on the eastern flank, to impose costs on adversaries through coordinated industrial and regulatory power, and to make decisions in a crisis without waiting for US authorization at every operational threshold. It is a realistically achievable ambition and the one that current official EU doctrine, at its most serious, is converging upon.
Finally, mindset shift requires civic resilience as a hard-power enabler. Preparedness must not be treated exclusively as a matter of procurement and force structure. A Union whose citizens understand the nature of the threat, trust their governments to respond to it, maintain cognitive readiness for disruption, and are embedded in resilient societal structures is a Union that can sustain a deterrent posture credibly over time. Armaments without social depth are fragile instruments; Europe’s strategic revival depends on both.
Chapter 2: The single market and the economies of scale
The macro picture, three decades on
The most common claim about the European economy is that it has fallen behind. The most common evidence is GDP measured in current US dollars. Using that metric, the EU economy in 2008 was slightly larger than the US economy. By 2022, it was roughly a third smaller. Read literally, this implies a European miracle starting in 2000, the first full calendar year after the euro’s introduction, until 2008, when €1 strengthened from $0.92 to $1.47, followed by a European disaster from 2008 to 2022, when €1 fell to $1.05. However, neither happened. What did happen had to do with the dollar.
A more accurate comparison uses PPP, which corrects for exchange-rate fluctuations and the fact that domestic prices differ across economies. Measured by PPP, the EU and the United States have been declining in tandem as a share of global output—not because either economy is shrinking, but because Asia is growing at a faster rate.36Zsolt Darvas, The European Union’s Remarkable Growth Performance Relative to the United States, Bruegel, October 26, 2023, https://www.bruegel.org/analysis/european-unions-remarkable-growth-performance-relative-united-states. In 1995, the EU and the United States together produced roughly 43 percent of global GDP at PPP. According to the IMF World Economic Outlook, three decades later, China accounted for 19.6 percent, the United States 14.6 percent, and the EU 14.0 percent.37IMF, World Economic Outlook database, April 2026, https://www.imf.org/en/publications/weo/issues/2026/04/14/world-economic-outlook-april-2026. By 2025, the EU-US combined share had fallen to 28.6 percent. The decline is real but reflects a drop of relative weight in a world that has added 2.5 billion people to the middle-income bracket. It is not a reduction in European productive capacity.
In nominal terms, the picture is different again. In 2025, the EU generated approximately $21.2 trillion in GDP at current market prices (€19.3 trillion at the average annual exchange rate), against approximately $30.8 trillion for the United States and $19.6 trillion for China.38IMF, World Economic Outlook database, April 2026, https://www.imf.org/en/publications/weo/issues/2026/04/14/world-economic-outlook-april-2026. Based on these figures, the United States had a sizable lead, but that was partly a price effect (American goods and services cost more in dollar terms)39At the end of 2024, the US-EU27 price-level ratio was approximately 1.39 (OECD PPP program): A basket priced at $100 in the US cost roughly $72 in the EU. For Germany specifically, the gap was 28 percent (price level 0.72 vs. US 1.00). Source: OECD-Eurostat PPP programme, 2024 round. and partly a population effect (the US population has grown more rapidly than the EU’s).40US Census Bureau 2024 Population Estimates; Eurostat population statistics. The US population grew 8.6 percent 2010-2024 (from 309 million to 336 million); EU27 grew 2.1 percent (from 440 millions to 449 million).
The most informative metric is GDP per capita at PPP. Based on this measure, the EU has not fallen behind the United States over the past three decades; instead, it has held its position. In 1995—the first year for which a consistent EU27 series exists—EU per capita GDP at PPP was 71 percent of the US level. The ratio rose to 75 percent by 2022 and settled at 73 percent in 2025.41IMF, World Economic Outlook database, April 2026, https://www.imf.org/en/publications/weo/issues/2026/04/14/world-economic-outlook-april-2026. Over thirty years, the number has stayed in the 70–75 percent range compared to the world’s most productive large economy. The picture that emerges is not of a continent in decline but of one that has maintained structural stability even when measured against the world’s strongest benchmark. The convergence story is especially striking in the eastern member states, whose per capita income level rose from 32% of the US level in 1995 to 55 percent in 2022, and the IMF projects it will reach 60% by 2028.42Darvas, The European Union’s Remarkable Growth Performance. China’s catch-up has been even more dramatic in proportional terms, with per capital income rising from roughly 6 percent of the US level in 1995 to 30 percent in 2022 and 33 percent by 2025. However, China’s standard of living remains around a third of the United States,’43IMF WEO April 2026. China GDP per capita at PPP 2025 = $29,352; US = $89,991; ratio 32.6%. and the country faces the challenge of an aging population, a property-led growth model under visible structural strain, and high regional disparities.44United Nations Development Programme, Monitoring China’s Human Development, February 2026, https://www.undp.org/sites/g/files/zskgke326/files/2026-04/phdi_report_final.pdf.
A further refinement is gross national income (GNI), which measures not where output is produced but who earns the income. This distinction is crucial for economies like Ireland’s, where multinational profit-shifting inflates GDP relative to the income that actually accrues to citizens. At the EU27 level, however, GDP and GNI track closely. The per capita picture is similar: Both EU27 and US GNI per capita at PPP place their populations in the high-income bracket, with the EU at roughly three-quarters of the US level. China remains in the upper-middle-income bracket: According to the World Bank, GNI per capita reached $13,660 in current dollars in 2024,45World Bank GNI per capita, Atlas method, https://data.worldbank.org/indicator/NY.GNP.PCAP.CD. while the IMF estimated GDP per capita at $13,968 in 2025—both of which are close to, but still below, the World Bank’s high-income threshold of $14,005.
The implication is straightforward, and it runs counter to the prevailing narrative. The EU is not an economy in decline. It is a high-income economy comparable in scale to the United States, growing more slowly than emerging Asia (as every advanced economy is), keeping pace with the United States on per capita measures, and exceeding China on the metrics that matter for living standards. A point worth making: The European Union is a lifestyle empire in which the quality of life is the highest in the world.46Piotr Arak, Martyna Flis, and Krzysztof Kutwa, A Union of Nations 2.0: Ideas for EU Reform, Polish Economic Institute, August 2018, https://pie.net.pl/wp-content/uploads/2021/12/A_Union_of_Nations_2.0.pdf.
The world’s largest trading power
The first asset that Europe’s competitors consistently underestimate is its position in global trade. In 2024, EU27 exports of goods and services to non-member countries reached approximately $4.43 trillion—13.7 percent of global exports—compared to $3.75 trillion for China (11.6 percent) and $3.19 trillion for the United States (9.9 percent). Excluding exports between member states,47World Bank WDI for total exports; Eurostat for EU27 extra-EU goods and services exports 2024; WTO Statistical Review 2025. the European Union is the world’s largest exporter by a wide margin, ahead of China by roughly $670 billion and the United States by $1.2 trillion. Furthermore, the EU is the only major economy that maintains a trade surplus across both goods and services.
The composition of those surpluses is significant. The United States runs a trade surplus in services and a deficit in goods. China runs a goods surplus and a deficit in services. Europe runs surpluses in both—a balance that is intentional and reflects an economic model built on specialization and quality rather than volume in a few sectors. It also means that Europe is less exposed than either China or the United States to a trade shock concentrated in either goods or services. That matters in a world where trade is increasingly weaponized.
The structure of those exports reveals what kind of economy each is. The EU27 directs 82.4 percent of its extra-regional merchandise exports across the three manufactures categories that define an advanced industrial economy: chemicals and pharmaceuticals, machinery and transport equipment, and other manufactured goods. China’s manufactures share is higher at 93.7 percent, but far narrower in composition: machinery and transport equipment alone accounts for over 42 percent of total Chinese exports, concentrated in electronics, computers, and increasingly electric vehicles (EVs), batteries, and solar modules.48Andaman Partners, “Engine of Global Trade: The Rise and Global Impact of China’s Exports,” September 22, 2025, https://andamanpartners.com/2025/09/engine-of-global-trade-the-rise-and-global-impact-of-chinas-exports/. The United States sits at the other end of the spectrum at 68.8 percent—a gap explained largely by mineral fuels, which account for 16.5 percent of American merchandise exports49Own elaboration based on Eurostat (EU27 extra-EU goods exports by SITC, 2024, € converted at average 2024 USD/EUR = 1.0824); US Census, China Customs. and reflect the country’s emergence since 2014 as one of the world’s largest exporters of liquefied natural gas and a major oil exporter.
Three structural points follow:
First, the EU has the most diversified export base of the three economies. Chemicals and other manufactured goods each account for roughly a fifth of its exports, and machinery and transport equipment for just under 40 percent. China, by contrast, relies far more on a single category: machinery and transport equipment alone make up 42 percent of its exports, and together with miscellaneous manufactures they account for more than 60 percent. The EU enjoys greater economic resilience.50Ibidem A shock concentrated in one sector hits the EU less severely than it would hit China or the United States, in the case of a fuel-sector shock.
Second, the EU’s trade dominance is concentrated in sectors with high entry barriers, includ-ing pharmaceuticals, aerospace, specialized chemicals, and high-end machinery. These industries require decades of accumulated regulatory certification, specialized production knowledge, and capital-intensive development—capabilities that state-directed industrial policy cannot easily replicate on Beijing’s shorter timescales. Mario Draghi51Draghi, The Future of European Competitiveness. made the same point from the opposite perspective, noting that the EU’s productivity weakness is concentrated in emerging fields like digital and AI, not in its established industrial base, which remains globally competitive.52Ibidem Wunsch and Langenus53Pierre Wunsch and Geert Langenus, Eurosclerosis 2.0 in a Changing World: From Repetition to Rupture, National Bank of Belgium Policy Paper, April 2026, https://www.nbb.be/doc/ts/other/eurosclerosis_2_0.pdf. argue that Europe handles incremental progress relatively well across pharmaceuticals, chemicals, internal combustion engine cars, and aerospace—sectors where decades of accumulated capability cannot be quickly replicated—but is resistant to disruptive innovation, which tends to originate outside Europe.
Third, the structural mix shapes the political economy of trade defense. When the EU imposes restrictions on Chinese EVs, batteries, or solar modules, it is protecting sectors worth $1.1 trillion in extra-EU exports. In advanced-manufacturing terms, the EU has more to defend than either of its major competitors, a stark reminder of what is at stake in getting industrial and trade policy right.
The sectoral picture sharpens the point further. While the United States dominates frontier technologies and China excels in industrial mass production, Europe leads in luxury goods, processed agri-foods, and high-value manufacturing. European firms, including LVMH, Hermès, Kering, Richemont, Prada, and Ferrari, control roughly 70 percent of the global personal luxury goods market, which Bain & Company and Fondazione Altagamma valued at €363 billion in 2024. This dominance is anchored in heritage, geographical-indication protections, and a sense of cultural scarcity that no industrial policy can replicate.54Claudia D’Arpizio and Federica Levato, “Luxury Stumbles in 2024 but Can Still Return to Solid Growth,”Bain & Company, November 13, 2024, https://www.bain.com/insights/luxury-stumbles-in-2024-but-can-still-return-to-solid-growth-snap-chart/. The EU is the world’s largest agri-food exporter and the only top-five exporter to grow export value in 202555European Commission, Monitoring EU Agri-Food Trade Developments Until June 2026, https://webgate.ec.europa.eu/circabc-ewpp/d/d/workspace/SpacesStore/2ad06bcb-cd1d-4873-a7a5-d0d17dd299dc/download. with €2395 billion in extra-EU agri-food exports in 2025, led not by raw commodity volume but by branded and protected products such as wine, cheese, and processed meats. In the pharmaceutical sector, EU exports to non-EU countries reached €366 billion in 2025, generating a record trade surplus of €221 billion. This milestone was driven by a 16 percent year on year increase in exports, pushing the surplus to its highest level on record.56Eurostat, “Medicinal & Pharma Products: €221 Billion Trade Surplus,” April 13, 2026, https://ec.europa.eu/eurostat/web/products-eurostat-news/w/ddn-20260413-1. In commercial aerospace, Airbus delivered 793 aircraft in 2025 compared to Boeing’s 600. Boeing’s post-MAX recovery narrowed the gap, with Airbus’s share of combined deliveries falling to roughly 57 percent, down from above two-thirds in 2024. Airbus’s order backlog advantage remained intact at roughly 60/40 in 2026.57Airbus, Annual Press Conference 2026, February 19, 2026, https://www.airbus.com/en/newsroom/annual-press-conference-2026; Boeing, “Boeing Announces Fourth Quarter Deliveries,” January 13, 2026, https://investors.boeing.com/investors/news/press-release-details/2026/Boeing-Announces-Fourth-Quarter-Deliveries/default.aspx; backlog share calculated from Q1 2026 reporting, “Airbus vs Boeing Backlog in 2026: What the Numbers Actually Show,” The Flight Brief, 2026, https://www.theflightbrief.com/articles/airbus-boeing-aircraft-backlog-2026. In machinery, specialized chemicals, and precision manufacturing, European producers occupy positions that the United States cannot easily contest and China cannot rapidly replicate. Their position is anchored by the Mittelstand—Europe’s dense networks of specialized small and medium-sized enterprises—which remains a core structural strength, despite external commentary that persists in calling it a weakness.58David B. Audretsch and Erik E. Lehmann, The Seven Secrets of Germany: Economic Resilience in an Era of Global Turbulence (Oxford University Press, 2016).
Beneath these trade flows runs a quieter form of economic infrastructure: the legal and contractual architecture on which global commerce depends. Companies from the United States, China, and elsewhere settle their cross-border commercial disputes in London, Paris, Stockholm, Vienna, and Geneva. European contract law governs a disproportionate share of cross-border transactions. Financial services, engineering, digital solutions, logistics, legal arbitration, and tourism form the backbone of Europe’s “intangible economy.” The euro accounts for roughly 20 percent of global foreign exchange reserves, making it the world’s second reserve currency—a status no other currency has come close to challenging in two decades, despite serious effort by Beijing.59Adam S. Posen, “Why the Euro Will Not Rival the Dollar,” International Finance, 11, no. 1(May 2008): 75-100, https://www.piie.com/sites/default/files/publications/papers/posen1008.pdf; European Central Bank, International Role of the Euro, June 2024, https://www.ecb.europa.eu/pub/pdf/ire/ecb.ire202406~0b56ba4f71.en.pdf.
A more analytically powerful approach to comparative trade relies on economic complexity, a concept developed by Hausmann and Hidalgo. Tracked annually by Harvard’s Growth Lab, it shifts the focus to the diversity and sophistication of the productive capabilities embedded in a country’s exports. Unlike headline trade volumes, the Economic Complexity Index captures the “know how density” of an economy. Growth Lab research shows that this metric predicts long-run economic growth more reliably than traditional measures of governance, competitiveness, or human capital alone.60César A. Hidalgo and Ricardo Hausmann, “The Building Blocks of Economic Complexity,” Proceedings of the National Academy of Sciences, 106, no. 26 (June 2009): 10,570–75; Ricardo Hausmann et al., The Atlas of Economic Complexity: Mapping Paths to Prosperity (Cambridge, MA: MIT Press). Using this metric, Europe dominates the global top tier. Of the thirty most economically complex economies in the world, nineteen are EU27 member states61The Growth Lab at Harvard University, “Growth Projections and Complexity Rankings” Complexity Rankings & Growth Projections, Harvard Dataverse, 2026, https://doi.org/10.7910/DVN/XTAQMC.—meaning that 63 percent of the global top tier is European. Germany ranks sixth, followed within the top thirty by Czechia (7), Slovenia (9), Austria (11), Sweden (13), Ireland (14), Hungary (15), Finland (16), Slovakia (17), Italy (18), France (21), Romania (23), and Belgium (24). China ranks tenth and the United States twentieth.62The Growth Lab at Harvard University, “Growth Projections and Complexity Rankings” Complexity Rankings & Growth Projections. The implication is direct: While China is climbing the complexity ladder rapidly and the United States holds a stable middle position in the high-complexity tier, the European Union as a bloc occupies the most diversified high-complexity productive space in the global economy.63Japan is in first place, followed by Switzerland in second place. Adding Switzerland and the United Kingdom (twelfth place) to the EU means twenty-one of the thirty most economically complex economies are European or Europe-adjacent. The transatlantic and Pacific advanced democracies still hold the commanding heights of complex production.
Europe has also begun to deploy market access strategically. The 2023 anti-subsidy investigation into Chinese EVs, which produced provisional countervailing duties in 2024, was the first sustained application of EU trade defense to a strategic sector under active geopolitical competition. The framing matters. This is not traditional protectionism but rather the defense of an industrial base whose loss would be irreversible on any relevant timescale. Seeing Chinese EV expansion to the EU market probably more action is needed.
The capital markets gap
A balance sheet as strong as the EU’s should generate investment at scale. It does not. This failure is the most glaring vulnerability in Europe’s economic position, and one that should not be minimized.
The comparison is sharpest across two metrics. On savings, the EU structurally saves at a much higher rate than the United States—broadly matching the world average—but remains well below China. In 2025 (or newest data), gross domestic savings stood at 24 percent percent of GDP in the EU compared to 16.6 percent in the United States and 42.7 percent in China, with the world average at 26.4 percent.64World Bank, https://data.worldbank.org/indicator/NY.GNS.ICTR.ZS. Over three decades, the European savings rate has stayed in the 22–26 percent range; the US rate fell from above 20 percent in the late 1990s to 17 percent today; China’s rate climbed past 50 percent in the early 2010s before easing back to the low 40s. In absolute terms, the United States generated approximately $4.87 trillion in gross domestic savings in 2024, narrowly above the EU at $4.82 trillion and well behind China at $8 trillion. The EU and the United States together accounted for 33 percent of global savings; China alone accounted for 27 percent.
A balance sheet as strong as the EU’s should generate investment at scale. It does not…Europe is simultaneously the world’s largest capital exporter and an investment-constrained bloc.
On capital markets, the contrast is reversed. The market capitalization of listed domestic companies in the United States stood at 224 percent of GDP in 2025, compared to 79.5 percent in China. The EU aggregate is lower at 56 percent (estimated using the World Bank country data). EU household financial assets sit predominantly in bank deposits and domestic sovereign bonds, rather than in equity, venture capital, and growth-stage private capital. European venture capital deployment is roughly 0.3 percent of GDP per year, compared to approximately 0.7 percent in the United States.65Nathaniel G. Arnold, Guillaume Claveres, and Jan Frie, “Stepping Up Venture Capital to Finance Innovation in Europe,” working paper, International Monetary Fund, June 12, 2024, https://www.imf.org/-/media/files/publications/wp/2024/english/wpiea2024146-print-pdf.pdf. The structural consequence is well-documented: European deep tech firms, from quantum to advanced materials to AI infrastructure, increasingly raise late-stage rounds in the United States and list on US exchanges because European late-stage capital markets do not exist at the required scale.66Letta, Much More than a Market; Draghi, The Future of EU Competitiveness; Nicolas Véron, Breaking the Deadlock: A Single Supervisor to Unshackle Europe’s Capital Markets Union, Bruegel, June 26, 2025, https://www.bruegel.org/blueprint/breaking-deadlock-single-supervisor-unshackle-europes-capital-markets-union.
The picture, put simply, is that Europe saves more than the United States in relative terms but operates capital markets less than a third as deep. China is the inverse: It saves nearly twice as much as the EU as a share of GDP, yet hosts capital markets only marginally deeper. The United States has built the world’s most developed equity, venture, and growth-stage private capital markets on a savings base that is structurally thinner than either China or the EU. Europe is simultaneously the world’s largest capital exporter and an investment-constrained bloc—a paradox that means European savings finance American innovation while European companies built on European technology raise capital under American regulatory oversight, list on American exchanges, and gradually shift their decision-making to American jurisdictions. The Letta and Draghi reports of 2024 both made this point. The European Commission’s response—rebranding “capital markets union” as “savings and investments union”—captures the right diagnosis with not yet enough operational follow-through.67Jeromin Zettelmeyer, Draghi on a Shoestring: The European Commission’s Competitiveness Compass, Bruegel, February 3, 2025, https://www.bruegel.org/analysis/draghi-shoestring-european-commissions-competitiveness-compass.
Completing the capital markets union is therefore not a technocratic financial reform. It is a strategic activation decision. The estimated economic gain from full implementation runs to hundreds of billions of euros annually, channeling existing European savings into European productive investment at near-zero additional public cost. On the metrics that matter for European strategic autonomy, it is the highest-return institutional reform available to the bloc.
Recent IMF research68Luis Brandão-Marques et al., Deeper and More Integrated Financial Markets to Foster Growth and Resilience in Europe, IMF Staff Discussion Notes, 2026, no. 2 (June 10, 2026), https://doi.org/10.5089/9798229048330.006. puts a number on this. Reducing barriers to cross-border banking alone could raise EU GDP by approximately 2 percent in the long term, simply by allowing savings to flow more efficiently across borders and lowering funding costs for firms. Adding reforms to cross-border venture capital and pension-fund risk capital brings the estimated gain to nearly 3 percent; combined with business-dynamism reforms—improving the environment for startups, skills, and R&D—the long-term GDP gain could reach double digits. The IMF’s own illustration of the problem is telling: When the French AI company Mistral needed financing, the round was led not by a European venture fund but by ASML, a Dutch semiconductor equipment maker—a sign that even Europe’s own capital, when it moves at all, often bypasses the venture-capital channel entirely.
The EU current account ran a surplus of $413 billion in 2025 (1.9 percent of GDP) — down from a record €475.8 billion in 2024. China ran a surplus of $735.0 billion (3.8 percent of GDP); the United States ran a deficit of $1.12 trillion (-3.6 percent of GDP), narrower than 2024’s record $1.19 trillion (-4 percent of GDP)69Eurostat, “Balance of payments statistics,” Statistics Explained, https://ec.europa.eu/eurostat/statistics-explained/index.php?title=Balance_of_payments_statistics (EU current account balance, 2025); World Bank Group, World Development Indicators, series BN.CAB.XOKA.CD (current account balance, current US$) and BN.CAB.XOKA.GD.ZS (current account balance, % of GDP), https://data.worldbank.org/ (United States and China current account balance, 2025).
The stock measure tells the deeper story. The EU27’s net international investment position—the cumulative balance of foreign assets owned by residents compared to domestic assets owned by foreigners excluding intra-EU trade—reached nearly $652 billion at the end of 2025, up from the deficit position of -$1.3 trillion in 2020 and nearly −$2.7 trillion as recently as 2014.70Eurostat, “International investment position – quarterly and annual data (BPM6),” dataset bop_iip6_q__custom_22780473, https://ec.europa.eu/eurostat/databrowser/view/bop_iip6_q__custom_22780473/default/table, extracted 15/09/2026. Over the course of a decade, the EU27 has moved from substantial net debtor to a net creditor. Germany—at +$3.6 trillion in 2024 and +$4.3 trillion in 202571International Monetary Fund, International Investment Position dataset, series IIP_NETAL_P (net assets less liabilities), released May 2026, https://data.imf.org/Datasets/IIP.—is now the largest single-country net creditor in the world, ahead of China at +$3.2 trillion 2024 (+$4.1 trillion in 2025), Japan at +$3.4 trillion in 2024 (+$3.7 trillion in 2025), and Norway at +$1.7 trillion in 2024 (+$2.1 trillion in 2025). The EU’s creditor position is concentrated in Germany and the Netherlands.72All data from IMF International Investment Position database, May 2026 release; World Bank current account series.
The United States is following the opposite trajectory. US net external liabilities reached −$26.5 trillion at the end of 2024 and −$27.5 trillion in 2025, up from −$14.7 trillion in 2020 and −$7.6 trillion in 2015. US net external debt has more than tripled in a decade. The United Kingdom, often grouped with the United States in financial-markets analyses, has held its net position close to balance across this period (−$216 billion in 2024, −$269 billion in 2025), confirming that the deterioration is specifically American rather than Anglo-Saxon.73All data from IMF International Investment Position database, April May 2026 release; World Bank current account series.
The problem of the macroeconomic imbalance is concentrated in Germany: its individual net creditor position rivals China’s and exceeds Japan’s, and it has held that position for years. China sits structurally on the same side of the balance sheet as Germany, with a creditor position that grew by roughly $900 billion in 2025 alone—the opposite direction from the EU’s. The United States is the largest net debtor in history, and its position is widening, not narrowing.
Europe finances much of the rest of the world’s investment—and a sizable share of the US deficit—out of its own surplus. The capital that funds American innovation, late-stage venture, and growth-stage private equity flows partly from European savings, channeled through American capital markets. This is the missing piece of the capital markets gap diagnosis: The EU is effectively exporting its savings advantage because its financial infrastructure cannot absorb it.
A balance sheet is not a strategy. Europe’s $652 billion net international investment position (NIIP) is composed overwhelmingly of private-sector claims, including pension-fund portfolios, corporate foreign direct investment (FDI), and bank lending, that cannot be directed by government fiat toward strategic objectives. NextGenerationEU took thirteen months from political agreement to first disbursement. ReArm Europe’s €800 billion envelope has no binding disbursement schedule. The CHIPS Act’s €43 billion headline mobilizes approximately €3.3 billion in direct EU expenditure; the rest is national subsidy and private co-investment whose durability depends on future political cycles. The United States has the Defense Production Act; China can redirect industrial capacity by administrative order; the EU has no standing framework for industrial surge mobilization. The distinction between owning assets and deploying them is the financial dimension of the conversion problem.
Three innovations would help the EU bridge this gap without treaty changes: a permanent, equity-taking strategic investment vehicle modeled on Norway’s sovereign wealth fund; a rapid-disbursement mechanism for ReArm Europe that pre-approves procurement frameworks and releases capital against production milestones; and a European industrial mobilization authority, activable by qualified majority and empowered to prioritize supply-chain allocations during declared crises. The balance-sheet advantage is real. The transmission mechanism from balance sheet to strategic action is not.
Common fiscal capacity and the euro
Government debt tells the same story from a different angle. In 2025, the IMF projected US general government gross debt at 123.9 percent of GDP, against 82.5 percent for the EU2774The Euro Area figure is 87.1%. EU27 is lower because the eight non-EA member states (notably Sweden, Denmark, Poland, Czechia) have lower debt-to-GDP ratios. and 99.2 percent for China.75International Monetary Fund, “General Government Gross Debt, Percent of GDP,” World Economic Outlook, April 2026, https://data.imf.org/en/datasets/IMF.RES:WEO. Within the EU, dispersion remains substantial: Estonia at 24.2 percent, the Netherlands at 43.3 percent, Germany at 62.9 percent, Spain just above 100 percent, France at 116.0 percent, Italy at 137.1 percent, and Greece at the top at 145.7 percent, down sharply from 209.9 percent in 2020.76Greek debt-to-GDP trajectory: 2020=209.9 percent, 2024=155.4 percent, 2025=145.7 percent. By 2030, projected to be 115.5 percent. The Greek convergence is itself a powerful example of what the EU’s fiscal framework can deliver under sustained pressure. By 2030, the IMF projects that Greek debt will be 115.5 percent of GDP, a 94-percentage-point reduction in a decade, achieved without leaving the bloc or the euro.
China’s debt position requires a longer treatment because the official figure understates the structural reality. Officially, general government debt—combining central and local liabilities—was roughly 89 percent of GDP in 2024, according to the IMF, up from 70 percent in 2020 and projected at the time to reach 110 percent by 2029.77Piotr Arak, letter to the editor, Financial Times, October 25, 2024, https://www.ft.com/content/d432b3e8-68fd-4f0b-93a5-591837533d7f. On paper, that looked broadly comparable to advanced economies, even relatively manageable for a country that had relied as heavily on investment to fuel growth as China has. The IMF projections, from April 2026, have revised the trajectory upward and accelerated it: Official Chinese gross government debt is now at 99.2 percent of GDP in 2025 and projected to reach 120.3 percent by 2029 and 123.8 percent by 2030—already 10 percentage points higher than the October 2024 figures. The deterioration has been faster than the IMF expected—and the trajectory is steepening, not flattening.
But the headline figure is not the full picture. For two decades, Chinese officials have relied on local government financing vehicles (LGFV) to fund the country’s infrastructure buildout while keeping the liabilities off the government balance sheet. The hidden debt accumulated through those vehicles was estimated at nearly 55 percent of GDP by the end of 2024,78International Monetary Fund, People’s Republic of China: 2024 Article IV Consultation—Press Release; Staff Report; and Statement by the Executive Director for the People’s Republic of China, IMF Country Report No. 24/258, August 2024, https://www.imf.org/en/Publications/CR/Issues/2024/08/02/Peoples-Republic-of-China-2024-Article-IV-Consultation-Press-Release-Staff-Report-and-554090. with augmented debt—official plus LGFV-linked—projected to reach almost 150 percent of GDP by 2029. Add corporate debt, particularly from state-owned enterprises whose obligations are de facto sovereign, and the country carries another 120 percent of GDP in liabilities.
By comparison, the EU’s 82.5 percent of GDP—issued in deep, transparent capital markets, denominated in the world’s second reserve currency, and constrained by treaty rules whose binding force has been demonstrated repeatedly—appears less as a weakness and more as the most credible aggregate fiscal position among the major blocs. In absolute terms, the gap is wide. In 2025, US general government debt reached approximately $38.1 trillion, China’s official number was $19.5 trillion (with augmented debt running well above), and the EU27’s was $17.5 trillion. By 2030, the IMF projects that US debt will be 138.9 percent of GDP—adding roughly $13 trillion of additional gross issuance—compared to the EU’s essentially flat trajectory of 85.5 percent. China’s debt is projected to add another 25 percentage points of GDP in liabilities over the same five years. China’s government debt has expanded by roughly 17 percent per year since 2008, US debt by 7.7 percent, and EU debt by roughly 3 percent. Europe’s number is partly a reflection of weaker nominal European growth, but it is also the result of far tighter fiscal constraints adopted after the 2010–12 sovereign debt crisis.
Viewed together, the three balance sheets tell a story that the GDP comparison hides. Europe has more fiscal space than the United States and more transparent fiscal space than China. It has the world’s largest private savings pool, the world’s largest single-bloc net external creditor position, and the most conservative aggregate fiscal stance of any major bloc. The constraint on European deployment of these assets is institutional, not financial.
The institutional ceiling on common European fiscal capacity has already shifted further than most external observers appreciate. NextGenerationEU, the recovery instrument adopted in 2020 with a headline envelope of €800 billion (roughly $870 billion), introduced what two decades of Maastricht-era debate had treated as politically impossible: common debt issued at bloc level, with proceeds disbursed both as grants and loans and debt service backed by the EU budget and member-state guarantees. ReArm Europe,79ReArm Europe’s headline €800 billion envelope comprises €150 billion from the EU-backed SAFE instrument and €650 billion from relaxed Stability and Growth Pact rules permitting greater member-state defense spending under the national escape clause. The composition matters: SAFE is bloc-level common debt; the remainder is national fiscal space, not common capacity. the defense-industrial envelope adopted in 2025 at the same headline scale, applies the same logic in a different policy domain. The question is no longer whether Europe can mobilize common fiscal capacity at scale. The question is at what pace and for which purposes it chooses to do so.80Guntram Wolff, Armin Steinbach, and Jeromin Zettelmeyer, Accelerating European Rearmament, April 2025, Bruegel, https://www.bruegel.org/sites/default/files/2025-04/PB%2015%202025_3.pdf.
The euro is the deepest piece of this architecture. The world’s second reserve currency, with approximately 20 percent of global foreign exchange reserves and a comparable share of cross-border debt issuance denominated in euros, it gives Europe a coercive infrastructure that no bloc save the United States possesses. The 2022 freeze of approximately €260 billion in Russian central bank assets held in euro-area institutions—and their subsequent immobilization—demonstrated the operational reach of euro-denominated financial sanctions. The euro is not yet a peer to the dollar; its role in trade settlement, official reserves, and global liquidity provision remains roughly half the dollar’s. But it is the only credible second pole in the global monetary system. Beijing has spent two decades trying, unsuccessfully, to replicate that status with the renminbi.81Posen, “Why the Euro Will Not Rival the Dollar”; European Central Bank, The International Role of the Euro.
The single market
In nominal GDP terms, the EU roughly matches China and trails the United States—a comparison that understates the importance of Europe’s single market, the largest and most deeply integrated economic space in the world. The free movement of goods, services, capital, and people across twenty-seven countries adds an estimated 9 percent to EU GDP every year.82European Commission, The Single Market: Estimates of Integration Benefits, 2024. The 1988 Cecchini Report, the original quantification exercise that informed the Single European Act, projected gains of 5–6.5 percent of GDP from market integration. By 1993, EU studies were estimating 2.5 million jobs created and significant productivity gains from the first wave of integration.83Paolo Cecchini, Michel Catinat, and Alexis Jacquemin, The European Challenge–1992: The Benefits of a Single Market, https://aei.pitt.edu/99590/; Zsolt Pataki, The Cost of Non-Europe in the Single Market, September 2014, https://www.europarl.europa.eu/RegData/etudes/STUD/2014/510981/EPRS_STU(2014)510981_REV1_EN.pdf.
The single market in goods is largely complete. The single market in services, capital, energy, and digital is not, and the IMF’s 2024 report84International Monetary Fund, Regional Economic Outlook: A Recovery Short of Europe’s Full Potential, October 2024, https://www.imf.org/-/media/files/publications/reo/eur/2024/october/english/text.pdf; Alfred Kammer, “Scaling Up the Single Market to Boost Productivity” (speech, House of the Euro, Brussels, November 14, 2024), https://www.imf.org/en/news/articles/2024/11/18/sp111424-scaling-up-the-single-market-to-boost-productivity; Oyun Erdene Adilbish et al., Europe’s Productivity Weakness: Firm-Level Roots and Remedies (working paper, International Monetary Fund, February 14, 2025), https://www.imf.org/en/publications/wp/issues/2025/02/14/europes-productivity-weakness-firm-level-roots-and-remedies-561771. puts numbers on the gap that are genuinely arresting. The report estimates that remaining intra-EU barriers are equivalent on average to a 44 percent tariff on goods and a 110 percent tariff on services—three times higher than barriers between US states for goods, and higher than the most aggressive tariffs imposed on adversarial trading partners. Lowering intra-EU trade barriers to US interstate levels could raise EU productivity by nearly 7 percentage points over the long term, halving the productivity gap with the United States.85Keith Head and Thierry Mayer, “The United States of Europe: A Gravity Model Evaluation of the Four Freedoms,” Journal of Economic Perspectives 35, no. 2 (Spring 2021): 23–48, https://www.aeaweb.org/articles?id=10.1257/jep.35.2.23. The European Central Bank’s analysis,86Roberto Bernasconi, Naïm Cordemans, Vanessa Gunnella, Giacomo Pongetti, and Lucia Quaglietti, “What is the Untapped Potential of the EU Single Market?,” Economic Bulletin Articles, European Central Bank, vol. 8, 2025, https://www.ecb.europa.eu/press/economic-bulletin/articles/2026/html/ecb.ebart202508_01~2e71d52829.en.html. broadly corroborates the IMF estimate while offering a tighter range for services depending on elasticity assumptions, finding tariff-equivalent trade costs of around 78–115 percent on services and confirming that only half of the potential benefits from EU membership have been realized to date.
These figures should be interpreted with care. Some scientists have argued that the IMF’s research overstates the tariff equivalent because it treats genuine consumer preferences for local products (wine, regional foods, identity goods) as if they were policy barriers.87Keith Head and Thierry Mayer, “No, the EU Does Not Impose a 45% Tariff on Itself,” VoxEU/CEPR, November 13, 2025, https://cepr.org/voxeu/columns/no-eu-does-not-impose-45-tariff-itself. That critique has force in specific sectors, particularly food, textiles, and culturally embedded goods. It does not, however, displace the central finding: Even on the more conservative academic estimates—intra-EU goods trade costs at 8–13 percent in tariff-equivalent terms,88Head and Mayer, “The United States of Europe: A Gravity Model Evaluation of the Four Freedoms.” services costs in the euro area closer to 60 percent89Nathaniel G. Arnold et al., Lifting Binding Constraints on Growth in Europe: Actionable Priorities to Deepen the Single Market, IMF Working Paper WP/25/113, June 2025, https://www.imf.org/en/Publications/WP/Issues/2025/06/13/Lifting-Binding-Constraints-on-Growth-in-Europe-Actionable-Priorities-to-Deepen-the-Single-567610.—the EU is meaningfully less integrated than the United States, and the services gap is structural rather than methodological.
The headline estimate of the gain from completion, drawn from European Commission and IMF analysis converging on a similar range, is that completion of the services market—financial services, professional services, digital services, and healthcare—would add €1.8–€2.1 trillion (roughly $1.95–$2.30 trillion) to EU GDP, the equivalent of adding an economy about the size of Spain to the bloc’s productive output.90Estimates provided by the authors. If anything, the estimate is conservative: It does not fully price in the second-order effects of capital and energy market integration on productivity in tradable sectors. The IMF puts a cleaner number on the related cross-cutting reform: Labor movement across EU member states is currently estimated at eight times more costly than mobility between US states, choking the ability of European firms to scale.91Letta, Much More Than a Market.
The non-tariff barriers underpinning these costs are not abstract. A construction company finds that its building materials, while EU-compliant, still need costly national checks. A foreign university seeking to establish a campus faces major delays in getting staff qualifications recognized. A homecare provider expanding into another member state navigates a separate national licensing regime. Mutual recognition—the founding principle of the single market established in 1979 by the Court of Justice in Cassis de Dijon—fails in practice across most service sectors92Piotr Semeniuk, Economic Protectionism in the European Union (Warsaw: Polish Economic Institute, 2019), https://pie.net.pl/wp-content/uploads/2019/01/Raport-Protekcjonizm-_EN-red.pdf. and several goods categories, because national regulators routinely require additional national-level verification of EU-compliant products and services.93Luis Garicano, “The Myth of the Single Market,” Silicon Continent, May 14, 2025, https://www.siliconcontinent.com/p/the-myth-of-the-single-market.
A paradox sits at the center of the regulation debate that political commentary consistently misreads. Reducing regulatory burden on European businesses requires more EU-level regulation, not less. The dominant compliance cost facing European firms is not the volume of EU rules; it is divergence in how twenty-seven member states transpose, interpret, and enforce them. Twenty-seven national implementations of a single directive, each with its own administrative practice and case law, is not deregulation. It is fragmentation. The “twenty-eighth regime” idea proposed by Letta—a single, optional EU-wide regulatory framework that companies can opt into, replacing twenty-seven national regimes—is the cleanest available remedy. EU-Inc proposed by the European Commission is the first step to resolving this issue.
The strategic implication is significant: Market access is Europe’s primary coercive instrument, and the single market is what makes that instrument credible. Russia after February 2022 demonstrated empirically what exclusion does to an economically integrated state: It compounds faster than military attrition. Every third-country actor—India, the Gulf states, ASEAN, the Mercosur bloc, and most of Africa—faces a structural question about which advanced market it cannot afford to lose access to. For most of Eurasia, large parts of Latin America, and significant parts of Africa, the answer is the European single market. That non-negotiability is leverage. Completing the market deepens it.
Human capital
The final element of Europe’s comparative economic balance sheet is human capital, and here the European advantage is again systematically underweighted in commentary that fixates on top-decile institutions.
The most striking measure is institutional breadth. In the 2026 Times Higher Education World University Rankings, 120 EU27 universities were included the global top 500, compared to 102 from the United States, forty-nine from the United Kingdom, and thirty-five from mainland China. Of the 2,191 globally ranked institutions, 495 are based in EU27 member states—more than the United States (171), the United Kingdom (109), and mainland China (97) combined.94Times Higher Education, World University Rankings 2026, https://www.timeshighereducation.com/world-university-rankings/2026/world-ranking. Counts include all currently active EU27 member state universities. This is the structural fact that the “America has Harvard, MIT, and Stanford” framing obscures. The United States may be home to a number of powerhouse research institutions, but the EU produces more high-quality research universities across more countries than any other bloc. China is rapidly upgrading a small number of its elite universities through targeted state investment—Tsinghua, for example, is ranked twelfth globally95Times Higher Education, World University Rankings 2026.—but the country has only thirty-five institutions in the top five hundred.
Within the EU27, leadership is concentrated in the four largest research nations but is not exclusive to them. Germany has twenty-five universities in the global top 500, led by the Technical University of Munich at twenty-seventh place and LMU Munich at thirty-fourth. The Netherlands places twelve of its thirteen ranked universities in the top 500, the highest concentration of high-quality research provision per capita in the world, anchored by Delft University of Technology (fifty-seventh) and the University of Amsterdam (sixty-second). France contributes ten to the top 500, led by Paris Sciences et Lettres (forty-eighth) and Université Paris-Saclay (sixty-eighth). Italy adds 7, led by Bologna and Sapienza. Belgium punches above its weight with 6, led by KU Leuven (forty-sixth) and Ghent (115th); Sweden has 5, including the Karolinska Institute (fifty-third); Spain, Ireland, Austria, Denmark, Finland, and Poland round out the top-tier contributors. Central and Eastern Europe, especially Czechia, Romania, and Poland, contributes a deep pool of ranked institutions that fall just below the top 500 but produce graduates for a continent-wide labor pool through free movement.
The graduate flow tracks the institutional picture. In 2023, the EU27 produced approximate-ly 4.4 million tertiary graduates, broadly comparable to the United States in absolute terms and concentrated in engineering, life sciences, economics, law, and medicine—fields that support advanced manufacturing, regulatory infrastructure, and high-end services.96Oyun Erdene Adilbish et al., “Europe’s Productivity Weakness: Firm-Level Roots and Remedies,” IMF Working Paper No. 25/40, International Monetary Fund, February 2025, https://www.imf.org/en/Publications/WP/Issues/2025/02/14/Europe-s-Productivity-Weakness-Firm-Level-Roots-and-Remedies-561771. The asymmetry between the EU and the United States is not in graduate volume but in research-system geography. While US high-skill labor is concentrated in a handful of metropolitan areas (Boston, the Bay Area, New York, Seattle, North Carolina’s Research Triangle), the EU’s high-skill labor is distributed across Amsterdam, Barcelona, Brussels, Copenhagen, Dublin, Helsinki, Milan, Munich, Paris, Stockholm, Vienna, Warsaw, and many others. Distribution is resilience. A geographic concentration of human capital becomes a vulnerability when a region faces a housing, policy, or fiscal shock; distribution buffers against it.
Erasmus+, the EU’s flagship student-and-staff mobility program, with €26.2 billion ($28.3 billion) committed for 2021–27 and approximately ten million participants over its lifetime, has built human-capital networks across the bloc in ways no other major economy can match. The Draghi report proposed a fivefold increase in Erasmus+ funding precisely because the cross-border mobility it generates is the most direct mechanism for converting the EU’s distributed human capital into a continent-wide labor pool. A French engineer who studied in Munich and works in Stockholm is a unit of European labor-market integration that no national policy could produce.
Europe’s human-capital advantage is not concentrated in a handful of superstar institutions vulnerable to political or funding shocks. It is distributed, mobile within the bloc, and reinforced by free movement and shared research programs. Europe’s university network is a quiet but critical pillar of its long-term economic power. It is precisely the kind of human-capital advantage that compounds under sustained pressure, which is precisely the condition Cold War 2.0 will impose. The 2025 changes to US visa policy, federal research funding, and university governance have already prompted measurable flows of researchers from American to European institutions; if current US policy holds, that movement will accelerate through 2026.
The preceding human-capital analysis describes the quality of the labor force without addressing its quantity. The EU27 working-age population peaked at approximately 307 million in 2009 and is projects by Eurostat to fall to 265 million by 2050—a loss roughly equivalent to Spain’s entire working-age population. The old-age dependency ratio, which measures how many retirees exist for every hundred working-age adults, is projected to rise from 36 to 56 between 2023 and 2050. This demographic cuts across every major finding in this report. The savings rate will decline as retirees draw down their accumulated savings faster than workers add to theirs. The fiscal headroom at 82.5 percent of GDP will face structural upward pressure from age-related spending that the European Commission’s 2024 Ageing Report projects will add a further 2.0 percentage points of GDP by 2050.97European Commission, Directorate-General for Economic and Financial Affairs, 2024 Ageing Report: Economic and Budgetary Projections for the EU Member States (2022–2070), Institutional Paper 279, April 2024, https://economy-finance.ec.europa.eu/publications/2024-ageing-report-economic-and-budgetary-projections-eu-member-states-2022-2070_en?prefLang=pl. That pressure will be paired with another labor-market challenge. The consulting company Kearney98Michael Kahn, Christoph Steitz, and Dominique Patton, “Europe’s Defence Companies Scramble for Workers as Business Booms,” Reuters, May 27, 2025, https://www.reuters.com/business/aerospace-defense/europes-defence-companies-scramble-workers-business-booms-2025-05-27/. estimates that EU defense will need 760,000 additional workers by 2030—demand that must be met by a labor market already at record tightness, with unemployment running at just 5.9 percent in early 2026. At that level of constraint, hiring is largely a zero-sum exercise: Every engineer hired by Rheinmetall is an engineer no longer available to Siemens or the Mittelstand. Eurostat estimates that stabilizing the working-age population requires annual net immigration of 1.5 million to 2.0 million people. Current net migration approaches that range but is poorly distributed, inadequately integrated, and politically contested. An immigration strategy tied to labor demand is not a social-policy nicety—it is a precondition for every economic and industrial scenario in this report. The case for moving simultaneously across defense, industrial policy, and fiscal consolidation is not only geopolitical. Demographics make it equally urgent.
Chapter 3: Geography, corridors, and enlargement
Geography as strategy
The central claim of this chapter is deceptively simple: Geography is no longer background context for European grand strategy. It is the medium through which power is exercised, contested, and secured. The EU’s strategic decisions—about enlargement, corridor access, and energy and infrastructure investment, and where it deploys financial and political leverage—are inseparable from the geographic logic within which they operate. To view geography as a neutral stage upon which policy is performed is to misunderstand the nature of the strategic competition Europe now confronts. Russia’s war against Ukraine is not only a normative challenge to the European order. It is also a contest over the physical and political geography of the continent, over which states orbit Moscow’s sphere of coercion and which are anchored to the EU’s legal and economic space.99Ian Bond, Contested Space: Eastern Europe between Russia and the EU, Centre for European Reform, March 2017, https://www.cer.eu/publications/archive/policy-brief/2017/contested-space-russian-and-eu-relations-eastern-europe.
This geographic dimension of European strategy has been present since the integration project was founded. What has changed since 2022, accelerating further in 2024 and 2025, is its official recognition at the highest levels of EU institutional authority. The European Council’s 2024 to 2029 Strategic Agenda100European Council, Strategic Agenda 2024–2029. describes enlargement explicitly as a geostrategic investment in peace, security, stability, and prosperity—a formulation that would have been considered excessively political at any earlier moment in the Union’s enlargement history. The European Parliament’s March 2026 report on enlargement101European Parliament, Report on the EU Enlargement Strategy (Brussels: European Parliament, Published May 2, 2026), https://www.europarl.europa.eu/doceo/document/A-10-2026-0016_EN.html. states plainly that the cost of non-enlargement is the creation of gray zones vulnerable to malign external influence. The May 2025 EU Black Sea strategic approach102Delegation of the European Union to Ukraine, “New EU Strategy for Secure, Prosperous and Resilient Black Sea Region,” May 30, 2025, https://www.eeas.europa.eu/delegations/ukraine/new-eu-strategy-secure-prosperous-and-resilient-black-sea-region_en. frames the region as a connectivity corridor linking Europe to the South Caucasus and Central Asia, explicitly aligning it with the enlargement process, a framing reinforced in June 2026 by the launch of the EU Connectivity Agenda Platform operationalizing precisely those corridor links. Taken together, these documents represent a conceptual revolution in how Brussels officially understands the relationship between territory, integration, and power.
Enlargement as the EU’s most distinctive strategic instrument
This chapter argues that enlargement is the European Union’s most legitimate, most scalable, and most structurally distinctive instrument for producing secure political space in its neighborhood. No other actor in Europe’s vicinity possesses an equivalent mechanism. Russia’s model, based on coercion, bribery, frozen conflict, and energy dependency, produces compliance, not stability, and corrodes the political foundations on which it relies. China’s model, rooted in infrastructure finance and market access conditioned on political alignment, generates economic dependency without institutional anchoring and leaves governance structures largely unreformed. The United States offers security guarantees and market access, but its domestic political volatility since 2016 has demonstrated that US strategic commitment is neither unconditional nor automatic.103Matteo Bonomi, Luisa Chiodi, Luca Cinciripini and Pietro Sala, “Preparing for Enlargement: Contributions of the EU and the Western Balkans,” Istituto Affari Internazionali, July 9, 2024, https://www.iai.it/sites/default/files/iai2409.pdf.
The EU’s enlargement toolkit operates differently and, when deployed with strategic seriousness, more durably. Conditional integration—the offer of market access, regulatory convergence, institutional reform support, financial instruments, and ultimately full membership in exchange for governance transformation, rule of law reform, and alignment with European norms—produces the kind of deep structural anchoring that military presence alone cannot achieve. A state that has internalized the Union’s legal order, integrated its economy into the single market, and embedded its institutions in European regulatory networks is a state that has functionally shifted the center of gravity of its political economy away from external coercive actors and toward European frameworks.104Frank Schimmelfennig and Ulrich Sedelmeier, “Governance by Conditionality: EU Rule Transfer to the Candidate Countries of Central and Eastern Europe,” Journal of European Public Policy 11, no. 4 (2004): 661–79, https://doi.org/10.1080/1350176042000248089. At its best, that is what enlargement accomplishes—not merely accession management but order-building. The strategic innovation of the current enlargement cycle—the one that distinguishes 2024–26 from all previous rounds—is the operationalization of staged integration as a bridge between geopolitical urgency and procedural conditionality.105Ivan Nagornyak and Mariia Shalamberidze, “How Staged Integration Can Revitalise EU Enlargement,” The Loop, July 8, 2025, https://theloop.ecpr.eu/how-staged-integration-can-revitalise-eu-enlargement/. The dilemma that haunted European enlargement policy starting in 2022 was real: There was a compelling security case for rapidly incorporating Ukraine, Moldova, and the Western Balkans, but the procedural and governance standards required for full membership could not be waived without eroding the credibility of the entire accession system.106Michael Emerson, Milena Lazarević, Steven Blockmans, and Strahinja Subotić, “A Template for Staged Accession to the EU,” Centre for European Policy Studies, October 1, 2021, https://www.ceps.eu/ceps-publications/a-template-for-staged-accession-to-the-eu/. Staged integration resolves this dilemma instrumentally. It allows the EU to deepen functional incorporation—through growth plans, sectoral single-market access, infrastructure connection, sanctions alignment, military mobility, and financial reform instruments—well before formal membership milestones are reached. Moldova’s €1.9 billion Reform and Growth Facility,107Council of the EU, “Moldova: Council Gives Final Green Light to Support Reforms and Economic Growth with €1.9 Billion,” press release, March 18, 2025, https://www.consilium.europa.eu/en/press/press-releases/2025/03/18/moldova-council-gives-final-green-light-to-support-reforms-and-economic-growth-with-almost-2-billion/. approved by the European Council in March 2025, is the clearest operational example. It uses financial and reform conditionality to anchor Chișinău in European institutional frameworks not as a substitute for accession but as its practical antechamber.108Engjellushe Morina, “Accelerate the Accessions: Why Faster Is Better in EU Enlargement Policy,” European Council on Foreign Relations, December 18, 2025, https://ecfr.eu/publication/accelerate-the-accessions-why-faster-is-better-in-eu-enlargement-policy/. Meanwhile, at the EU-Western Balkans Summit in Tivat, leaders reaffirmed that EU enlargement is a strategic investment and signaled new efforts to streamline the process for top candidate nations.109European Commission, “Ukraine–Enlargement and Eastern Neighbourhood: Ukraine Opens First Negotiating Cluster,” June 15, 2026, https://enlargement.ec.europa.eu/countries/ukraine_en; António Costa, “Remarks by President António Costa at the EU-Western Balkans Summit,” Tivat, Montenegro, June 5, 2026, https://ieu-monitoring.com/editorial/eu-and-western-balkans-push-enlargement-forward-as-brussels-eyes-faster-accession-path/1242805; Milan Nič et al., Europe’s Next Enlargement, German Council on Foreign Relations, March 18, 2026, https://dgap.org/en/research/publications/europes-next-enlargement. Even Ukraine formally opened its first negotiating cluster, the fundamentals chapter, marking the first substantive milestone in accession negotiations during active wartime.
The new urgency surrounding enlargement has not dissolved the structural tensions that have constrained every previous round. Internal EU reform—the institutional prerequisite for absorbing a Union of thirty or more member states—remains stalled, with disagreements over the qualified majority voting, budgetary rebalancing, and agricultural policy unreformed precisely because the political costs of addressing them fall on current member states rather than candidates. France and the Netherlands retain deep reservations about the pace and sequencing of accession, particularly where it intersects with cohesion fund redistribution and labor-market access. Member states continue to instrumentalize enlargement processes for transactional ends. And the merit-based conditionality architecture faces a genuine and as yet unresolved tension: The faster the process moves for geopolitical reasons, the harder it becomes to maintain the governance standards that justify it. As noted in April 2026,110Barbara Lippert, Nicolai von Ondarza, and Frauke M. Seebass, EU Enlargement: Ukraine as a Special Case, the Western Balkans as the Norm, April 20, 2026, https://doi.org/10.18449/2026C17. none of the current official candidates fully meets the fundamentals of rule of law, democracy, and fundamental rights, an additional burden that the EU has not yet found a principled way to manage without compromising its standards or stalling its strategic and geopolitical ambition. Staged integration is the most serious attempt yet to square that circle. Whether it succeeds, or whether it simply defers the contradiction to a later and more costly moment, remains an open question, and the answer will depend in no small part on whether three structural vulnerabilities that have constrained every previous enlargement round can be addressed with greater seriousness than before.
A differentiated map of enlargement progress
The current enlargement landscape is best understood as a differentiated strategic map rather than a uniform queue of candidate countries advancing in sync toward a common destination.111European Commission, “2025 Enlargement Package Shows Progress Towards EU Membership for Key Enlargement Partners,” November 4, 2025, https://enlargement.ec.europa.eu/news/2025-enlargement-package-shows-progress-towards-eu-membership-key-enlargement-partners-2025-11-04_en. That differentiation is not a weakness of the EU’s enlargement architecture but rather a strength if it is effectively managed. It allows Europe to reward progress, maintain leverage over laggards, and respond to geopolitical urgency without collapsing the conditionality standards that give the entire process its credibility.
Ukraine represents the most consequential and the most institutionally remarkable case. Accession negotiations were formally started on June 25, 2024.112Council of the European Union, “First Intergovernmental Conference at Ministerial Level with Ukraine,” June 25, 2024, https://www.consilium.europa.eu/en/meetings/international-ministerial-meetings/2024/06/25/ukraine/. Ukraine completed the European Commission screening process by September 30, 2025—a pace of advancement without precedent in the history of EU enlargement that reflects the genuine seriousness of Ukrainian institutional effort during wartime and the EU’s recognition that integrating a nation of almost forty million people engaged in the largest land war in Europe since 1945 is strategically indispensable. The 2025 enlargement package made major advances, particularly with respect to rule of law, anti-corruption frameworks, and judicial independence, domains where progress is typically slowest.113European Commission, “2025 Enlargement Package”; European Commission, Ukraine Report 2025, November 4, 2025, https://enlargement.ec.europa.eu/ukraine-report-2025_en. Even so, Ukraine’s trajectory has faced obstacles: Implementation gaps remain substantial, the reconstruction finance architecture is still being assembled, and the political-economic dimensions of eventual full membership raise unresolved questions about agricultural policy, structural funds, and voting weight within EU institutions. But the strategic direction is clear, and the Union is committed to the integration in terms that would be exceedingly difficult to reverse.
Moldova offers a complementary and instructive model: integration through resilience-building rather than formal accession benchmarks. The country is smaller, institutionally more fragile, and geographically more exposed than Ukraine. Its accession path will be slower. But the EU’s approach—combining reform finance, political signaling, market access, and security partnership—shows that staged integration can serve as genuine statecraft even when full membership remains distant.114European External Action Service, “EU-Moldova Summit in Brussels Marks a New Milestone on Path to EU Membership,” June 22, 2026, https://www.eeas.europa.eu/delegations/moldova/eu-moldova-summit-brussels-marks-new-milestone-path-eu-membership_en. The effect is to reduce Moldova’s vulnerability to Russian coercive leverage incrementally and without waiting for a formal accession conference. It is precisely the kind of geographically calibrated, instrumentally flexible approach that a middle-power strategy at continental scale requires.
Georgia represents the indispensable negative case. The European Commission’s 2025 enlargement package115European Commission, “2025 Enlargement Package.” described Georgia as a candidate country in name only, following sustained democratic backsliding by the ruling Georgian Dream party since 2023. The European Parliament’s February 2025 resolution demanded targeted sanctions.116European Parliament, Joint Motion for a Resolution on the Further Deterioration of the Political Situation in Georgia, February 13, 2025, https://www.europarl.europa.eu/doceo/document/RC-10-2025-0106_EN.html. The Georgian case highlights a strength of the Union’s enlargement architecture that is often overlooked: The EU can differentiate, freeze, and—when necessary—suspend processes without destroying the instrument itself. The ability to withhold membership prospect credibly is the foundation on which the transformative power of the accession offer rests. If the EU extended membership regardless of political behavior, it would bestow a prize without insisting on the transformation that justifies taking a strategic risk. Georgia shows that conditionality is not a bureaucratic formality but rather the source of the Union’s leverage.
In the Western Balkans, Montenegro and Albania remain the formal front-runners: Montenegro leads on chapter closures with sixteen provisionally closed as of June 2026 and a declared membership target of 2028, while Albania met the critical interim benchmarks for the rule-of-law chapters in May this year, unlocking its own chapter-closing process. North Macedonia, by contrast, remains stalled with no chapters provisionally closed, the Bulgaria veto unresolved, and the accession process effectively frozen.117European Commission, “2025 Enlargement Package”; European Council, “Enlargement: Albania Meets Interim Benchmarks for Fundamentals Cluster,” May 26, 2026, https://www.consilium.europa.eu/en/press/press-releases/2026/05/26/enlargement-albania-meets-interim-benchmarks-for-fundamentals-cluster/. Both examples are evidence that the enlargement machine continues to function when political will and administrative focus converge, even in a region that has spent two decades watching the accession horizon recede. Serbia’s trajectory is more troubling. The country combines domestic authoritarian tendencies with strategic ambiguity toward Russia and growing economic dependence on China. The result is selective engagement with EU reform processes: Belgrade pursues enough cooperation to retain access to European markets while preserving the political freedom to maneuver outside Europe.118European Commission, Serbia Report 2025, November 4, 2025, https://enlargement.ec.europa.eu/document/download/6e68ce26-b95b-48e1-921a-c60c12da8f00_en?filename=serbia-report-2025.pdf; Iliriana Gjoni, “Why the EU Must Change Course on Serbia,” Carnegie Endowment for International Peace, February 4, 2025, https://carnegieendowment.org/europe/strategic-europe/2025/02/why-the-eu-must-change-course-on-serbia. Bosnia and Herzegovina and Kosovo face structural constraints that standard EU conditionality cannot fix on its own. Bosnia is trapped by the dysfunctional constitutional architecture established by the Dayton Accords, while Kosovo’s path is blocked by its unresolved status and non-recognition by five EU member states.119Berta López Domènech, “Unlocking Bosnia and Herzegovina’s EU Accession Path,” European Policy Centre, April 14, 2026, https://www.epc.eu/publication/unlocking-bosnia-and-herzegovinas-eu-accession-path/; Dimitar Bechev et al., “Overcoming Inertia in Kosovo,” Carnegie Endowment for International Peace, May 22, 2025, https://carnegieendowment.org/research/2025/05/overcoming-inertia-in-kosovo.
The geographic architecture of European grand strategy
The geographic architecture that emerges from this analysis is not a single frontier but a layered strategic space—a distinction that matters for policy. The first and most strategically urgent ring is the eastern flank and Black Sea basin. Ukraine, Moldova, and the difficult question of Georgia constitute the core of what is ultimately an existential strategic challenge: whether the European Union can anchor the states that lie between its current eastern border and Russia’s zone of coercive influence firmly enough within European political and economic frameworks to prevent a return to the gray-zone vulnerability that made 2022 possible.120European External Action Service, “Questions and Answers on the European Union’s Strategic Approach to the Black Sea Region,” May 29, 2025, https://www.eeas.europa.eu/delegations/armenia/questions-and-answers-european-unions-strategic-approach-black-sea-region_en. The Black Sea is not a peripheral theater in this context. It is the geographic hinge between European security and access to the South Caucasus, the Caspian corridor, and Central Asian supply chains.121European External Action Service, “EU Launches Connectivity Agenda Platform to Strengthen Links between Europe and Central Asia through the Black Sea Region and the South Caucasus,” June 23, 2026, https://www.eeas.europa.eu/delegations/moldova/eu-launches-connectivity-agenda-platform-strengthen-links-between-europe-and-central-asia-through_en.
The EU’s 2025 strategic approach to the Black Sea region—linking maritime security, demining, corridor connectivity, and enlargement—is the first serious institutionalized treatment of the region’s strategic centrality.122Glib Kanievskyi and Mykhailo Samus, “The Changing Military Balance in the Black Sea: A Ukrainian Perspective,” Carnegie Endowment for International Peace, April 2, 2026, https://carnegieendowment.org/research/2026/04/the-changing-military-balance-in-the-black-sea-a-ukrainian-perspective; Kateryna Zarembo, “A Strategy Long Overdue: The EU’s New Vision for the Black Sea,” Royal United Services Institute, August 22, 2025, https://www.rusi.org/explore-our-research/publications/commentary/strategy-long-overdue-eus-new-vision-black-sea. Its operational instruments remain thinner than its strategic ambitions, and external analysis has rightly faulted the absence of concrete funding clarity and delivery mechanisms. However, the conceptual advance is significant: The Black Sea is now formally recognized not as a peripheral body of water but as a structuring feature of European continental strategy—a reframing that will shape how resources, attention, and diplomatic capital will be allocated over the coming decade.
The second ring is the Western Balkans. This is where the EU’s credibility as a strategic actor has been most visibly tested and repeatedly found wanting over the past two decades. That credibility deficit causes not only reputational harm but also strategic damage. Chinese infrastructure investment concentrated in Serbia and, to a lesser extent, in Montenegro and North Macedonia has created economic dependencies that complicate those countries’ capacity to align fully with EU regulatory frameworks, sanctions architecture, and technological standards.123Branimir Jovanović and Sonja Stojadinović, The EU’s and China’s Grants and Loans in the Western Balkans, Vienna Institute for International Economic Studies, April 2025, https://wiiw.ac.at/the-eu-s-and-china-s-grants-and-loans-in-the-western-balkans-dlp-7279.pdf. The Union’s response must combine differentiated accession acceleration—rewarding front-runners decisively rather than managing the region as a uniform bloc—with more determined use of financial, regulatory, and de-risking instruments to reduce the openings through which external actors consolidate leverage.124Iliriana Gjoni et al., “Rules or Deals? The EU’s Challenge in Regulating Corrosive Capital in the Western Balkans,” Carnegie Endowment for International Peace, December 8, 2025, https://carnegieendowment.org/europe/research/2025/12/rules-or-deals-the-eus-challenge-in-regulating-corrosive-capital-in-the-western-balkans. Staged accession for Albania and Montenegro is not simply a bureaucratic achievement but proof that Europe’s strategic toolkit can move decisively when political will is mobilized.125European Commission, “2025 Enlargement Package.”
The third ring is the southern flank: the Mediterranean, North Africa, the Middle East, and sub-Saharan Africa. Here the Union’s interests are real, but the appropriate instruments are different—less security integration, more development finance, migration management, energy diversification, and investment competition with China in fragile states.126European Commission and Italian Government, “The Mattei Plan for Africa and the Global Gateway: A Common Effort with the African Continent,” joint summit, Rome, June 20, 2025, https://www.governo.it/en/articolo/mattei-plan-africa-and-global-gateway-common-effort-african-continent-summit/29040; Italian Government, Piano Mattei per l’Africa: Relazione annuale al Parlamento sullo stato di attuazione, second annual parliamentary report, June 30, 2025, https://www.governo.it/sites/governo.it/files/documenti/documenti/Notizie-allegati/Piano%20Mattei/Relazione_Attuazione_PianoMattei_2025.pdf; Daniele Fattibene, “The Mattei Plan for Africa: From Aid to Partnership?,” Istituto Affari Internazionali, November 28, 2025, https://www.iai.it/en/publications/c41/mattei-plan-africa-aid-partnership; Brett Rayner et al., North Africa: Connecting Continents, Creating Opportunities, International Monetary Fund, February 4, 2026, https://www.elibrary.imf.org/view/journals/087/2026/002/article-A001-en.xml; Philippe Van Damme, The EU’s Competing Strategic Interests in Africa: Priorities for the Next MFF, Maastricht: European Centre for Development Policy Management, March 19, 2025, https://ecdpm.org/work/eus-competing-strategic-interests-africa-priorities-next-mff. For the purposes of European grand strategy, the southern flank should be viewed as a stabilization belt—a domain where European engagement matters for managing migration flows, economic dependencies, and influence competition—rather than as a substitute for the anchoring function that enlargement performs in the east. The risk of strategic distraction—of investing political capital in Mediterranean regions in ways that drain attention and resources from the existential challenge on the eastern flank—must be named and actively resisted.
The eastern flank is existential; the southern flank is operational. But operational neglect carries strategic consequences for the east because three of the EU’s most consequential challenges are concentrated there. First, energy supply: Algeria provides 12 to 14 percent of EU gas imports; the Eastern Mediterranean holds reserves whose development is strategically significant; and the Southern Gas Corridor has become a pillar of the post-Russian energy architecture.127Stuart Elliott, “EU, Algeria Eye Further Strengthening of Cooperation in Gas Sector: EC,” S&P Global, February 12, 2026, https://www.spglobal.com/energy/en/news-research/latest-news/natural-gas/021226-eu-algeria-eye-further-strengthening-of-cooperation-in-gas-sector-ec; European Commission, “Diversification of Gas Supply Sources and Routes,” October 2025, https://energy.ec.europa.eu/topics/energy-security/diversification-gas-supply-sources-and-routes_en. These are structural components of European energy security, not marginal supplements. Second, the Iran–Hormuz disruption referenced in Chapter 4 is a southern-theater crisis whose effects—LNG price spikes from Qatari cargo diversion, oil-price shocks, rerouted trade flows through Suez and the Mediterranean—would render the Mediterranean the most contested maritime space for European interests, against a naval presence that is thin relative to operational demands.128Velina Tchakarova, Marco Felsberger, and Herbert Saurugg, “Global Systemic Rupture: The Fourth Systemic Crisis and Its Architecture,” GfKV, April 12, 2026, https://gfkv.org/wp-content/uploads/2026/04/GfKV-Global-Systemic-Rupture-The-Fourth-Systemic-Crisis-and-Its-Architecture.pdf. Third, the demographic constraint identified above intersects directly with the southern flank: North and sub-Saharan Africa contain the world’s youngest populations, and Europe’s demographic deficit and Africa’s demographic surplus are structural complements—but only through managed legal channels, not through unmanaged irregular flows129Antonio Sempere and Suman Naishadham, “Thousands of Migrants in Ceuta Wait in Limbo While Spain Figures Out What to Do with Them,” Associated Press, August 21, 2026, https://apnews.com/article/spain-ceuta-morocco-migration-fe8e003171d5ce019d978ed9eaea49ed. that empower populist parties hostile to European integration.130Jakkie Cilliers, Julia Baum, and Gijsbert Werner, “Africa’s Future Demographic Dividend Matters to Europe Today,” Institute for Security Studies, July 23, 2025, https://futures.issafrica.org/blog/2025/Africas-future-demographic-dividend-matters-to-Europe-today. A strategic southern-flank policy must combine energy security, maritime presence, and managed migration into a single framework, with clear priority for the east but adequate resourcing for the south.
The structural vulnerabilities that strategic ambition must address
An honest assessment of the EU’s geographic strategy requires an equally honest accounting of its structural vulnerabilities. Three weaknesses deserve particular emphasis.
The first is veto vulnerability. The unanimity requirement in foreign affairs, enlargement decisions, and taxation means that a single member state can hold the entire process hostage for reasons that have nothing to do with the substantive merits of the question at hand. Hungary’s repeated blockage of Ukraine-related European Council decisions between 2022 and early 2026 is the most visible recent example, but the structural problem extends beyond any single government.131Elisabeth Heinz and Leticia Batista Cabanas, “The Unanimity Trap: What Is the EU Veto and Why Is It So Hard to Reform?” Euronews, March 31, 2026, https://www.euronews.com/my-europe/2026/03/31/to-survive-the-eu-needs-to-break-out-of-its-own-veto-trap. The accumulation of bilateral disputes, domestic political pressures, and transactional bargaining that shapes Council decision-making on enlargement drives outcomes toward the lowest common denominator—one that is incompatible with the strategic tempo a contested geopolitical environment demands. The solution is not institutional revolution—treaty amendment is not a realistic near-term option—but rather a combination of presidency conclusions as a functional substitute for blocked Council conclusions, greater use of variable geometry for urgent decisions, and, where possible, the narrowing of the range of policy domains that require unanimity.
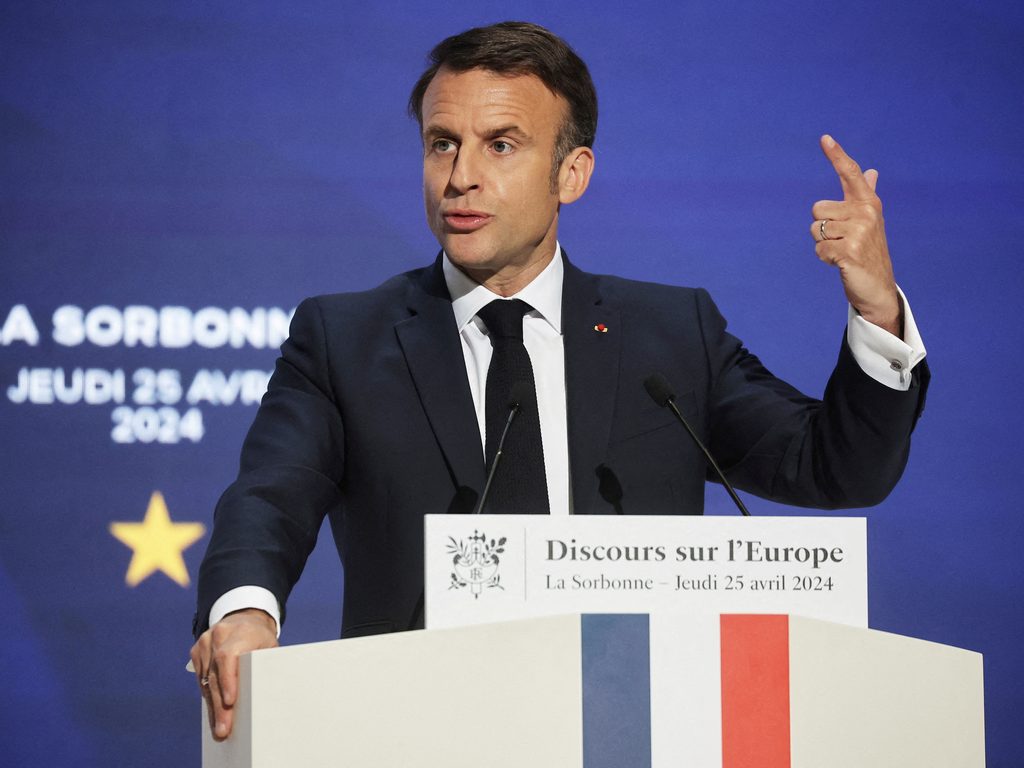
paradigm for European agency. Christophe Petit Tesson/Pool via REUTERS Connect.
The second vulnerability is China’s growing footprint in Europe’s own neighborhood and Turkey’s ambiguous role. The concentration of Chinese foreign direct investment in the Western Balkans is not a peripheral concern. Chinese investment in Serbian manufacturing, digital infrastructure, and port access creates dependency structures that intersect directly with EU enlargement politics, sanctions alignment, and technology standards.132Branimir Jovanovic, “What’s Driving Chinese FDI in the Western Balkans? And What Should Be Done About It?” Vienna Institute for International Economic Studies, June 12, 2025, https://wiiw.ac.at/what-s-driving-chinese-fdi-in-the-western-balkans–and-what-should-be-done-about-it-n-685.html. The EU has been slow to develop coherent instruments for de-risking Chinese economic influence concentration in candidate countries, in part because its member states have pursued divergent strategies toward Beijing and in part because the necessary regulatory and financial mechanisms do not exist at the scale the problem demands. Moreover, Turkey compounds the strategic ambiguity: Indispensable to European security architecture in the Black Sea, NATO’s southern flank, and migration management, the country is simultaneously entangled with Russia in energy markets and committed to a transactional posture toward both Western and Eastern power blocs that resists simple categorization.133Jeffrey Mankoff and Max Bergmann, “Strategic Ambiguity: Erdoğan’s Turkey in a Multipolar World,” Center for Strategic and International Studies, December 2, 2025, https://www.csis.org/analysis/strategic-ambiguity-erdogans-turkey-multipolar-world. Europe must design a strategy that works with a partner of that kind.
The third vulnerability is the widening-versus-deepening dilemma—or, rather, the cost of treating it as a dilemma. The tendency is to frame enlargement as a choice between EU expansion and institutional deepening when the current cycle suggests that this is precisely the wrong framing. Evidence from 2024–26 shows that staged integration and pre-accession statecraft can advance both simultaneously: deepening the EU’s engagement with candidate countries while using the reform conditionality of the accession process to drive institutional improvement within candidate countries and within the EU’s decision-making frameworks themselves. The European Commission’s March 2024 pre-enlargement reforms communication134European Commission, Communication from the Commission to the European Parliament, the European Council and the Council on Pre-Enlargement Reforms and Policy Reviews, March 20, 2024, https://commission.europa.eu/document/download/926b3cb2-f027-40b6-ac7b-2c198a164c94_en. makes this clear: Readiness for a larger Union requires internal EU reform to proceed in parallel with external accession progress.135Veronica Anghel, “Why the EU Is a Geopolitical Power: Wartime Enlargement, Integration, and Reform,” Journal of European Public Policy 32, no. 12 (September 2025): 2862-85, https://doi.org/10.1080/13501763.2025.2558974. The two processes are not sequential but constitutive of each other.
The architecture of a middle-power grand strategy: Geographic priorities
The geographic logic developed in this chapter points toward a specific and prioritized architecture for European grand strategy that goes beyond the generalities of neighborhood policy or the procedural language of accession management. That architecture has four components. First, the eastern flank and Black Sea basin must be treated as the strategic core. Support for Ukraine—military, financial, and the enlargement process itself—is not a charitable gesture. It is an investment in the EU’s strategic depth and conventional deterrence. A Ukraine that is functionally anchored to European frameworks is a country that has shifted the continent’s strategic geography in ways that reduce the vulnerability of every member state. The same logic applies, proportionally, to Moldova. Georgia’s frozen trajectory should be managed actively and not left to drift into permanent gray-zone status—neither integrated nor formally abandoned. A failed or captured state on the Black Sea’s eastern shore creates a security liability for Europe.
A staged accession framework that moves the most advanced candidates into substantial single-market integration, defense-industrial cooperation, and sanctions alignment—even before full membership is granted—is strategically sound and institutionally achievable within current treaty frameworks.
Second, the Western Balkans must be managed through deliberate differentiation rather than uniform regional solidarity. Rewarding front-runners such as Montenegro and Albania with concrete, irreversible integration steps is not a threat to regional cohesion—it is conditionality logic applied with strategic intent. It also sends a signal to the laggards and the hedgers that European patience is finite and that genuine alignment carries tangible rewards.136Luca Bertuzzi, “EU Set to Reallocate Western Balkans Funding in Favour of Accession ‘Frontrunners,’” Euronews, July 2, 2026, https://www.euronews.com/my-europe/2026/07/02/exclusive-eu-set-to-reallocate-western-balkans-funding-in-favour-of-accession-frontrunners. A staged accession framework that moves the most advanced candidates into substantial single-market integration, defense-industrial cooperation, and sanctions alignment—even before full membership is granted—is strategically sound and institutionally achievable within current treaty frameworks.
Third, the reduction of veto vulnerability must become a design principle of European enlargement strategy, not an aspiration deferred to treaty reform. This means making maximum use of existing mechanisms—qualified majority voting where it is available, enhanced cooperation formats, presidency conclusions—and building political coalitions strong enough to isolate procedural blockages rather than accommodate them.137Zselyke Csaky and Charles Grant, “Does EU Enlargement Require Voting Reform?” Centre for European Reform, May 9, 2025, https://www.cer.eu/insights/does-eu-enlargement-require-voting-reform. The broad convergence on enlargement as a geopolitical necessity—now visible across France, Germany, Poland, Sweden, Denmark, the Baltic states, Croatia, and Italy—constitutes the foundation of such a coalition, even allowing for variation in timing preferences and sequencing priorities.
Fourth, corridor logic must be elevated to the center of enlargement and neighborhood strategy. Geography becomes strategic when corridors are connected before treaties are signed. Military mobility corridors, energy transition infrastructure, digital backbone networks, and transport links that integrate candidate-country economies into European logistics frameworks are forms of pre-accession statecraft that yield strategic benefits independent of the formal accession calendar.138European Commission, “Commission Moves Towards ‘Military Schengen’ and Transformation of Defence Industry,” November 19, 2025, https://transport.ec.europa.eu/news-events/news/commission-moves-towards-military-schengen-and-transformation-defence-industry-2025-11-19_en. The Three Seas Initiative, the Trans-European Transport Network extension to candidate countries, and the energy infrastructure investments driven by the phase-out of Russian gas imports are all practical expressions of corridor logic. Integrating them into a coherent enlargement strategy has not yet happened at the level the geopolitical moment requires.
Conclusion: The middle power that can
The European Union is neither the impotent civilian power its critics mock nor the coherent strategic force its supporters envision. It is something more specific and more interesting: a middle power of continental scale that possesses structural strengths—market depth, institutional durability, regulatory reach, enlargement toolkit, and alliance embeddedness—whose strategic potential has been consistently weakened by a conversion problem: the institutionalized tendency to delay the translation of strategic awareness into coordinated action.139Tchakarova, “A Grand Strategy for Europe in the New Cold War.
That conversion problem is neither permanent nor intractable. The evidence shows that when geopolitical urgency combines with administrative focus and political coalition, the EU system can move with considerably greater speed and decisiveness than its critics allow. It opened accession negotiations with Ukraine and Moldova,140Council of the European Union, “First Accession Conference with Ukraine,” June 25, 2024, https://www.consilium.europa.eu/en/meetings/international-ministerial-meetings/2024/06/25/ukraine/; Council of the European Union, “First Accession Conference with Moldova,” June 25, 2024, https://www.consilium.europa.eu/en/meetings/international-ministerial-meetings/2024/06/25/moldova/. produced the most serious European preparedness doctrine in a generation,141Niinistö, Safer Together; European Commission, EU Preparedness Union Strategy; European Commission and European External Action Service, White Paper for European Defence – Readiness 2030. assembled unprecedented financial support for Ukrainian reconstruction and military capacity that exceeded US assistance, established a formal geostrategic framework for enlargement,142European External Action Service, “EU Assistance to Ukraine,” June 16, 2026, https://www.eeas.europa.eu/delegations/united-states-america/eu-assistance-ukraine-us-dollars_en. and moved the Black Sea from strategic periphery to strategic doctrine.143European External Action Service and European Commission, “New EU Strategy for Secure, Prosperous and Resilient Black Sea Region,” May 28, 2025, https://enlargement.ec.europa.eu/news/new-eu-strategy-secure-prosperous-and-resilient-black-sea-region-2025-05-28_en. These are real achievements that a serious assessment of European power cannot discount.
The path forward is defined by the logic of conversion at scale. Europe must embed preparedness as a governing institutional doctrine. It must treat enlargement as statecraft, not administration. It must organize its geographic priorities around the eastern flank and Black Sea basin as the strategic core, the Western Balkans as a theater of differentiated acceleration, and the southern flank as a stabilization belt. It must reduce veto vulnerability through political coalition rather than treaty revision. And it must redefine strategic autonomy not as separation from the alliance system, but as the capacity to carry a decisive share of the collective burden and to act, when necessary, without waiting for permission.
Chapter 4: Infrastructure, energy, and supply chains
The European Union’s infrastructure and energy architecture is undergoing the most consequential transformation since the post-WWII coal-and-steel era. Three concurrent forces drive this restructuring: the Russian energy weaponization (which started prior to the 2022 full-scale invasion of Ukraine), the cascading chokepoint vulnerabilities exposed by the Strait of Hormuz disruption, and a recalibration of European political consensus on baseload power. Together, these forces are producing a structural decoupling from hydrocarbon dependency that constitutes a genuine long-term strategic asset—provided the EU completes the institutional and physical infrastructure required to lock in these gains.
Energy intensity data shows clear structural differences in how efficiently major economies convert energy into economic output. On a purchasing power parity (PPP)-adjusted basis, the EU uses roughly 0.05 kg of oil equivalent (about 0.6 kWh) to generate one dollar of GDP, making it the most energy-efficient among the three major economies. The United States is less efficient, consuming around 0.08 kg of oil equivalent (about 0.9 kWh) per dollar of output—approximately 60 percent more energy than the EU. China is the most energy-intensive, requiring about 0.12–0.13 kg of oil equivalent (roughly 1.4–1.5 kWh) per dollar of GDP, which is about 2.5 times the EU level and 50–60 percent higher than the United States.144These differences reflect variations in industrial structure, energy mix, and capital stock composition. Figures are drawn from World Bank and IEA energy-intensity-of-GDP data (expressed in megajoules per 2017 PPP dollar) and have been converted to a common energy unit for comparability. 145World Bank, “Energy Intensity Level of Primary Energy (MJ/$2017 PPP GDP),” https://data.worldbank.org/indicator/EG.EGY.PRIM.PP.KD.
The degree of external energy dependence differs sharply across major global economies when measured as import share of total primary energy consumption. The European Union remains the most structurally import-dependent system, with roughly 55–60 percent of its energy consumption met through imports,146Eurostat, Shedding Light on Energy in Europe – 2025 Edition (Publications Office of the European Union, 2025), https://ec.europa.eu/eurostat/web/interactive-publications/energy-2025. reflecting its limited domestic hydrocarbon base and heavy reliance on external oil and gas suppliers. The United States, by contrast, has significantly reduced its exposure due to the shale revolution: Imports cover only around 15–20 percent of total energy use,147U.S. Energy Information Administration, “Imports Made Up 17% of U.S. Energy Supply in 2024, the Lowest Share in Nearly 40 Years,” Today in Energy, July 7, 2025, https://www.eia.gov/todayinenergy/detail.php?id=65664. and it has shifted into a net-exporting position in some fuels, especially natural gas. China holds a middle position, importing approximately 15 percent of its total energy needs,148Zheng Xin, “Energy Self-Sufficiency Rate Reaches 85%,” China Daily, December 17, 2024, https://www.chinadaily.com.cn/a/202412/17/WS6760d927a310f1265a1d34c6.html. although its vulnerability is concentrated in oil, which remains critical for transport and industrial supply chains. These differences illustrate distinct structural energy models: the EU as an import-dependent consumer economy, the US as a largely self-sufficient (and increasingly export-oriented) producer, and China as a hybrid system with partial domestic security and persistent external exposure in key hydrocarbons.
The energy transformation: From vulnerability to optionality
Prior to 2022, the EU’s energy architecture rested on a tacit assumption that Russian pipeline gas would remain available, affordable, and politically neutral. That assumption has been comprehensively invalidated. Russian pipeline gas in EU imports fell from approximately 40 percent in 2021 to 12 percent by 2025, a decline achieved through reduced demand, Norwegian pipeline expansion, and the most rapid LNG import infrastructure buildout in European history.149Council of the European Union, “Where Does the EU’s Gas Come From?” https://www.consilium.europa.eu/en/infographics/where-does-the-eu-s-gas-come-from/.
The post-2022 LNG infrastructure buildout—Wilhelmshaven, Brunsbüttel, Eemshaven, the Adriatic LNG expansion, and the Baltic Connector reconstruction—has broken Europe’s Gazprom dependency. Political and commercial relationships built around LNG diversification, such as long-term offtake agreements, capital commitments, and supplier-state relationships, offer strong alternatives to Russian energy. However, European countries continue to import oil and gas from Russia or from intermediaries like Kazakhstan when the underlying source is effectively the same. The important difference is that Europe now possesses genuine optionality on gas sourcing: US LNG, Qatari LNG, Norwegian pipeline capacity, East Mediterranean supplies, and Algerian pipeline capacity collectively provide a diversified portfolio that was absent in 2021.150Michał Kurtyka, Marcin Gawęda, and Lisa Basquel, From Diversification to Integration: A Market-Based LNG Coordination Mechanism in Europe, Atlantic Council, June 10, 2026, https://www.atlanticcouncil.org/in-depth-research-reports/report/from-diversification-to-integration-a-market-based-lng-coordination-mechanism-in-europe/. Optionality is power: The ability to threaten sourcing substitution changes the negotiating dynamic with every hydrocarbon supplier, from Algeria to Azerbaijan.
European LNG import capacity expanded by approximately 75 billion cubic meters between 2022 and 2024, enough to replace the entirety of prewar Russian pipeline flows, with operational redundancy to spare.
In parallel, southeast Europe is consolidating its role as a structural import gateway, with planned enhancements to Greece’s Revithoussa terminal and further development of the Alexandroupolis floating storage and regasification unit (FSRU) as a permanent regional hub feeding the Vertical Gas Corridor toward Bulgaria, Romania, and Hungary.151Eleni Varvitsioti, “Greece Eyes Central Role in Europe’s Post-Russia Gas Market,” Financial Times, February 22, 2026, https://www.ft.com/content/f169bb37-4d25-43c3-846d-4849a708a5c2. These investments are not merely redundancy measures; they are designed to move Europe from emergency resilience toward sustained market liquidity in global LNG trade. It is the political and commercial relationships built around LNG diversification—long-term offtake agreements, capital commitments, and supplier-state relationships—that create the strong path dependency, not the physical infrastructure itself (FSRUs are floating units and could theoretically be redeployed).
At the same time, pipeline-adjacent infrastructure and interconnectivity projects are being upgraded to ensure that LNG regasification capacity translates into continent-wide flow flexibility. The expansion of interconnectors such as Greece–Bulgaria (IGB), Bulgaria–Serbia, and Poland–Slovakia, alongside reinforcement of Germany’s north–south corridor, is effectively eliminating the last remnants of regional segmentation within the EU gas market. The strategic implication is that new LNG capacity is no longer being built in isolation but as part of an integrated system architecture that allows marginal LNG cargoes to arbitrage across the entire continent. Several additional FSRU projects under consideration in the Eastern Mediterranean and Adriatic further reinforce this trajectory, embedding LNG import capability as a semipermanent feature of European energy security. Collectively, these planned investments point to a structural transition from rapid substitution of Russian volumes to the construction of a fully flexible, globally integrated gas import system.
A baseload divide
The most pronounced shift in Europe’s energy perspective relates to nuclear power. For two decades after the Chernobyl and Fukushima disasters, nuclear energy remained politically contested across much of the EU, with Germany’s Energiewende embedding a phase-out consensus that was widely emulated.152Bundesministerium fur Wirtschaft und Klimaschutz, Energiewende: Das Jahresmonitoring, November 2023, https://data.bundesnetzagentur.de/Bundesnetzagentur/SharedDocs/Mediathek/Monitoringberichte/monitoringberichtenergie2023.pdf. That consensus has since fractured. The post-2022 realization that gas dependency creates strategic vulnerability has prompted a European nuclear renaissance, codified in the Nuclear Alliance framework. Launched in February 2023, the coalition of eleven (now fourteen) EU member states committed to maintaining or expanding nuclear capacity with others interested in joining.153Ben Judah Rachel Rizzo, Théophile Pouget-Abadie, Jonah Allen, and Francis Shin, How to Strike a Grand Bargain on EU Nuclear Energy Policy, Atlantic Council, October 16, 2023, https://www.atlanticcouncil.org/in-depth-research-reports/report/how-to-strike-a-grand-bargain-on-eu-nuclear-energy-policy/.
The European Commission has increasingly recognized nuclear energy as part of the EU’s agenda, supporting supply-chain security for medical isotopes,154European Council, “Radioisotopes for Medical Use: Council Approves Conclusions,” June 17, 2024, https://www.consilium.europa.eu/en/press/press-releases/2024/06/17/radioisotopes-for-medical-use-council-approves-conclusions/. nuclear fuel fabrication, and the development of small modular reactors (SMRs). In 2026, it published its first dedicated strategy for SMRs,155European Commission, “Strategy for the Development and Deployment of Small Modular Reactors (SMRs) in Europe,” COM(2026) 117 final, March 10, 2026, https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX%3A52026DC0117&qid=1773310096275. signaling a notable departure from the commission’s earlier, more cautious approach to nuclear energy.
Across Europe, nuclear energy is experiencing an uneven revival. In France, the most significant program is the new EPR2 fleet, with plans for at least six reactors (and options for more)156Électricité de France, EPR2: A Key Program for the Low-Carbon Electricity of Tomorrow, https://www.edf.fr/groupe-edf/produire-une-energie-respectueuse-du-climat/lenergie-nucleaire/nouveau-nucleaire/programme-epr2. intended to replace aging capacity and stabilize long-term nuclear output. This initiative walks back earlier phase-out rhetoric and reaffirms nuclear as a core pillar of the French system.157One needs to note that France’s nuclear fleet experienced exceptionally low availability in 2022, driven by maintenance backlogs, stress-corrosion cracking and weather-related constraints, but availability recovered substantially from 2023 onward. In 2026, the fleet has again faced temporary disruptions, particularly during periods of extreme heat and drought, which have forced EDF to reduce output or temporarily shut down reactors because of environmental limits on river temperatures and water availability. These episodes highlight a growing climate-related operational risk that needs to be mitigated. In Central and Eastern Europe, Poland is launching its first nuclear program, anchored in the AP1000 reactor project led by Westinghouse, alongside parallel discussions with South Korean partners on additional capacity, marking one of the largest greenfield nuclear expansions in Europe in decades.158World Nuclear Association, World Nuclear Performance Report 2025, https://world-nuclear.org/our-association/publications/world-nuclear-performance-report. The Czech Republic is planning a major expansion at Dukovany, selecting KHNP technology for new units. Hungary is proceeding with Paks II, but the 2026 change in government raises the question of who the technology provider will be instead of Russia. Romania is expanding its Cernavodă plant and investing in small modular reactor development.159Similarly, the non-EU United Kingdom is pursuing both large-scale reactors, such as Hinkley Point C and Sizewell C, and an aggressive SMR strategy led by Rolls-Royce SMR.
The renewables integration challenge
Renewable energy—wind, solar, hydro—has expanded dramatically, with the REPowerEU plan targeting a 45 percent renewable share in final energy consumption by 2030, up from 22 percent in 2021.160European Commission, “REPowerEU: Joint European Action for More Affordable, Secure and Sustainable Energy,” press release, March 7, 2022, https://ec.europa.eu/commission/presscorner/detail/en/ip_22_1511. This expansion is structurally beneficial for strategic autonomy: Wind and solar have zero fuel imports, no chokepoint vulnerability, and falling marginal costs. However, the intermittency of renewables creates a grid stability challenge that cannot be resolved without dispatchable baseload or massive storage deployment.
According to some member states, pushing both nuclear and renewables is not contradictory; it is the only technically coherent pathway to full decarbonization with strategic resilience. Germany’s Osterpaket legislation, passed in July 2022, targets 80 percent renewable electricity by 2030 while extending the operating lives of its three remaining nuclear plants until April 2023.161Bundesministerium für Wirtschaft und Klimaschutz, Osterpaket: Kernpunkte des Osterpakets für einen beschleunigten Ausbau der erneuerbaren Energien, 2022, https://www.bundestag.de/dokumente/textarchiv/2022/kw27-de-energie-902620. However, despite the energy crisis reopening the debate, Germany proceeded with its nuclear phase-out. The country’s path consequently shifted from technological complementarity toward rapid renewable scaling, with system flexibility provided by markets and gas infrastructure. That structure is more exposed to fuel price volatility but remains politically aligned with the Energiewende commitment.
A growing body of European policy analysis, including work by the European Roundtable on Climate Change and Sustainable Transition (ERCST),162Andrei Marcu et al., 2025 State of the EU ETS Report, European Roundtable on Climate Change and Sustainable Transition, May 21, 2026, https://ercst.org/2025-state-of-the-eu-ets-report/. argues that the central constraint in a high-renewables system is no longer installed capacity, but system adequacy and flexibility across time scales. Wind and solar shares rise above 50–60 percent of electricity generation, marginal value declines sharply during peak production hours, and scarcity pricing becomes more frequent during low-wind and low-solar periods. This creates a structural “cannibalization effect,” where additional renewable capacity does not proportionally increase system reliability without parallel investments in grids, interconnection, demand response, and dispatchable generation. Under this framework, electricity systems become increasingly dependent on flexibility resources rather than energy volume, changing the key policy question from how much renewable capacity to build to how to ensure firm capacity during extended periods of low renewable output.
Battery storage is scaling fast at the short-duration end. EU capacity has grown roughly tenfold since 2021, reaching just over 100 GWh across Europe by the end of 2025, and now smooths intra-day solar peaks and price volatility.163pv Europe, “Europe Hits 100 GWh as Utility-Scale Takes Over the Storage Market,” July 15, 2026, https://www.pveurope.eu/markets/europe-hits-100-gwh-utility-scale-takes-over-storage-market. But economics deteriorate sharply beyond four-to-six-hour discharge windows, leaving the multi-day and seasonal shortfalls of low-wind, low-solar periods to technologies like pumped hydro and long-duration storage that remain immature or geographically constrained at scale. Storage is therefore best understood as a complement to firm dispatchable capacity, not a substitute for it: it can shave peaks, but it cannot yet underwrite multi-week adequacy margins.
At the European level, this has translated into a growing recognition that capacity mechanisms, cross-border interconnection, and firm low-carbon generation are becoming system-critical infrastructure rather than optional complements. While electrification of transport, heating, and industry is expected to significantly increase total electricity demand, it also increases the cost of intermittency by raising the consequences of supply shortfalls. As a result, even in highly ambitious decarbonization scenarios, the system continues to require a substantial backbone of dispatchable capacity—whether from energy storage, nuclear, hydro, biomass, or gas and hydrogen-fired plants—to maintain adequacy margins. Total dispatchable generation capacity in the EU27 remains remarkably stable at roughly 420–510 GW,164ENTSO-E and ENTSOG, TYNDP 2024 Scenarios Report, European Network of Transmission System Operators for Electricity, January 2025, https://2024.entsos-tyndp-scenarios.eu/wp-content/uploads/2025/01/TYNDP_2024_Scenarios_Report_FInal_Version_250128_web.pdf. even as the underlying technology mix shifts almost entirely from coal and gas. This is why EU pathways converge on the need for a firm low-carbon or dispatchable backbone on that order of magnitude by mid-century, not as an alternative to renewables, but as the structural condition enabling their dominance.
Supply chains and strategic sovereignty
The COVID-19 pandemic and the subsequent acceleration of US–China technology decoupling exposed the EU’s deepest supply-chain vulnerability: critical dependencies on single-country suppliers for semiconductor inputs, critical raw materials, and advanced-manufacturing components that underpin both civilian industrial production and emerging defense capability. The EU’s legislative response—the EU CHIPS Act and the Critical Raw Materials Act—represents the most ambitious reshoring and diversification program in European industrial history.
The EU CHIPS Act, adopted in September 2023, mobilizes €43 billion ($49 billion) in policy-driven investments, aiming to double the EU’s share of global semiconductor production capacity to 20 percent by 2030, up from approximately 10 percent in 2020.165European Parliament and Council of the European Union, Regulation (EU) 2023/1781 Establishing a Framework of Measures for Strengthening the European Semiconductor Ecosystem (Chips Act), adopted September 13, 2023, published in the Official Journal (OJ L 229) on September 18, 2023, https://eur-lex.europa.eu/eli/reg/2023/1781/oj/eng. The strategic logic is defensive: Advanced logic chips (below 10nm) are essential to AI, defense systems, and industrial automation, and the EU currently produces none of them at scale. TSMC’s announced Dresden plant, Intel’s Magdeburg facility (although later canceled), and STMicroelectronics’ Crolles expansion make up the first tranche of this buildout, but the gap between announcement and operational production remains substantial.
The Critical Raw Materials Act, adopted in April 2024, establishes EU domestic extraction, processing, and recycling targets for thirty-four critical raw materials. The benchmark is significant: By 2030, the EU must extract at least 10 percent, process at least 40 percent, and recycle at least 25 percent of its annual consumption of strategic raw materials, including lithium, cobalt, nickel, manganese, and rare earth elements.166European Parliament and Council of the European Union, Regulation (EU) 2024/1252 Establishing a Framework for Ensuring a Secure and Sustainable Supply of Critical Raw Materials (Critical Raw Materials Act), adopted April 11, 2024, published in OJ L (2024/1252) on May 3, 2024, https://eur-lex.europa.eu/eli/reg/2024/1252/2024-05-03/eng. For lithium alone, EU demand is projected to increase twelvefold by 2030, driven by battery production for electric vehicles and grid storage. The EU currently produces less than 1 percent of the global lithium supply, with approximately 56 percent of processing concentrated in China.167European Commission, Directorate-General for Internal Market, Industry, Entrepreneurship and SMEs. “Study on the Critical Raw Materials for the EU 2023 – Final Report.” Publications Office of the European Union, 2023, https://single-market-economy.ec.europa.eu/publications/study-critical-raw-materials-eu-2023-final-report_en.
The strategic vulnerability here is not theoretical. China’s August 2023 export controls on gallium and germanium—critical for semiconductors and infrared optics—showed the coercive potential of critical raw material concentration. The EU sources 77 percent of its gallium from China.168Eurostat, “International Trade in Critical Raw Materials,” Statistics Explained, data extracted June 2026, https://ec.europa.eu/eurostat/statistics-explained/index.php?title=International_trade_in_critical_raw_materials. In response, the European Commission has selected sixty strategic projects, including forty-seven within the EU and thirteen in third countries and overseas territories to accelerate extraction and processing, and has announced the establishment of an EU Critical Raw Materials Centre in 2026 to coordinate joint purchasing, strategic stockpiling, and supply-chain monitoring.169European Commission, Strategic Projects Under the Critical Raw Materials Act, March 25, 2025, https://single-market-economy.ec.europa.eu/sectors/raw-materials/areas-specific-interest/critical-raw-materials/strategic-projects-under-crma/selected-projects_en. However, mining and processing projects typically take up to fifteen years to mature, and the CRMA did not commit public funding to guarantee demand at specified prices, leaving a gap between policy ambition and operational security.170Niklas Hintermayer and Antonia Hmaidi, “China’s Rare-earths Export Controls Hit EU Rearmament—But Open a Strategic Window,” Mercator Institute for China Studies, October 1, 2025, https://merics.org/en/comment/chinas-export-controls-hit-eu-rearmament-open-strategic-window.
Honest strategic assessment must identify domains where European industrial policy buys time rather than solves the underlying problem. In clean-energy manufacturing, China produces approximately 80 percent of global solar modules, over 75 percent of battery cells, and roughly 70 percent of electric vehicles. Chinese cost advantages are not primarily subsidy-driven; they are structural, rooted in vertically integrated supply chains, unmatched scale economies, a decade of process-engineering optimization, and wage levels that remain a fraction of European labor costs. The EU’s countervailing duties on Chinese EVs offset the price gap temporarily; they do not eliminate the cost-structure differential. In critical-minerals processing, China controls approximately 85 percent of rare earth refining and 60 percent of lithium refining. CRMA targets are necessary, but European mining projects face permitting timelines of seven to fifteen years, and the CRMA did not commit public funding to guarantee offtake prices—the mechanism that would de-risk private investment against Chinese price-cutting of the kind that destroyed European solar manufacturing between 2012 and 2018. In shipbuilding, China builds half the world’s commercial tonnage; European shipyards have contracted to niche segments insufficient to support the naval expansion a credible maritime posture demands. These domains require a managed-dependency strategy: diversified supply sources, stockpiling, recycling capacity, and sustained tariff defense rather than a self-sufficiency narrative. Where Europe leads—in pharmaceuticals, aerospace, chemicals, machinery, and luxury goods—the task is defense. Where it is structurally weak, the task is managed competition with realistic timelines.
The industrial base: Emerging hard-power manufacturing
The EU’s industrial base is undergoing its most significant restructuring since the post-WWII reconstruction period. It is being reshaped by three concurrent processes: the ReArm Europe defense investment surge, the dual-use technology integration driven by the EDIP, and the wider industrial policy response to Chinese overcapacity and US Inflation Reduction Act subsidy competition.
ReArm Europe, launched in March 2025, mobilizes €800 billion ($915 billion) in defense investment over the 2025–30 period, structured through common procurement, production capacity expansion, and the permanent structuring of European defense industrial cooperation.171European Commission and High Representative of the Union for Foreign Affairs and Security Policy, Joint White Paper for European Defence Readiness 2030, JOIN (2025) 120 final, March 19, 2025, https://data.consilium.europa.eu/doc/document/ST-7293-2025-INIT/en/pdf. The operational challenge is not money; it is production capacity. European artillery shell production capacity has increased from approximately 300,000 rounds annually before the war started in 2022 to a target of 2 million rounds by the end of 2025.172Rudy Ruitenberg, “European Ammo Firms Tell EU to ‘Hurry Up’ with 155mm Shell Aid Top-Up,” Defense News, June 20, 2024, https://www.defensenews.com/global/europe/2024/06/20/european-ammo-firms-tell-eu-to-hurry-up-with-155mm-shell-aid-top-up/. This amounts to a sixfold expansion, achieved through the Act in Support of Ammunition Production (ASAP) mechanism, which provides co-financing for production line expansion across fourteen member states.173By late 2025, combined European 155mm production is estimated to have reached approximately 1.2–1.3 million rounds annually—about a fourfold increase from pre-war levels but short of the 2 million target, which in practice slipped beyond its original end-2025 deadline. See “155mm Artillery Shell Production EU 2026: Race to Supply Ukraine,” Ukraine War Analytics, February 28, 2026, https://ukraine-war-analytics.com/weapons/155mm-shell-production-eu-2026.html.
The dual-use logic—technologies with both civilian and military applications—is central to the strategic case for European industrial policy. Advanced semiconductors, quantum computing, AI, hypersonic propulsion, and space launch capability all have commercial markets and defense applications. The EDIP framework explicitly channels Horizon Europe civilian research funding toward dual-use outcomes, creating an innovation pipeline that leverages civilian R&D budgets for defense outcomes without requiring parallel defense-dedicated funding streams.174Daniel Fiott, “The European Defence Industry Programme: From Fragmentation to Integration,” European Security, 33, no. 2 (2024): 215–34.
Europe’s defense production surge faces a labor bottleneck that threatens to outpace capital deployment. Kearney estimates that raising defense spending to 3 percent of GDP–consistent with NATO’s revised trajectory–would require approximately 760,000 additional skilled workers across the EU by 2030.175Michael Kahn, Christoph Steitz, and Dominique Patton, “Help Wanted: Europe’s Defence Companies Scramble for Workers as Business Booms,” Reuters, May 27, 2025, https://www.reuters.com/business/aerospace-defense/europes-defence-companies-scramble-workers-business-booms-2025-05-27/. The existing workforce is aging rapidly: Nearly one-quarter of defense sector employees have over twenty years of experience, and many are approaching retirement.176Experis, Future Forward: Mission 2030: Closing Tech Talent Gaps in Aerospace & Defense, May 6, 2026, https://manpowergroup.nl/wp-content/uploads/2026/05/EXP-2026-Aerospace-and-Defense-Mission-2030-White-Paper.pdf. Arms manufacturers, suddenly flush with orders, are competing for coders, engineers, data scientists, and skilled tradespeople who have attractive opportunities to work in civilian industries and are typically not drawn to careers in weapons production.177This reflects less a moral aversion to defense work than a structural mismatch. Firms are constrained in how aggressively they can bid for talent against civilian tech and industry, since uncontrolled wage growth would undercut their cost competitiveness, while the specialized, low-volume manufacturing know-how the sector requires is simply scarce in the broader labor market. In response, firms such as PBS Group in the Czech Republic have raised wages by 8–10 percent and established in-house training schools, while KNDS France has expanded shifts and increased hiring by 50 percent annually in recent years.
The most dynamic frontier of hard-power manufacturing today is not traditional weapons platforms but unmanned systems, AI-enabled battle networks, and low-cost, “attritable” drones—domains in which Ukraine has become a living laboratory. The EU moved in 2025 to structurally integrate Ukraine’s defense industry into its own industrial ecosystem. Ukraine has been officially recognized as a partner under the SAFE program, allowing Ukrainian manufacturers to fully participate in joint European procurement, integrate into supply chains, and engage in high-tech defense projects. An EU-Ukraine Task Force on Defense Industrial Cooperation, which held its first meeting in May 2025, coordinates participation in SAFE and EDIP, facilitates systematic information exchange on capabilities and bottlenecks, and leverages Ukraine’s combat experience to shape the EU’s technological road maps. The EDIP regulation further allocates €300 million ($343 million) to a Ukraine Support Instrument aimed at modernizing Ukraine’s defense sector and supporting its integration with European manufacturers, while the Fund to Accelerate Defense Supply Chain Transformation (FAST) is set at a minimum of €150 million ($172 million).178Defense Mirror, “EU Adopts New Law to Launch European Defence Industry Programme,” November 27, 2025, https://www.defensemirror.com/news/40605/. 2025 proved a breakthrough year that began to unlock long-standing restrictions to Europe-Ukraine defense-industrial cooperation. The strategic logic of integration—a rearmed Ukraine as Europe’s first line of defense and a source of combat-tested innovation for European firms—is now broadly accepted.
The TEN-T network as geopolitical infrastructure
The Trans-European Transport Networks (TEN-T) are the physical expression of the EU’s connectivity strategy a programme demanding €700 billion ($808 billion) infrastructure investments that connects the bloc’s internal nodes while simultaneously anchoring adjacent states—Ukraine, Moldova, the Western Balkans, and Georgia—into European logistics architecture.179European Parliament and Council of the European Union, Regulation (EU) 2024/1679 on Union Guidelines for the Development of the Trans-European Transport Network, adopted June 13, 2024, published OJ L, 2024/1679, June 28, 2024, https://eur-lex.europa.eu/eli/reg/2024/1679/oj/eng; European Commission, “Commission Identifies Infrastructure Priorities and Investment Needs for Trans-European Transport Corridors,” Directorate-General for Mobility and Transport, September 22, 2016, https://transport.ec.europa.eu/news-events/news/european-commission-identifies-infrastructure-priorities-and-investment-needs-trans-european-2016-09-22_en. The revised TEN-T Regulation, adopted in June 2024, extends European transport corridors to Ukrainian and Moldovan territory, integrating Odesa, Lviv, and Kyiv into the European core network.
Infrastructure is geopolitics at low visibility.180Bertrand Badré and Saurabh Mishra, “The Geopolitics of Infrastructure,” Project Syndicate, April 20, 2026, https://www.project-syndicate.org/commentary/infrastructure-source-of-global-power-by-bertrand-badre-and-saurabh-mishra-2026-04. A country whose road, rail, and port infrastructure integrates with European standards and supply chains has its strategic orientation shaped well before any formal political decision is made. The nine core TEN-T corridors, including the Baltic–Adriatic, North Sea–Baltic, Mediterranean, and Rhine–Danube, create physical interdependence that raises the cost of strategic realignment for any member or candidate state.
Strategic interconnections: From industrial ambition to foundational resilience
The €800 billion ReArm Europe plan, the scaling of ammunition production, the dual‑use integration through EDIP, the mobilization of small and medium-enterprise supply chains, and the structural integration of Ukraine’s defense industry all point toward the emergence of a genuine European hard‑power manufacturing base. However, these ambitions cannot be realized in a vacuum. They depend on three foundational layers that must operate simultaneously: secure, affordable, and diversified energy; resilient supply chains for critical raw materials and advanced components; and a physical transport infrastructure that can rapidly move forces and matériel across the continent.
The EU has transformed from an energy‑import‑dependent bloc to one with genuine sourcing optionality—driven by the structural break with Russian pipeline gas, the unprecedented LNG infrastructure buildout, and a restoring of baseload sovereignty.181Leticia Batista Cabanas and Elisabeth Heinz, “EU Energy Mix: Crisis Pushes Balance on Nuclear, Renewables and Security,” Euronews, April 28, 2026, https://www.euronews.com/my-europe/2026/04/28/from-crisis-to-transition-how-europe-is-rethinking-its-energy-strategy. Without energy security, the electrification of industry, the operation of chip fabs, and the surge production of ammunition all remain vulnerable to coercion. The overarching argument is that the EU’s hard‑power manufacturing capacity will be as strong—or as brittle—as the energy, materials, and logistical systems on which it rests.
Chapter 5: Six policy priorities
The middle power that can act
This report’s argument has been documentary rather than prescriptive. We have established a balance sheet—based on trade, savings, fiscal stance, the single market, human capital, energy architecture, and industrial base—and we have shown, indicator by indicator, that the European Union already commands the necessary structural assets to navigate Cold War 2.0 as a credible compound power. What we have not yet outlined is the operational principle by which those assets should be deployed.
That principle is the Simultaneity Approach, and it is the doctrinal departure that distinguishes this report from the dominant strain of European strategic commentary. The premise is straightforward. The European Union faces a convergence, not a sequence, of pressures: a more transactional Trump administration, Chinese industrial overcapacity, Russia’s war against Ukraine, the conflict in Iran and the resulting disruption to the Strait of Hormuz, escalating competition with Beijing over chips and critical materials, and the internal competitiveness gap Draghi diagnosed. Yet the institutional architecture of European decision-making—built on consensus-based deliberation across sectorally siloed policy domains—is structurally unsuited to managing concurrent, cross-cutting crises.
Trade policy is industrial policy is energy policy is enlargement policy is defense policy is competitiveness policy.
The Simultaneity Approach holds that European strategic agency must be reorganized around compound crises, not sequential ones. Trade policy is industrial policy is energy policy is enlargement policy is defense policy is competitiveness policy. The instruments must be deployed concurrently and reinforce one another, with each lever amplifying the others. Brussels has begun to operate on this premise—the near-simultaneous activation of NextGenerationEU, ReArm Europe, the Critical Raw Materials Act, the CHIPS Act, the SAFE program, and the Anti-Coercion Instrument is not an accident of legislative tempo. It is the early operational expression of a compound strategic posture. What remains is to make that posture institutional rather than incidental.
Six policy priorities in operational sequence
The six priorities articulated below should be understood not as separable reforms but as a single integrated deployment plan. They are sequenced by their dependency structure: Each priority unlocks the operational space within which the next can be deployed.
1. Complete the capital markets union—the activation that unlocks all others.
The starting point is capital. European households and corporations save approximately $4.8 trillion per year—about the same as the United States in absolute terms. That savings stock, channeled into bank deposits and domestic sovereign bonds rather than equity, venture capital, and growth-stage private capi-tal, is the single largest under-deployed strategic asset in the European Union. The diagnosis has repeatedly been made—by Letta, Draghi, Véron at Bruegel, and the European Central Bank—and the operational architecture for completion has been mapped.182Letta, Much More Than a Market; Draghi, The Future of European Competitiveness; Véron, Breaking the Deadlock. What is required is the political decision to consolidate supervision under a single European Securities and Markets Authority with binding authority across all twenty-seven member states, to harmonize insolvency law and tax treatment, and to remove the national-regulator veto points that currently fragment the bloc’s capital pools. The economic return is in the hundreds of billions of euros annually at virtually no additional public cost. The strategic return is larger: A capital markets union that absorbs European savings is the difference between European technology funding American innovation and European technology funding European industrial sovereignty. This is the activation that unlocks all the others.
A capital markets union that absorbs European savings is the difference between European technology funding American innovation and European technology funding European industrial sovereignty.
A capital markets union would close the late-stage funding gap, but it would leave three structural conditions untouched—each of which reproduce the deficit independently of capital availability: the absence of sovereign compute infrastructure at frontier-training scale, a regulatory asymmetry in which the AI Act imposes compliance costs on European developers from inception while American competitors scale in a comparatively unregulated home market before facing equivalent obligations, and a talent-circulation pattern in which European universities train world-class AI researchers who relocate to American frontier labs for compute access and higher compensation. Europe’s realistic strategic objective is not to build a European OpenAI. It is to ensure that European industry can deploy AI at scale in the sectors where Europe already leads—in manufacturing, healthcare, energy, and logistics—without strategic reliance on American providers. That requires sovereign compute, interoperable data spaces under European governance, and a regulatory framework that enables industrial deployment. It does not require winning the foundation-model race. It requires becoming a sovereign and strategically autonomous user of the technology that race produces.
2. Defend and strategically deploy the trade surplus position.
Europe is the world’s largest external trader. That position gives it leverage, but only if Brussels chooses to wield it. The 2024 anti-subsidy investigation into Chinese electric vehicles, the credible threat of using the Anti-Coercion Instrument against discriminatory practices, and the structuring of trade defense around strategic sectors rather than headline volumes are the early instruments of a compound trade-policy posture. They must be extended. The operating principle is market access conditionality: Access to a $4.4 trillion external market is something no major economy can replace, and the EU should price that access against alignment with European standards on labor, climate, and economic security. This is not protectionism. It is the consistent application of European regulatory standards as a condition of commercial access—a doctrine that the Brussels Effect has already demonstrated at scale but has not yet been consolidated as a coherent strategic framework. The EU has applied this principle partially in trade negotiations—the Mercosur, New Zealand, and Indonesia agreements all incorporate labor, climate, and economic-security conditionality. What remains is to consolidate that practice as a coherent strategic framework rather than a case-by-case negotiating posture. The next iteration of EU trade policy should be organized around this principle from the outset.
3. Expand the single market and EU membership to Ukraine, Moldova, and the Western Balkans.
Enlargement is the European Union’s most distinctive strategic instrument and its most powerful long-term tool. Russia’s invasion of Ukraine has restored political momentum to a process that had stagnated for a decade. The EU should treat enlargement not as a sequential process of merit-based accession but as the operational core of a Cold War 2.0 geopolitical strategy. Ukraine and Moldova should be brought into the single market through phased sectoral integration well in advance of formal accession. The Western Balkans should be granted accelerated integration into the customs union, the energy market, and the digital single market—with treaty-level commitments structured to be reversible if member states regress on the rule of law, but front-loaded to create irreversible momentum. Each accession extends the regulatory perimeter, deepens the market, and narrows the strategic space within which the DragonBear axis can operate in Europe’s neighborhood.
Ukraine and Moldova should be brought into the single market through phased sectoral integration well in advance of formal accession.
4. Align industrial policy with economic security through the CHIPS Act, the Critical Raw Materials Act, the Net-Zero Industry Act, and the twenty-eighth regime.
In the past twenty-four months, the European Union has adopted more substantive industrial policy than at any point since the founding of the European Coal and Steel Community. The operational question is execution. The “twenty-eighth regime”—a single, EU-wide regulatory framework that companies can opt into in place of navigating twenty-seven national regimes—is the cleanest institutional remedy available. It would resolve the central paradox of European regulation: Reducing regulatory burden requires more EU-level regulation, not less. The dominant compliance cost facing European firms is divergence in national transposition, not the volume of EU rules. A twenty-eighth regime offered for high-complexity sectors—e.g., semiconductors, advanced pharmaceuticals, defense-industrial production, AI infrastructure, late-stage capital-raising—would reduce that fragmentation tax substantially without requiring treaty change.
5. Provide regulatory certainty across the full industrial stack—ETS, EDIP, STEP, the energy union, and the dual-use technology framework.
European industrial policy is criticized less for being too interventionist than for being too fragmented, complex, and unstable. Capital allocation decisions in semiconductors, batteries, hydrogen, critical raw materials, and defense-industrial capacity require ten- to twenty-year planning horizons, while investors need confidence that the regulatory framework will not change with every political cycle. The EU should therefore move away from the current ETS architecture, which has become an increasingly costly and unpredictable layer of industrial regulation, and replace it with a simpler framework that delivers emissions reductions without undermining European industrial competitiveness. At the same time, instruments such as EDIP, STEP, the Energy Union, and the dual-use technology framework should be consolidated and given durable, predictable rules.
Regulatory certainty is itself a form of industrial policy. The experience of the US Inflation Reduction Act is instructive, but its subsequent revision under the 2025 One Big Beautiful Bill Act also shows that no subsidy regime is immune to political change. The lesson for Europe is not to copy the IRA’s tax-credit mechanism, but to build industrial frameworks that provide credible long-term visibility for investors while remaining adaptable to changing economic conditions. Europe needs clearer investment signals.
6. Deepen the single market in services, capital, and digital—the largest remaining pool of unrealized productivity gain.
The IMF estimates that intra-EU barriers in services are equivalent to a 110 percent tariff. Completion of the services market, including financial services, professional services, digital services, and healthcare, would add €1.8–€2.1 trillion to EU GDP—the equivalent of adding an economy the size of Spain to the bloc’s productive output. That estimate, if anything, is conservative: It does not fully price in the second-order effects on productivity in tradable sectors that the digital and energy single markets would unlock. The political constraint on services-market completion has been the resistance of national professional bodies, regulators, and licensing authorities. The twenty-eighth regime is the mechanism for overcoming that resistance without confronting it directly: Companies and professionals opt into European frameworks where they are competitive, while national regimes remain available where they are preferred. Over time, competitive pressure bias favors the European frame. This is the same operational logic that delivered Schengen, the euro, and the energy union—incremental optionality that compounds into structural integration.
Credible 2030 vs. 2035 timeline
It is worth specifying, in operational terms, what successfully executing this program would produce by the end of the decade.
By 2030, the European Union would have completed a capital markets union and lifted European equity-market depth from approximately 60 percent to approximately 100 percent of GDP; would have absorbed Moldova and Montenegro as full member states, with Serbia, Bosnia, Kosovo, North Macedonia, Albania, Ukraine and Georgia, on credible accession trajectories; would have raised the EU share of global semiconductor production from approximately 10 percent to approximately 20 percent; would have completed the structural break with Russian pipeline gas and lowered its Chinese critical-minerals dependency through the binding targets of the Critical Raw Materials Act; would have raised aggregate defense-industrial production capacity by a factor of five against the 2022 baseline through ReArm Europe and the structural integration of the Ukrainian defense industry; would have stabilized aggregate government debt at 90 percent of GDP, against US debt at projected 139 percent and Chinese debt at projected 124 percent; and would have completed the single market in services with a productivity uplift in the range of €1.8–€2.1 trillion. This is not wishful thinking. Each measure is already on a European institution’s 2026 agenda. The only question is whether there’s the discipline and political will to execute the program.
By 2030, credible execution would produce: capital markets union legislative framework complete with European’s Securities and Markets Authority consolidated supervision, equity-market depth at 85 percent of GDP; Ukraine and Moldova in phased single-market access with customs-union integration substantially advanced, Montenegro and Albania with accession treaties signed (full membership for Ukraine is a 2033–2035 event); TSMC Dresden operational at initial scale, with the EU semiconductor share at 13–15 percent (the 20 percent target is achievable by 2032–33 given four-to-five-year fab construction cycles); defense-industrial production at three times the 2022 baseline (the fivefold target is a 2033–2035 objective); aggregate government debt stable at 85 percent of GDP; and the twenty-eighth regime operational for at least three high-complexity sectors. The €1.8–€2.1 trillion services-market GDP uplift, equity depth at 100 percent, semiconductor share at 20 percent, and full Ukrainian accession are 2035 goals. This is the same ambition on a realistic timeline. The difference matters because credibility with investors, allies, and adversaries depends on delivering what is promised, when it is promised.
The realistic risk register
The obvious counterpart to the preceding analysis is the risk register. Several risks could derail this strategy. The first is the conversion problem. As Chapter 1 argues, Europe’s strategic mindset has evolved more rapidly than its institutional architecture. Decision-making remains optimized for consensus rather than crisis tempo, meaning that doctrine may outpace the operational capacity to implement it. The persistence of these institutional constraints across successive crises suggests that political ambition alone will not guarantee execution.
A second risk is fragmentation under pressure. Simultaneous geopolitical and economic shocks encourage member states to optimize for national rather than European interests—Germany on energy, France on nuclear power, Poland on defense, and the Netherlands on financial services—at the expense of collective coherence. Hungary’s repeated use of vetoes, Slovakia’s alignment with Russia on defense procurement, and divisions across southern Europe on China illustrate how compounded crises amplify centrifugal forces. A broader populist shift across additional member states could further weaken political support for enlargement, higher defense spending, and the costs of the green transition.
External shocks present equally significant vulnerabilities. Sustained US tariff escalation against European exports would directly undermine the manufacturing sectors that remain central to the continent’s economic model. A disorderly slowdown in China would simultaneously reduce demand for European exports while increasing competitive pressure through discounted Chinese goods. Likewise, a prolonged disruption in the Strait of Hormuz would drive up LNG prices, eroding one of Europe’s key comparative advantages—its relatively high standard of living—through multiplicative cascading effects on energy, fertilizers, and food prices.
Structural challenges could prove equally consequential. Faster-than-expected demographic decline, continued emigration of skilled workers, or tighter constraints on immigration would weaken Europe’s labor force, fiscal capacity, and long-term growth potential. At the same time, deepening dependence on American AI platforms and cloud infrastructure risks creating strategic vulnerabilities that financial integration alone cannot address.
Finally, Europe faces a fundamental climate-competitiveness-security trilemma. It cannot simultaneously sustain the world’s most ambitious decarbonization agenda, preserve the deepest integrated single market, and maintain the most open trading model among major economic blocs without making explicit strategic tradeoffs. Unless policymakers clearly define which objectives take precedence under different conditions, the pursuit of all three goals producing policy incoherence. A strategy that cannot withstand its most probable failure modes is unlikely to succeed when those failures materialize.
The endowment already exists
This report has set out Europe’s structural balance sheet in operational detail because the alternative—relying on the cultural habit of European self-deprecation—leads to political and strategic underweighting of the bloc’s actual position. The European Union is not the impotent civilian power of the declinist commentary. Nor is it the seamless strategic actor of the most optimistic federalist visions. It is both more specific and more analytically interesting: a middle power of continental scale with structural assets sufficient to navigate Cold War 2.0 if it chooses to deploy them at the tempo the moment requires.
The simultaneity engine is built. The capital is available. The trade leverage exists. The fiscal stance is there. The human capital is ready. The energy architecture has been rebuilt. The defense-industrial base is being reconstructed. The single market is the world’s largest integrated economic space. The euro is the world’s second reserve currency. European universities, courts, and regulatory institutions continue to set the legal and contractual standards on which global commerce runs.
What is required is not new endowment but rather the institutional discipline, strategic confidence, and willingness to deploy compound power at compound tempo.
The endowment is already there. The constraint is its activation.
What is missing is the institutional machinery and the collective mindset to convert it. The adversary assumes that Europeans are too comfortable, too hedonistic, and too accustomed to peace to sustain strategic, or even civilizational effort. That bet against European resolve has been wrong before. Stalin made that bet against Finland in 1939. Putin made it against Ukraine in 2022. Both were wrong. But proving the assumption wrong requires what the Finns call sisu: the capacity to keep going when circumstances seem impossible. That capacity cannot rest in a single leader or institution. It must be embedded in a society that understands security is no longer someone else’s responsibility.
While the conversion problem this report has diagnosed is institutional, it is also cultural. For a generation, Europe treated security and peace as a given rather than something that required active maintenance. That assumption is now bankrupt. The mindset shift that replaces it must run deeper than defense budgets and procurement schedules. It must reach the point where European societies accept that bureaucratic perfection is the enemy of strategic tempo. A perfectly completed spreadsheet is worth nothing if it delivers no innovation, no ammunition, no deployable capability when the capability is needed. Europe does not need a coalition of the willing. It has had coalitions of the willing for decades, and they have produced statements and action plans. What it needs is a coalition of the doing—governments, industries, companies and citizens prepared to remove the procedural obstacles that make the interval between political decision and operational delivery intolerably long.
The honest accounting requires one other admission. The endowment documented in this report is not limitless. The demographic window is closing. The AI dependency risk deepens every year that sovereign compute and deployment infrastructure are not built. The fiscal space that distinguishes Europe from the United States and China will narrow as age-related expenditure rises. The defense-industrial scaling targets are achievable, but on a 2033–2035 timeline, not a 2030 timeline—and only if labor-market constraints and procurement reform are addressed simultaneously. These are not reasons for pessimism. They are the right reasons for urgency. A strategy that mistakes its own endowment for an indefinite option is a strategy that will discover too late that the option has expired.
In a world where three men in Washington, Moscow, and Beijing hold disproportionate sway over the fate of eight billion people, the case for a fourth center of strategic gravity such as a European Union that has converted its structural weight into operational agency is not just aspirational. It is existential. The question is no longer whether Europe has the resources. It is whether Europe has the will, the institutional discipline, and the collective sisu to deploy those resources before the geopolitical window closes.
About the authors
Piotr Arak is a nonresident senior fellow with the Atlantic Council’s Europe Center. Arak is an economist with extensive experience across government, academia, and the private sector. From 2018 to 2023, he served as director of the Polish Economic Institute, where he built the organization into one of the most influential think tanks in Central and Eastern Europe. He is currently chief economist at VeloBank and lectures as an assistant professor at the Faculty of Economic Sciences at the University of Warsaw. His expertise covers international trade as well as fiscal and monetary policy. Earlier in his career, Arak worked at Deloitte, the analytical center Polityka Insight, the United Nations Development Programme, and the Polish prime minister’s office. He holds a PhD and an MA in social sciences from the University of Warsaw, an MBA from the Université du Québec à Montréal and the Warsaw School of Economics, and an executive certificate in economic development from Harvard Kennedy School.

Velina Tchakarova is the founder of FACE (For A Conscious Experience), a Vienna-based geopolitical intelligence firm. Tchakarova is a geopolitical strategist and certified strategic foresight expert with twenty-six years of professional and academic experience spanning security, defense, and strategic foresight. She previously served as director of the Austrian Institute for European and Security Policy and lectured at the Real-World Risk Institute, founded by Nassim Nicholas Taleb. She serves on the European Security Forum Network in Finland, the Scientific Advisory Board of the European Forum Alpbach, and the Strategic and Security Policy Advisory Board of the Austrian Federal Ministry of Defense, and is a board member of the Vienna Economic Forum. She holds an MA in political science from the University of Heidelberg and a BA in political economy from the University for World and National Economy in Sofia. She earned a certification in mastering foresight at the George Washington University Center for Excellence in Public Leadership and is completing a doctoral dissertation at the University of Vienna, Austria.
Acknowledgements
The authors are grateful to James Batchik and Jörn Fleck for their extensive and rigorous review of this report at every stage of drafting, and for the many substantive comments that sharpened its argument and its evidence. They also thank Bart Piasecki, Nina Kruzewska, Samantha Wong, and Andrew D’Anieri for their close reading and valuable feedback on individual chapters. The authors further thank colleagues at the Atlantic Council’s Global Energy Center, the China Hub, and the Western Balkans Team for their review of the sections touching their respective areas of expertise. Emma Nix provided the graphics and data visualization. The authors alone are responsible for the analysis, conclusions, and any remaining errors.
Related reading
Explore the program
The Europe Center promotes leadership, strategies, and analysis to ensure a strong, ambitious, and forward-looking transatlantic relationship.
Image: European Union, 2026.