As we approach Halloween, the prize for the scariest costume may belong to the U.S. economy itself: Dr. Jekyll and Mr. Hyde.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
Last week, two hotter-than-expected inflation reports out of the United States appeared to suggest that the Federal Reserve remains well behind the curve. Yet Treasury yields barely reacted. That shouldn’t be surprising, as bond investors, who have a habit of seeing through the noise faster than equity markets, appear to recognize something important: This is not traditional demand-driven inflation.
Instead, inflation continues to move higher primarily because of supply-side forces that interest rates cannot easily fix. Gasoline alone accounted for more than half of September’s monthly increase in consumer prices while energy represented more than half of the increase in producer prices and more than 80 per cent of the rise in goods prices. Raising interest rates may reduce demand, but it does little to increase oil production or resolve geopolitical disruptions affecting global energy markets.
Canada's best source for investing news, analysis and insight.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of Investor will soon be in your inbox.
We encountered an issue signing you up. Please try again
As a result, what we’re witnessing is a deeply divided economy. Dr. Jekyll is the multitrillion-dollar artificial intelligence buildout. A handful of technology giants are spending at a pace rarely seen outside of wartime mobilization, building data centres, power infrastructure, semiconductor capacity and digital ecosystems. The scale of this investment is extraordinary. The Goldman Sachs Group Inc. estimates global AI-related investment could approach US$800 billion in 2026 and ultimately surpass US$1 trillion annually later this decade. It is creating thousands of likely temporary construction and infrastructure jobs, driving capital expenditures and supporting a surge in economic activity, but it is also creating the illusion that the broader economy is far stronger than it really is.
Mr. Hyde is everything lurking underneath.
Away from the AI headlines, much of Main Street America is hurting. Consumers are becoming increasingly selective with their spending after years of elevated inflation eroded purchasing power. Just as conditions appeared to be stabilizing, the conflict with Iran sent energy prices sharply higher, once again squeezing household budgets. According to the U.S. Bureau of Labor Statistics, real average hourly earnings declined 0.7 per cent over the past year after adjusting for inflation. Workers partially offset that loss by working longer hours, leaving real weekly earnings essentially unchanged. In other words, many Americans are not getting ahead. They are simply working more to maintain the same standard of living.
The housing market offers perhaps the clearest example of this growing divide. Existing home sales remain stuck near post-financial-crisis lows, while sellers now outnumber buyers by roughly 63 per cent, the largest imbalance in more than a decade. In much of the country, affordability has deteriorated to the point where prospective buyers simply cannot make the math work.
Credit markets are sending similar signals. Regional banks remain heavily exposed to commercial real estate, particularly office buildings, where vacancy rates have exceeded levels reached following the Global Financial Crisis and delinquency rates are about 12 per cent. At the same time, private equity firms are grappling with a financing environment that bears little resemblance to the era of near-zero interest rates that fuelled much of their growth. Increasingly, sponsors are being forced to inject fresh capital into struggling portfolio companies, restructure debt and extend maturities simply to keep businesses afloat.
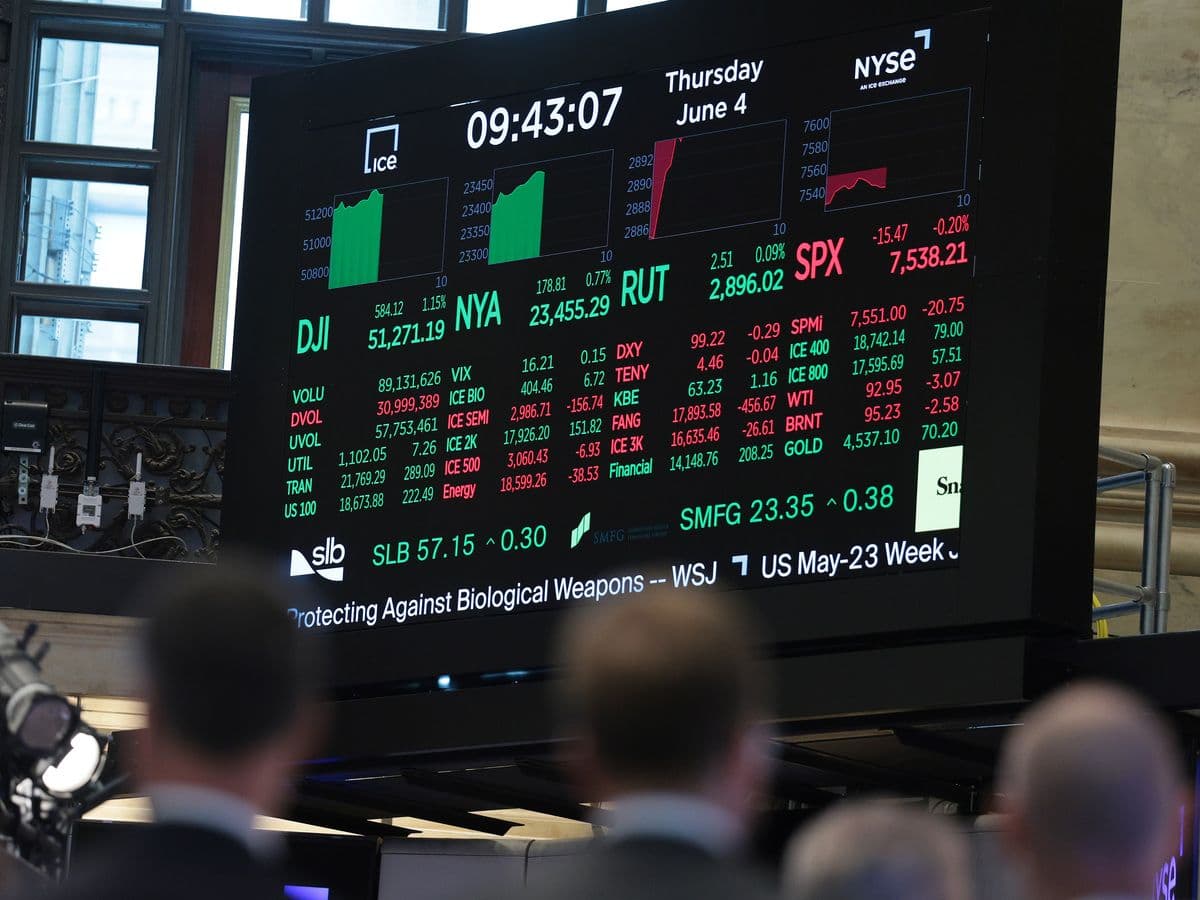
This same divergence is playing out in public markets. While the S&P 500 sits near record highs, the average stock tells a very different story. Approximately 60 per cent of the index’s constituents are already down more than 20 per cent from their highs, while nearly one-third have suffered drawdowns exceeding 40 per cent. Think about that.
Ultimately, U.S. policymakers will no longer be able to ignore what the bond market is telling them. Financing trillion-dollar deficits while simultaneously funding a multitrillion-dollar AI buildout becomes increasingly difficult when energy shocks continue to fuel inflation and keep capital costs elevated. Unless the global energy supply situation stabilizes, both government borrowing costs and private-sector financing costs are likely to remain under pressure.
My concern is that policymakers and equity investors remain fixated on Dr. Jekyll. They see the data centres, the capital spending, the soaring technology stocks and the headline economic growth. What they are failing to see is Mr. Hyde slowly deteriorating beneath the surface: the consumer stretched thin; housing activity near recessionary levels; stressed lenders and increasingly narrow market leadership.
Canadian investors would be wise to pay attention. The major U.S. equity indexes now represent an increasingly large share of many Canadian portfolios, whether directly through U.S. holdings or indirectly through pension funds, mutual funds and exchange-traded funds. More importantly, Canada’s economy also remains heavily tied to the health of the United States through trade, investment flows and corporate earnings. If the weakness beneath the surface of the U.S. economy eventually becomes impossible to ignore, the impact is unlikely to stop at the border.
Eventually, the economy’s split personality will resolve itself. The only question is whether policymakers recognize the growing divergence in time. If they remain focused solely on Dr. Jekyll, they risk being blindsided by Mr. Hyde. And for investors on both sides of the border, that is the risk that matters most.
Martin Pelletier, CFA, is the author of Investing Through the Storm and a senior portfolio manager at TriVest Wealth, a team that is part of Wellington-Altus Private Counsel Inc. TriVest provides discretionary risk-managed portfolios, investment audit/oversight and advanced tax, estate and wealth planning. The opinions expressed are not necessarily those of Wellington-Altus.
_____________________________________________________________
If you like this story, sign up for the FP Investor Newsletter.
Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.