Published : 19 October 2026
•
Updated : 19 October 2026, 01:31
Mehedi Hasan
The Carbon Border Adjustment Mechanism (CBAM), which the EU’s co-legislators signed on 10 May 2023 to counter the risk of ‘carbon leakage’ – carbon-intensive production moving to countries with weaker climate rules – entered its definitive, financial phase on 1 January 2026. This followed a two-year transitional, reporting-only period that began in October 2023. CBAM is the first border carbon adjustment of its kind to be implemented anywhere in the world: importers now face a charge based on the emissions intensity of the goods they import.
For now, CBAM covers six emissions-intensive sectors: cement, iron and steel, aluminium, fertilisers, hydrogen, and electricity. Its main aim is to ensure fairness for EU producers, who already bear the costs of the EU Emissions Trading System (EU ETS). As the EU’s then trade chief, Valdis Dombrovskis, put it: “The European Commission had designed CBAM carefully so that it was compatible with WTO rules, applying the same carbon price on imported goods as on domestic EU producers.”
Bangladesh’s ready-made garment sector is unlikely to fall directly under the EU’s Carbon Border Adjustment Mechanism (CBAM), although certain garment inputs could face indirect cost pressures. Photo: Amran Hossain
The first question this raises is whether CBAM is a climate policy or a trade barrier. Brussels’ answer is the former: a climate measure designed to comply with WTO rules.
To begin with, the carbon cost will increase the product's price for the importer. Under the basic law of demand, a higher price tends to reduce the quantity demanded. To stay competitive, the producer will therefore need to cut its emissions; if it cannot, its exports could suffer.
Importers can deduct the corresponding amount if they can prove that a carbon price has already been paid during production of the imported good. But can a country realistically set a carbon price equivalent to the EU’s – for the same volume of emissions and the same volume of production? The exchange rate is a further complication: if a country fixes its carbon tax in local currency, can that rate be reliably kept in line with the EU price to create a level playing field?
Another problem is that the carbon cost on importers is likely to raise overall production costs, because importers will tend to pass it back to producers rather than absorb it themselves. In effect, the tax on the importer becomes an indirect tax on the producer – who ends up paying it in the very country where the emissions occurred, in the name of fairness for producers in the importing country. This is the central problem with CBAM.
From the exporting country’s perspective, this looks unjust and lacks a clear rationale. How can the EU tax emissions that did not occur on its own territory and still call it a climate policy? Will that revenue be transferred to the country where the emissions happened, to help compensate for the environmental damage? In all likelihood, it will not. If it were returned to the exporting country’s government, the measure could, to some extent, be considered fair. Money collected under a carbon tax and climate policy ought to be subject to a transparent accounting system that channels it to its rightful beneficiaries – in this case, the exporting countries where the emissions occurred. Alternatively, could the revenue be directed towards global climate finance, such as Loss and Damage or adaptation?
Consider the climate finance record of developed countries, the EU among them.
The EU’s Carbon Border Adjustment Mechanism entered its definitive phase on January 1, 2026, introducing carbon-related obligations for imports from six emissions-intensive sectors. Photo: Reuters
At the 2009 UN Climate Conference, developed nations pledged to mobilise USD 100 billion annually by 2020 to help developing nations with climate mitigation and adaptation. According to the OECD, this commitment was met for the first time in 2022, reaching USD 115.9 billion. However, the ‘Climate Finance Shadow Report 2025’, published by CARE Climate Justice and Oxfam, finds that the true value of this support – once loan interest and repayments are accounted for – is only around USD 28–35 billion. This large gap arises because roughly two-thirds of this support is delivered as loans, often at market rates, rather than as the grants that were promised to help vulnerable nations adapt to a crisis they did not cause.
In 2024, Reuters conducted an extensive investigation into global climate funds. It focused on USD 189 billion disbursed as direct country-to-country payments, out of roughly USD 353 billion paid between 2015 and 2020 under the USD 100 billion pledge, which was first made in 2009 and reaffirmed in the 2015 Paris Agreement. Reuters’ analysis found that a significant share of this money flows back to wealthy countries through loan repayments, interest, and tied work contracts. The investigation found that wealthy nations have loaned at least USD 18 billion at market-rate interest – including USD 10.2 billion from Japan, USD 3.6 billion from France, USD 1.9 billion from Germany, and USD 1.5 billion from the United States. It also found at least USD 11 billion in loans, almost all from Japan, that required recipient nations to hire companies or buy materials from the lending country. At least USD 10.6 billion in grants from 24 countries and the EU carried similar conditions, requiring recipients to engage companies, non-profits, or public agencies from the donor country.
Climate finance is supposed to be driven by the needs and priorities of recipient countries, not to be a business opportunity for developed ones. The gap between what developed countries pledge and what they deliver suggests a system that prioritises creditors’ returns over climate justice.
Climate finance is supposed to be driven by the needs and priorities of recipient countries, not to be a business opportunity for developed ones. The gap between what developed countries pledge and what they deliver suggests a system that prioritises creditors’ returns over climate justice.
Given this record, one can reasonably infer that CBAM revenue is unlikely to be returned directly to exporting countries – a serious gap in the mechanism’s design. A tax imposed to establish fairness for EU producers can end up creating unfairness for exporting countries, particularly when those countries never see the revenue.
What should exporting countries do?
We believe that, if CBAM is here to stay, the best response for exporting countries is to introduce their own carbon tax on export goods as early as possible. Doing so would allow them to capture and retain the value of their own emissions pricing, rather than ceding it to the EU. Exporting countries that delay such a tax face a double loss: they bear the environmental cost of the emissions without capturing any of the corresponding fiscal benefit.
Concern for Bangladesh
Although Bangladesh exports few of the products CBAM currently covers, the mechanism unsettled Bangladeshi businesses from the moment it was first discussed. In 2023, the Federation of Bangladesh Chambers of Commerce & Industry (FBCCI), the apex body representing Bangladeshi businesses, responded by submitting recommendations to the EU through the Ministry of Commerce. FBCCI highlighted potential contradictions with WTO rules and argued that CBAM fails to account for the specific circumstances of Least Developed Countries (LDCs) and countries transitioning out of LDC status. Because LDCs generally lack the administrative and business-level capacity to comply with a complex carbon-tax system, FBCCI recommended that they be kept out of CBAM’s scope altogether – or, at minimum, exempted until a proper Measurement, Reporting and Verification (MRV) system for emissions is established in these countries.
The European Commission’s review report of 16 December 2025 expects CBAM’s impact on the poorest countries to be minimal: LDCs do not export significant volumes of CBAM-covered goods, and the Commission puts the resulting impact on their economies at less than 0.01% of GDP.
In response to developing countries’ concerns, the EU has pointed to development funds and technical assistance as the route for helping countries decarbonise and reduce their future exposure to CBAM. Such funds could help a country like Bangladesh move towards cleaner technologies and energy systems. But they could also add costs: to the extent that this support comes from the EU’s development budget as loans rather than grants, Bangladesh would have to repay it – ultimately placing a further burden on exporters.
Separately, in October 2025, the EU adopted a simplification regulation that, among other things, exempts importers who import less than 50 tonnes of CBAM goods per year from the mechanism’s obligations. The change is expected to remove the great majority of importers, mostly small ones, from CBAM’s administrative scope while still capturing the overwhelming share of the emissions the mechanism is designed to price. This is a welcome simplification, though it does not change the picture for Bangladesh, whose exposure to the current six-sector scope is minimal in any case.
For now, then, Bangladesh need not worry a great deal, since it does not export significant volumes of the high-emission products currently covered – steel, aluminium, cement, fertilisers, or electricity. Its production of these items is concentrated on meeting domestic demand. Looking ahead, however, two concerns have been raised: first, that an expansion of CBAM’s product scope could eventually bring ready-made garments (RMG), Bangladesh’s principal export, under the mechanism; and second, that graduation from LDC status would reduce Bangladesh’s access to certain EU support measures relevant to CBAM.
The EU’s carbon border tax aims to discourage carbon-intensive production, but concerns remain over whether it places an unfair burden on developing economies. Visual: Star
Recent developments make both concerns easier to assess than they were even a few months ago.
On the first concern, RMG, the scope-expansion process has moved quickly since the Commission’s review, and its direction is telling. The Commission’s proposal of 17 December 2025 would add roughly 180 ‘downstream’ products – manufactured goods made from materials already covered by CBAM – to the mechanism’s scope, with effect from 1 January 2028. The Council’s general approach of 12 June 2026 went further, adding some 200 metal-intensive industrial, construction, and electrical-equipment goods to the Commission’s list. The European Parliament’s environment committee, in its report of 9 July 2026, went further still, proposing to bring around 457 product groups into scope. Parliament’s plenary is expected to adopt its own position in September 2026, after which the file moves into trilogue negotiations with the Council. The products under discussion have one thing in common: a high steel or aluminium content (around 79% on average, by the Commission’s estimate). They include fabricated metal goods, machinery, vehicle components, and household appliances. Finished garments, fabrics, and other RMG products do not meet this criterion and are not on any of these lists.
Looking further ahead, the Commission’s December 2025 review reaffirms the EU’s ambition of eventually bringing CBAM’s scope into line with the sectors covered by the EU ETS, with 2030 cited as a working horizon. The sectors usually named for this ‘horizontal’ expansion are glass, ceramics, pulp and paper, bulk and organic chemicals and polymers, and oil refining – precisely because they are already inside the EU ETS. Garment and textile manufacturing is not part of the EU ETS, so it does not appear among the sectors under consideration for this pathway either. On the evidence available today, then, EU policy does not appear to be heading towards bringing RMG directly under CBAM, either by 2028 or by 2030.
That said, Bangladesh’s RMG sector is not entirely insulated from this process. Some of the downstream product lists under discussion include metal fittings and hardware – buttons, zip fasteners, buckles, and similar trims – that are common garment inputs. Should such items eventually be classified and taxed as standalone CBAM goods rather than as components of a finished garment, Bangladeshi garment manufacturers that import these inputs – and their upstream suppliers – could face indirect cost effects. This risk is much narrower than the direct inclusion of RMG and remains unsettled, but it is worth monitoring as the legislative process concludes over the coming months.
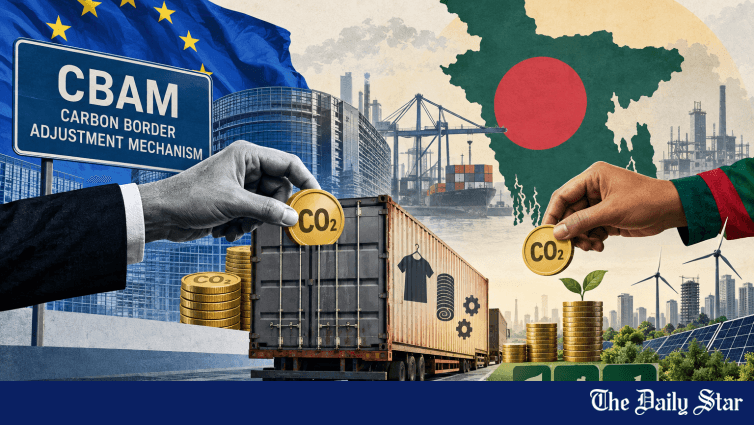
Introducing its own carbon tax could allow Bangladesh to retain revenue from carbon pricing rather than ceding it to the EU under its Carbon Border Adjustment Mechanism. Visual: AI-generated.
On the second concern, LDC graduation is no longer a question of ‘if’. Bangladesh’s graduation has been formally confirmed for 24 November 2026. The interim government’s Advisory Council reaffirmed in March 2025 that the transition would proceed on schedule, despite calls from some business groups for a deferral. This remains a concern in the CBAM context: any future CBAM-related technical assistance or preferential treatment tied to LDC status will cease to apply to Bangladesh from that date, even as the country is still building the MRV systems and decarbonisation capacity that such support is meant to help develop.
The Commission’s scope-expansion proposal and the Council’s and Parliament’s subsequent positions now give exporting countries such as Bangladesh a reasonably concrete picture of which product lines are being added in the near term, and on what timeline. What remains open is the second, further-reaching review the Commission has scheduled for 2027, covering additional scope extension – including indirect emissions and ‘other sectors’. Until that review concludes, there is no definitive list of the products CBAM will cover over the next five to six years. Bangladeshi exporters and policymakers need to track that 2027 review closely – even though, on present evidence, RMG itself is unlikely to feature in it.
Mehedi Hasan is an additional director for communications and advocacy at Business Initiative Leading Development (BUILD). He can be reached at [email protected].
Send your articles for Slow Reads to [email protected]. Check out our submission guidelines for details.