France's government bond yields climbed to their highest level in 25 years as the country has yet to contain its fiscal crisis. Despite budget-cutting pledges from presidential contenders, France's national debt now stands at roughly 10 times that of Greece when it was engulfed by its own crisis in 2010.
The yield on France's 10-year government bond approached 5% earlier this month before trading at around 4.8% on the 12th, Bloomberg reported. That marks a sharp jump from below 4% two months earlier. On the 10th, the risk premium over Italian bonds hit a record high. The premium on 10-year French debt over German bunds also rose to its highest since 2012.
France generates about 3 trillion euros (4,481 trillion won) in gross domestic product a year, but its debt totals roughly 3.6 trillion euros. The debt ratio is projected to exceed 120% of GDP within the next year, a steep climb from below 100% in 2019. France's current debt load is about 10 times the size of the Greek debt that triggered a fiscal crisis in 2010.
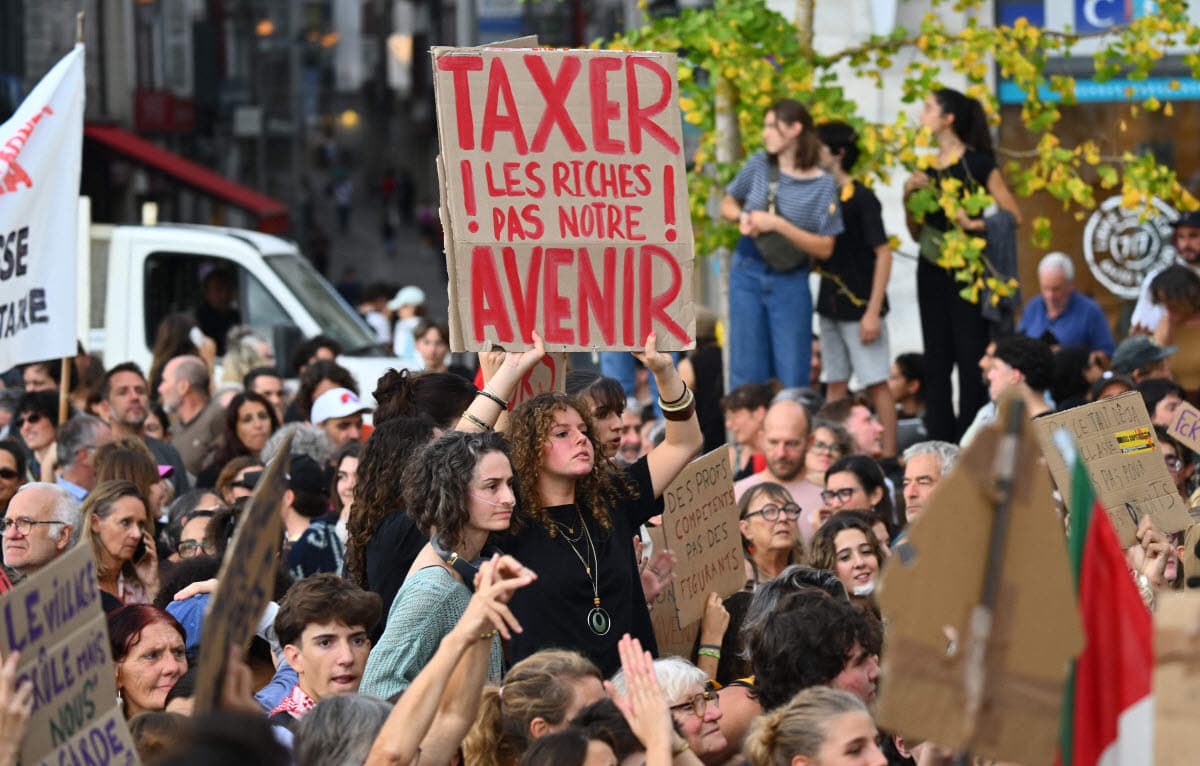
Student protests that authorities have been unable to quell have fanned concerns over the debt. The demonstrations, which began in late September this year, spread nationwide and turned violent in some cases. Protesters are demanding an additional 10 billion euros in education funding. Yet France's interest payments alone will top 90 billion euros (134 trillion won) next year, exceeding its annual education budget. In effect, the treasury is empty just as it faces angry crowds in the streets.

The biggest concern is that the strains are showing signs of spreading to other European sovereign bonds. Yields on 10-year debt issued by Italy and Greece, which are fiscally vulnerable alongside France, have risen to about 120 basis points and 100 basis points above German yields, respectively. A basis point equals 0.01 percentage point. Wider spreads indicate greater perceived risk relative to comparatively safe Germany. That has revived talk in the market of "contagion" from the debt crisis that erupted in Greece 15 years ago.
Michel Sapin, who served as finance minister in the early 1990s and again from 2014 to 2017, said a slowdown in economic activity, the severity of the budget crisis and anxiety over the presidential election have all converged. Political uncertainty is magnifying and amplifying genuine concerns, he said.
European Central Bank policymakers have signaled that emergency measures are not yet needed. Still, the chances that the ECB will raise rates at its monetary policy meeting on the 29th of this month are diminishing. Michael Theurer, a member of the Bundesbank executive board, said in a recent interview with Deutschlandfunk radio that there is no systemic sovereign debt crisis at present but that risks have risen considerably.
Pimco, one of the world's largest bond investors, said last week that it was maintaining a long-standing position of significant underweight on French government bonds and expected pressure to keep building. Thierry Wizman, a rates strategist at Macquarie Group, said the selloff in French bonds and the social unrest now work as a single loop, and that ending one crisis would help resolve the other.