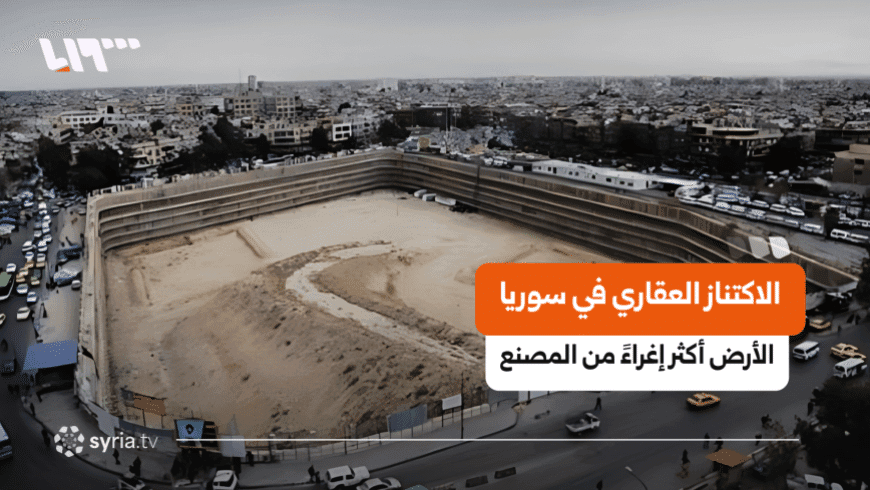
In Aleppo, a plot of land once occupied by the Albi Tex textile factory is being cleared for a new property development. Instead of machinery returning to operation and workers to production lines, the site will soon accommodate residential buildings under the Albi project, announced by the Syrian Investment Authority and the Aleppo Governorate as part of a recently approved investment package valued at approximately 800 million dollars.
The transformation reflects a broader shift in Syria’s economic landscape. Land that once derived its worth from what a factory produced is now valued for what can be built upon it.
After years of war and destruction, Syria needs to rebuild its homes, factories and infrastructure. Yet capital appears increasingly drawn to property, while industry and agriculture continue to wait for the investment required to revive them.
This raises a fundamental question: why would an investor prefer to buy land or develop property rather than operate a factory? And what becomes of the wider economy if money continues to flow into construction while production and job creation remain stalled?
Property as a Safe Haven for Capital
From the perspective of the broader economy, the need for factories and jobs is clear. Investors, however, approach the matter differently: where can they secure a reasonable return with the least exposure to risk?
Property is a tangible asset that can be held, sold or rented. Its value may rise over time with minimal additional effort. A factory, by contrast, requires electricity, raw materials, workers and markets, alongside operating costs, marketing expenses and the uncertainties of shifting laws and regulations.
Academic and economic adviser Ziad Arabsh argues that faster returns, easier access to finance and strong demand for housing make property particularly attractive. Reviving old factories, meanwhile, requires costly equipment upgrades and reliable supplies of energy and funding.
Yet the issue extends beyond cost. Investors also need clarity about the conditions they will face several years after committing their money.
Syrian businessman Mahmoud al‑Darawi has considered launching industrial and agricultural projects but is waiting for greater legal stability and a more predictable business environment. An investor may prepare a feasibility study based on existing customs duties, only to see those duties change once the project is under way, undermining the entire calculation.
For al‑Darawi, the stability of regulations can matter more than their precise terms. Investors can adapt to demanding conditions when the rules are clear and consistent. Long‑term planning becomes far more difficult when those rules change repeatedly.
Buying land and waiting for its value to appreciate can therefore appear less risky than investing in a factory that may take years to become profitable.
Economists use the term “land hoarding” to describe holding land without developing it, in anticipation of rising prices. The broader concept of “property hoarding” includes buying residential or commercial units and keeping them unused in expectation of capital gains rather than occupying or renting them.
This distinction matters. Property investment does not necessarily amount to hoarding. Building homes for sale or rent is an economic activity that provides housing, services and employment. Buying property and keeping it out of use primarily to profit from rising prices, however, falls within the definition of hoarding.
Social researcher Talal al‑Mustafa links this behaviour to a lack of confidence in the future and in public institutions. When investors fear unpredictable legislation, weak infrastructure and difficulties resolving disputes, they tend to preserve their wealth in physical assets they regard as safer.
The flow of capital into land therefore reveals something about the investment climate itself. When buying a plot appears safer than operating a factory, the question becomes why productive activity has come to carry greater risks.
Selling Property Before It Is Built
Property development offers another attraction: the possibility of receiving money from buyers before construction begins.
Syrian businessman Hamza al‑Deiri explains that some developers market projects using architectural plans and visual renderings, then begin selling units and collecting advance payments to help finance construction.
If the developer acquires the land through a partnership with the state, the cost of purchasing it may also be avoided, while buyers’ instalments help cover building expenses.
Factory owners face a different financial burden. They must purchase machinery and raw materials, pay wages and operate production lines before they can sell their products and begin earning revenue.
This gives some property developments a significant financial advantage. Developers may secure part of their funding before construction, while industrial investors must often shoulder substantial costs before production begins.
Selling property off‑plan, however, carries risks. Al‑Deiri warns against collecting buyers’ money without adequate safeguards or using advance payments to finance other developments, potentially leaving purchasers with unfinished buildings and little prospect of recovering their money.
Buying off‑plan units purely to hold them until their value increases can also encourage property hoarding.
Such practices highlight the need for effective oversight to ensure that buyers’ money is spent on the projects for which it was collected and that developers possess the resources and expertise required to fulfil their commitments.
Buildings Rise, but What About Wages?
After years of destruction, displacement and forced migration, Syria urgently needs more housing. Yet the expansion of property development raises another question: can ordinary Syrians afford the homes being built?
New buildings may rise across the cities while their prices remain far beyond the reach of most families.
Economist and researcher Khaled al‑Hamdi notes that the growing interest in property, hotels and urban development is evident in recently announced projects and agreements. He cautions, however, against confusing investment announcements with projects that have actually entered construction, or assuming that investment in industry and agriculture has disappeared altogether.
Al‑Hamdi warns of the widening gap between property prices and household incomes, particularly when housing costs rise faster than wages.
For investors, a home may be a means of preserving and increasing wealth. For families, it is a basic necessity, closely tied to stability and the ability to afford education, healthcare and other essential needs.
The problem becomes more acute when developers concentrate on expensive units at a time when much of the population needs homes within reach of their incomes.
Al‑Hamdi points out that Syria’s housing crisis has deeper roots, including wartime destruction, rising construction and financing costs, a shortage of suitable homes and weak purchasing power.
Cities may therefore experience a construction boom without any corresponding improvement in residents’ ability to buy homes or afford rent.
A further concern arises at the level of the wider economy. Arabsh warns that rapid expansion in construction, without comparable growth in industry and agriculture, could increase dependence on imports and demand for foreign currency.
Buildings require cement, steel, equipment and finishing materials. If domestic factories cannot supply a sufficient share of these goods, much of the money spent on construction will ultimately flow abroad to pay for imports.
Construction also creates valuable employment, although some jobs disappear when projects are completed. Factories, by contrast, can provide work over many years while developing workers’ skills and expanding domestic production.
When Ownership Matters More Than Work
The effects of property hoarding extend beyond housing prices. They also influence how wealth and opportunity are distributed across society.
Those who own land or buildings may see their wealth increase as prices rise, even without engaging in productive activity. People who depend on wages, meanwhile, may spend years saving for a home, only to discover that rising prices have pushed it further beyond their reach.
Talal al‑Mustafa believes that this widening divide could deepen inequality between those who own property and other assets and those who rely on their work to earn a living.
The issue is particularly sensitive in Syria, where many families lost their homes and possessions during the war, displacement and forced migration. Others retained properties they can sell or rent out, benefiting from their increasing value.
The consequences are especially apparent among young people. A young Syrian may spend years studying, working and acquiring professional skills without coming any closer to owning a home, while someone else may make substantial gains simply because a property they already own has risen in value.
Al‑Mustafa warns that continued inequality of this kind could undermine young people’s confidence in education and work as routes to a better life. Some may turn to emigration, property speculation or dependence on family wealth and inheritance to secure housing.
At this point, the issue reaches beyond the property market to the question of equal opportunity and the relationship between individual effort and financial reward.
When owning land becomes a quicker path to wealth than working or producing goods, investment decisions change, and so may an entire generation’s expectations of the future.
How Can Investment Be Drawn Back into Industry?
Simply urging investors to establish factories and agricultural projects is unlikely to achieve much. Capital generally flows toward opportunities that offer reasonable returns at acceptable levels of risk.
Talal al‑Mustafa therefore argues that the state should make productive investment more attractive by reducing its risks and linking incentives to measurable results, such as the number of jobs created, wages paid and goods produced.
This begins with reliable electricity and energy supplies, access to finance, protection of property rights, simpler administrative procedures and stable legislation. Investors need an environment in which they can estimate their costs and potential returns over the long term.
Ziad Arabsh takes a similar view, calling for the removal of obstacles to production, affordable financing, improved infrastructure and protection for emerging industries against unfair competition, while ensuring that manufacturers can obtain the materials and equipment they need at reasonable prices.
Mahmoud al‑Darawi likewise stresses the importance of stable policies on imports, exports and customs duties, allowing investors to make long‑term plans with greater confidence.
Another obstacle lies in the experience of investors themselves.
Someone accustomed to buying and developing property may possess considerable capital without having the expertise to run a factory or agricultural enterprise, with all the demands of daily operations, workforce management, costs and marketing.
Al‑Darawi therefore proposes partnerships between investors and experienced operators, along with specialised companies and investment funds that would allow capital to enter productive sectors without requiring investors to manage the businesses themselves.
Hamza al‑Deiri, meanwhile, argues that Syria should be viewed as a market capable of producing goods for domestic consumption and export. He calls for drawing on the experience and connections of Syrians living abroad to attract new investment into industry, technology and other economic activities.
These proposals share a central objective: making investment in factories sufficiently profitable and predictable for investors to trust in its long‑term prospects.
The Property Market Needs Rules Too
Alongside efforts to encourage productive investment, property development itself requires clear regulations to protect buyers and govern the activities of developers.
Hamza al‑Deiri proposes establishing a government body to oversee advance payments made by buyers. The funds would be held securely and released gradually as construction progresses, under supervision designed to ensure that they are spent on the projects concerned.
He also calls for assessing developers’ financial and technical capabilities before granting approval for projects, including reviewing their previous experience and ability to meet contractual obligations.
Such measures could discourage developers without sufficient resources from entering the market and protect buyers’ money from being used to finance poorly planned expansion.
Khaled al‑Hamdi, for his part, advocates greater incentives for projects that create lasting jobs, increase domestic production and boost exports, alongside clear measures of their economic and social impact.
He also emphasises the need to encourage affordable and mid‑priced housing, expand mortgage finance and link certain incentives to the provision of homes that a broad range of Syrian households can afford.
Reconstruction itself could provide opportunities to revitalise industry.
Building projects require construction materials, equipment, furniture, engineering services and transport. All these needs could generate sustained demand for locally produced goods and services, provided Syrian businesses can compete on quality and price.
In this way, the benefits of reconstruction could spread from building sites to factories, workshops and markets, creating jobs that continue long after individual projects are completed.
Who Will Live in the Cities We Are Building?
Syria needs to rebuild its homes, roads and factories. It also needs investment that creates jobs and incomes, allowing people to rebuild their lives.
Yet the value of announced investments and the number of new projects tell only part of the story of economic recovery. What matters most is how many jobs are created, how much production returns to the market and whether families can improve their living standards and meet their basic needs.
Cities may change beyond recognition, new towers may rise and land prices may soar, while ordinary Syrians continue to face the same familiar questions: where can they find work that pays enough, and how can they earn a salary that allows them to rent or buy a home?
In a country that has lost so many factories, homes and jobs, decisions about where investment should go will help determine the kind of economy that emerges from reconstruction.
Land that once accommodated a factory can be turned into a property development, generating returns, housing and employment. Yet other factories remain idle, waiting to resume production, while families need jobs and incomes that will allow them to live in the cities being rebuilt around them.
Here lies the cost of property hoarding: land values rising faster than the economy’s ability to create jobs and increase incomes, until property becomes a store of wealth rather than a place to live or produce.
What will Syria gain if the value of its land continues to rise while its people cannot afford even a single square metre of it?
This article was translated and edited by The Syrian Observer. The Syrian Observer has not verified the content of this story. Responsibility for the information and views set out in this article lies entirely with the author.
The post Property Hoarding in Syria: Why Has Land Become More Attractive Than Factories? first appeared on The Syrian Observer.